
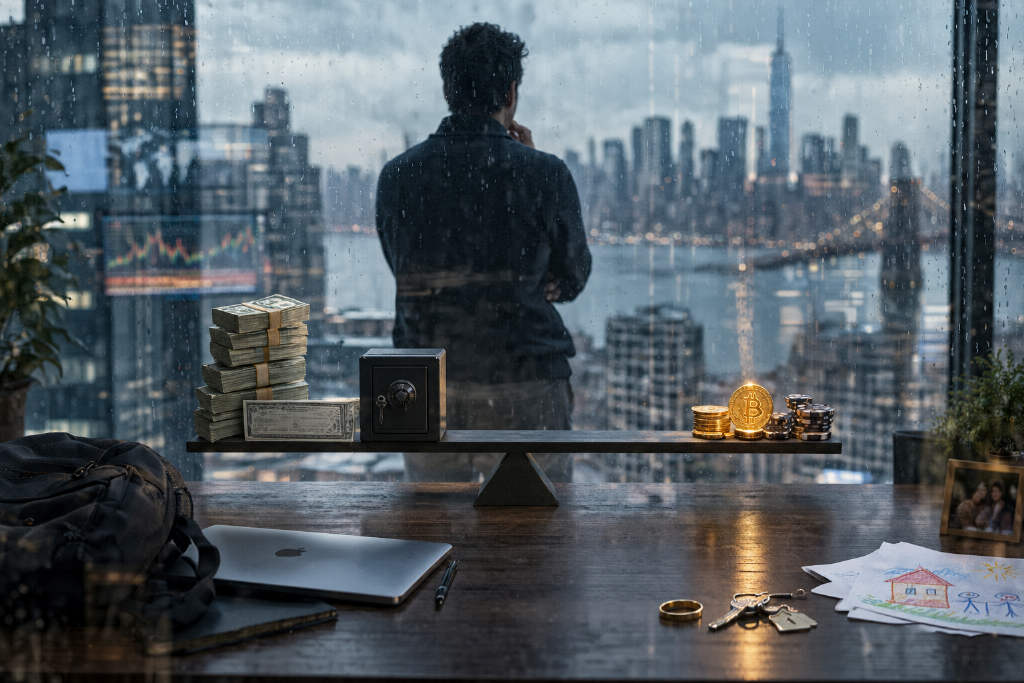
How much cash a person should hold, including cash equivalents such as government bonds, has produced very different answers from prominent investors.
Duan Yongping has said he remains fully invested in stocks because he does not like holding cash. Ray Dalio has argued that cash is trash. Warren Buffett has said that in the instructions for the assets he plans to leave his family, 10% should go to short-term Treasuries and 90% to the S&P 500. Nassim Nicholas Taleb, author of The Black Swan, has taken a much more extreme position through his barbell strategy: 90% in cash and short-term government bonds on the left side, and 10% in highly risky bets with large upside on the right.
In the PANews column, Bill Qian writes that these apparently conflicting views make sense once the question is framed correctly: it depends on who is asking.
A framework, not a fixed ratio
The article presents Taleb’s barbell strategy as a useful framework for thinking about cash rather than a universal allocation rule. The structure is simple: heavy on both ends and thin in the middle. The left side holds extremely safe assets that protect a person’s basic life needs. The right side takes risk in pursuit of outsized upside.
Qian describes this as an anti-fragile setup. Unexpected shocks are less likely to destroy the safety cushion on the left, while the right side still leaves room for large gains if things go well.
He also points to a counterintuitive idea. In a world where asset correlations are rising, investments in the middle of the risk spectrum may not offer enough return to justify their exposure. When tail events hit, those middle-ground assets may still carry meaningful downside.
The article says the barbell idea is not limited to financial portfolios. It can also be applied to time, career choices and other personal resources.
For a 25-year-old, the safety cushion may not be mostly cash
Qian uses the example of a 25-year-old employee at a large technology company to show how the answer changes by life stage.
For that person, the left side of the barbell may already include youth, good health, stable salary income and expected future cash flow. If those conditions are in place, there may be less need to hold a large amount of cash.
Under that setup, the article says a young person who has learned the right knowledge may choose to put savings into long-duration, more volatile assets such as the Nasdaq, Bitcoin or chip stocks. The same logic can extend beyond markets to education, trying vibe coding, building a self-media side business, or even attempting a career in stand-up comedy.
Qian pushes the right-side idea into everyday life as well. Joining a local interest group on weekends or attending gatherings organized by friends can also count as a right-tail bet, because those experiences may unexpectedly lead to useful people, ideas or information.
In this version of the barbell, the left side comes from time, health, low debt and enough money to cover living costs for a period of time. The right side consists of investments of money or effort that may create future upside.
For middle-aged people, cash on the left side matters more
The same model looks different for a middle-aged person.
The article argues that many middle-aged workers are already past the midpoint of their careers or have entered a mature stage with limited room for promotion. At the same time, younger workers may gradually become capable of replacing them. For many people employed by private companies, losing a job can make it difficult to return to a traditional workplace.
Because of that, Qian says middle-aged people should build up cash savings on the left side early rather than over-allocating to the right side because of the appeal of higher returns. If risk materializes before the safety cushion is large enough, the portfolio may fail when it is needed most.
He gives the left-side cushion two functions:
- helping a person or family get through hard times;
- providing enough “oxygen” for the volatile positions on the right so they are not forced to sell at the worst possible moment.
Why Buffett’s 10% cash rule is not a template for everyone
The article says Buffett’s 10% cash and 90% S&P allocation is itself a form of barbell strategy.
But Qian adds that Buffett can keep the left side so small because the advice was meant for his own family. At Buffett’s level of wealth, 10% in cash and Treasuries would still be enough to support his heirs even if the S&P 500 were cut in half.
For most ordinary middle-aged people, the more relevant question is not whether to copy that ratio. It is whether their own left-side cushion can cover household living expenses in a worst-case scenario, and only then how much remains available for risk investments on the right.
Personal finance is personal
Qian cites a line from The Psychology of Money: the most important part of personal finance is that it is personal. He argues that the same principle applies to the use of the barbell strategy.
People differ in temperament, talent, preferences, values and their ability to handle stress. Those differences shape how large the safety cushion should be and how much risk belongs on the right side.
The article also mentions actress Lucy Liu from Kill Bill. Qian recalls Liu saying in a program that she came from a difficult background and later saved a large amount of money that she called “F*ck You Money” because it bought freedom, independence and the right to say no.
He closes with a simple distinction: money that is spent buys experiences and memories, while money that is not spent buys the freedom to choose and refuse. On that basis, there is no single answer to how much cash a person should keep. The size of the safety cushion has to match real personal circumstances rather than someone else’s allocation ratio.
This article reflects the views of PANews columnist Bill Qian and does not represent the position of PANews. It also does not constitute investment advice.




