
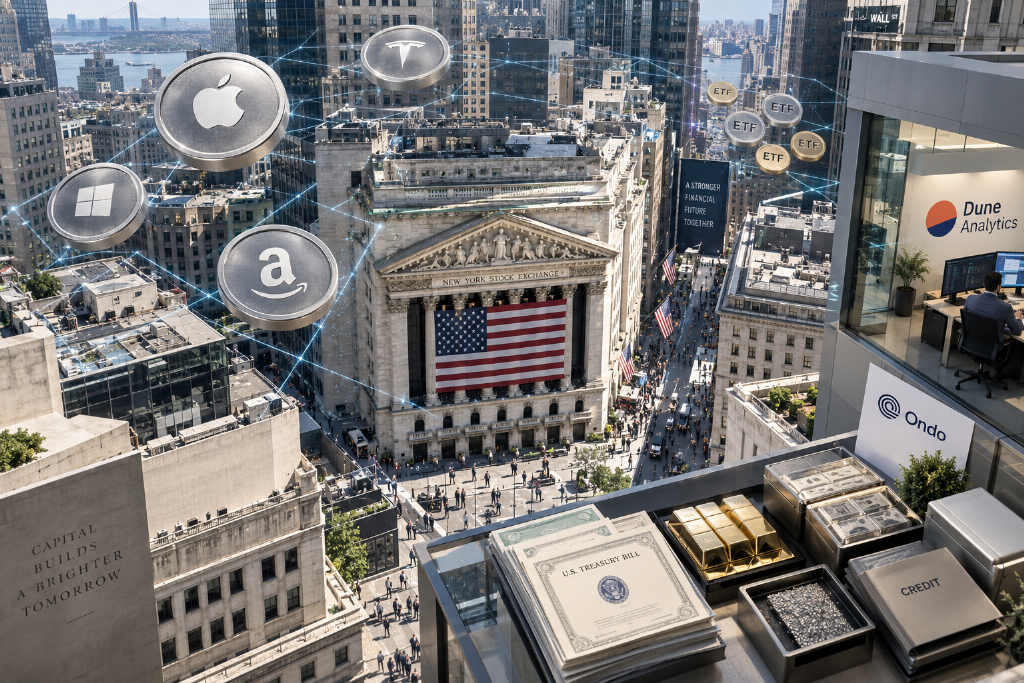
Dune Analytics said in its latest report that the tokenized real-world asset market reached $34.5 billion on Aug. 31, up more than 140% from a year earlier. The report also pointed to a clear split between on-chain and traditional equity investing: investors in tokenized stocks are leaning toward direct exposure to individual companies rather than ETF-based diversification.
Single-name stocks account for 81% of tokenized equity spot supply
The report compared on-chain and off-chain trading patterns across equities, credit, commodities, and cash equivalents. The biggest contrast appeared in equities. Dune data showed that single stocks made up 81% of tokenized equity spot supply, while ETFs accounted for 19%.
That is a sharp break from traditional markets, where index-based products have held a dominant position for years.
Ondo Finance says tokenization gives investors direct choice
Armand Khatri, ecosystem lead at Ondo Finance, said the main advantage of tokenization is that it reduces investor dependence on product menus set by local intermediaries. In traditional finance, the stocks or funds available to retail investors are often shaped by broker offerings and local regulatory limits. On-chain markets, by contrast, let investors choose the company they want exposure to directly.
Khatri said the decision between single-stock exposure and index exposure now sits with the investor. He added that this matters in emerging markets or in countries with tighter regulatory restrictions, where direct access to some large technology companies or crypto-linked firms may not be available, but tokenization can make those assets reachable.
Cash equivalents remain the largest supply segment, while equities lead trading activity
Even with total market value expanding to $34.5 billion over the past year, the supply side is still led by cash-equivalent products. That includes tokenized U.S. Treasuries and assets backing stablecoins, instruments described in the report as lower-risk products that mainly attract institutional capital and more conservative yield-seeking investors.
Equities, however, are the most actively traded part of the market. That points to stronger participation from retail traders and more aggressive capital in tokenized stocks.
Tokenized equities are still a tiny slice of the global stock market
Despite the growth, tokenized stocks remain small relative to the broader global equity market. According to Binance Research data cited by Binance co-CEO Richard Teng on X, the tokenized equity market stood at $4.43 billion as of Sept. 15, after growing 390% in 2026. Even so, it represented only 0.0029% of the $151.9 trillion global listed equity market.
Under its base-case scenario, Binance Research projected that tokenized equities could reach about $349 billion by 2030. Teng said tokenization will change how investors access stock markets, but added that the shift 「won’t happen overnight」.
U.S. regulators and exchanges are moving on tokenized equities
The report said the compliance path for tokenized stocks in the U.S. is being built out. On Sept. 17, the U.S. Securities and Exchange Commission granted temporary exemptive relief allowing limited on-chain trading of tokenized U.S. listed stocks. The move was described as a key step for larger institutional participation.
At the same time, the New York Stock Exchange and Blockchain.com said they plan to list tokenized U.S. stocks and ETFs through a planned NYSE digital trading platform, though the effort still requires regulatory approval.
Structural differences between on-chain and traditional markets remain in focus
Dune’s central observation was not only the rise in market value, but the difference in trading behavior. In traditional finance, passive investing through ETFs and index funds has dominated capital flows over the past decade. The tokenized on-chain market, by comparison, is showing a stronger preference for active stock picking.
The report said several structural factors may be behind that pattern: on-chain investors may be younger and more willing to take risk, infrastructure and liquidity for tokenized ETFs are still developing, and on-chain capital may be more focused on alpha generation than on tracking the broader market.
One question going forward is whether the current 19% ETF share will rise once institutional platforms such as NYSE and Coinbase launch compliant tokenized stock and ETF products. The report said that if tokenized ETFs can connect with the liquidity and brand trust of existing index fund products, the market’s ceiling could be much higher than the current single-stock-driven model.




