
Foresight published an article by Stephen arguing that low usage of fixed-rate lending products does not necessarily point to weak borrower demand. The problem, he wrote, is that current products often fail to solve the mismatch between a loan’s term and the borrower’s real financing horizon.

According to the article, a fixed rate locks in the financing price written into the contract, while prepayment terms determine whether that certainty can extend to a shorter borrowing period. If a loan can only be repaid at par or exited at market price, the borrower cannot automatically settle under another method through the contract itself — paying the original rate only for the time the funds were actually used and then closing the loan.
Borrowing demand and term-locking can move in opposite directions
The article says borrowers funding LP positions, carry trades, or short-lived market opportunities may face profit windows that are far shorter than the maturity of the loan. Another mismatch appears when the rate environment changes. A borrower may lock in funding when rates are high, then see cheaper capital become available during the life of the loan, but still have to bear the cost of exiting the original financing first.
That creates what the article describes as a counterintuitive demand structure for fixed-rate financing. When leverage demand is strongest, rates are often highest as well, making it least attractive to lock funding for the full term. When it does make sense to lock a rate, borrowing demand is often weaker. In the article’s framing, the product is most attractive when demand is at its lowest.
Under that structure, the economic consequences of maturity mismatch still sit with the borrower. The term may be too long for the strategy, or too long for the rate environment.
The cost of early exit depends on how repayment works
Stephen breaks the early-exit problem down by repayment method.
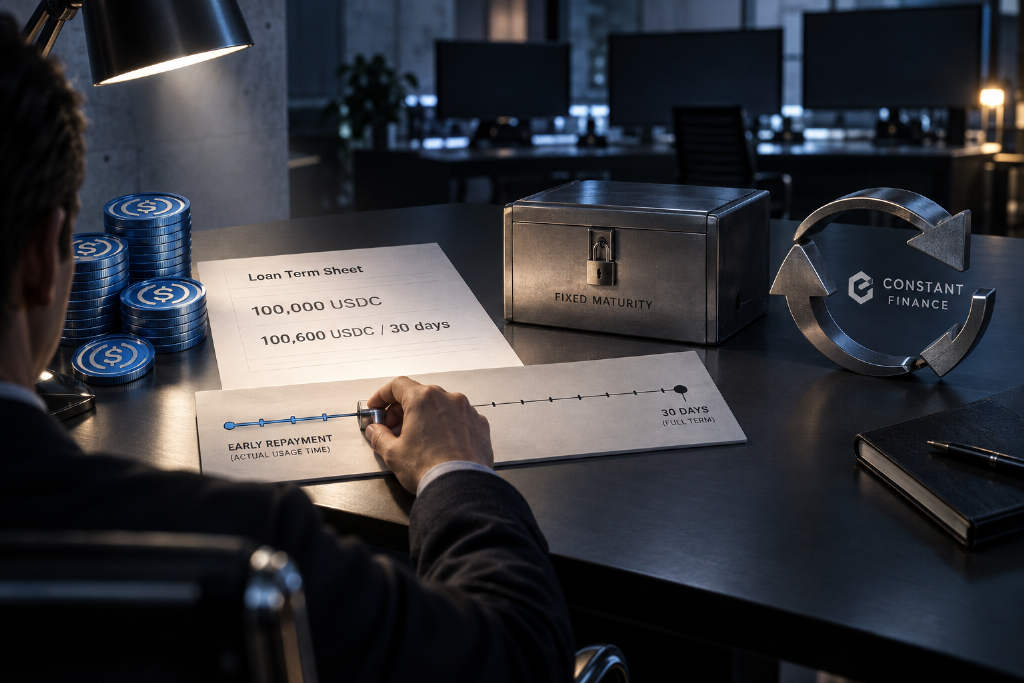
With direct repayment at par, the amount due does not automatically fall just because the actual borrowing period is shorter. The article gives an example in which a borrower receives 100,000 USDC and must repay 100,600 USDC after 30 days. Ignoring fees and slippage, the financing cost is 600 USDC. If the strategy ends on day 7, direct repayment still requires the full 100,600 USDC. Under the same simple-interest assumption, interest for seven days would be only 140 USDC, meaning the remaining 460 USDC is effectively the cost of 23 unused days of financing.
Another route is to buy back the relevant units in the market to offset the debt. The article says a market repurchase can reduce that cost and may even end up cheaper than paying the original rate only for the actual borrowing period. But the outcome depends on price and liquidity at the time of exit, so the borrower cannot know at origination what quote will be available later.
All else equal, a drop in market yields raises the value of the remaining fixed-rate claim and makes the buyback more expensive, while higher yields can produce the opposite result. In other words, a borrower may want to refinance at a lower rate just as the cost of ending the existing financing rises. The contract rate has not changed. The exit cost has.
More pools do not automatically mean aggregated liquidity
The article argues that if markets are segmented by loan asset, acceptable collateral, risk parameters, and maturity, then time itself becomes a boundary between markets. Letting one market accept multiple collateral assets can reduce some fragmentation.
Standardized maturities can concentrate trading activity, but when a borrower’s needs fall outside those dates, the borrower still has to absorb the term difference. Adding more maturities expands the menu, but it also increases the number of separate claims, each of which needs pricing and executable liquidity.
The article says multi-market quoting can ease part of that burden. A shared funding budget allows the same capital base to support multiple quotes without being pre-allocated to each market. Funding can be supplied only at execution, improving capital efficiency. Callback mechanisms can also support atomic rollovers across different maturities, though a rollover still requires executable financing terms on the other side.
These mechanisms are often described as aggregation. But the article argues that every added market, maturity, or collateral set splits the same funding supply and order flow into smaller pools, then reconnects them at the quoting layer.
In Stephen’s view, aggregation should be judged by how much existing liquidity a single borrowing request can actually reach. If a market can only match counterparties with the same asset, the same amount, and the same maturity, then it remains structurally fragmented no matter how many venues are quoting into it.
The article repeats that point directly: if a market can only match against a counterparty with “the same asset, the same amount, and the same maturity,” then it is still fragmented in structural terms, regardless of how many different venues provide quotes to that market.

That boundary exists because the claim itself carries a maturity. If maturity no longer had to match exactly, and loans of any tenor could serve a shorter-term financing need, then the same pool of capital could reach demand that previously could not be matched, without first slicing liquidity by expiry date.
On that basis, the article says liquidity aggregation can lower the cost of serving multiple markets, but it cannot solve the borrower’s maturity mismatch. Making more existing liquidity matchable is a different problem from adding more quoting venues.
A measurable cost ceiling can make some demand financeable
Under floating rates, the article says, funding cost is essentially a random variable. For strategies with bounded returns — carry, basis trades, market making, or financing against a known cash flow — it is hard to underwrite a trade in advance when financing cost has no clear ceiling. If the strategy’s margin is narrow, the rational outcome may be not to borrow at all.
Without a prepayment right that accrues interest only for actual borrowing time, a fixed rate gives the borrower only a known full-term cost. The borrower still cannot know in advance whether the strategy spread will cover the real cost of ending the financing early. Low activity in fixed-rate markets, the article argues, may therefore reflect product terms that exclude part of the demand rather than an absence of demand.
A clear prepayment right lets the borrower settle interest under pre-agreed rules based on actual borrowing time, while the loan still keeps a fixed rate and a defined maturity. That puts a ceiling on interest cost: at most, the borrower pays the fixed rate for the time the funds were actually used. If cheaper financing appears during that period, the cost could fall. With that ceiling in place, strategies with bounded returns can be modeled in advance, and borrowers can decide before entering a position whether the financing fits.
Constant Finance is testing that structure
The article says Constant Finance is already live on testnet. Its lending design centers on fixed-term loans, prepayment based on actual borrowing time, and an embedded refinancing mechanism, with the goal of making the interest calculation clear before the borrower enters a position.
Whether replacement financing is available at that point still depends on the funds available then and on the financing terms the borrower is willing to accept, the article adds.
The key comparison is total financing cost over actual usage
The article also says this flexibility is not free.
Prepayment means lenders give up future interest income and take on reinvestment risk, especially when market rates have already fallen. Lenders therefore need to price that prepayment right. In Constant Finance, the article says, that shows up as a higher quoted rate.
Whether the flexibility is worth it should ultimately be judged by the borrower’s total financing cost over the period the funds are actually used, not by the headline quoted rate alone.
That makes the meaningful competitive benchmark the full financing outcome: origination, actual usage period, and final settlement.
The article closes by saying fixed rates do remove one important uncertainty in financing cost. But under the repayment structures discussed here, borrowers still bear the consequences of maturity mismatch: either paying the full face-value amount or exiting at market price.
Infrastructure can become more sophisticated, the article says, but that does not remove the constraint. If predictable contractual obligations come at the cost of financing terms that do not match actual borrowing needs, then for this class of borrower, the lending market remains incomplete.
Disclaimer: Markets carry risk, and investment requires caution. This article does not constitute investment advice. Users should consider whether any opinion, view, or conclusion in the article fits their own circumstances. Any investment decision made on that basis is at their own risk.
