
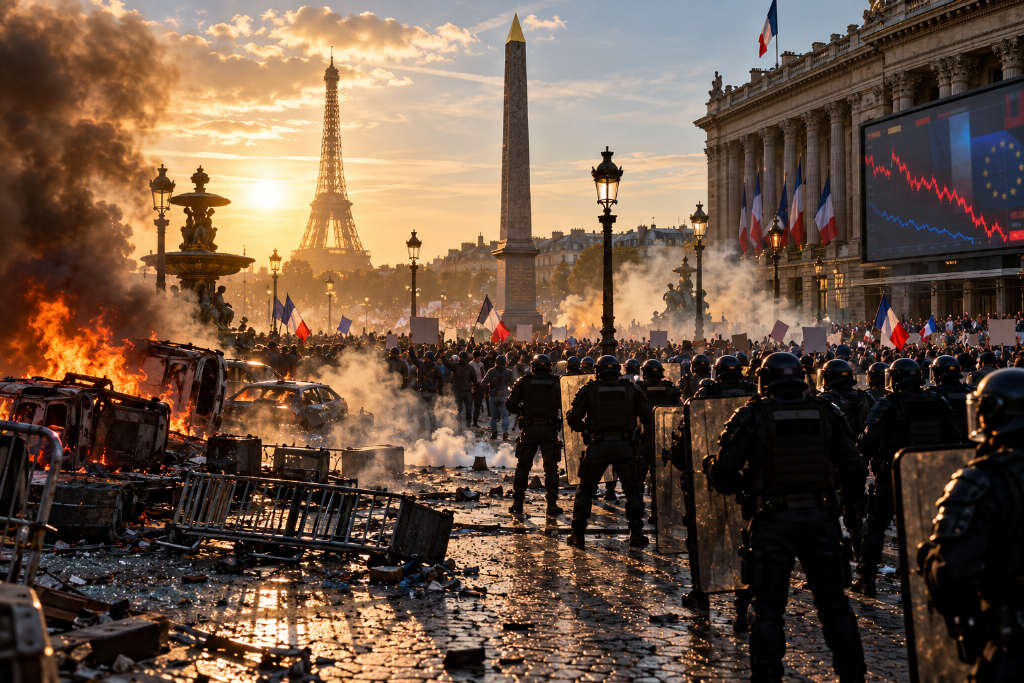
French assets fell under pressure on Oct. 19 after large-scale protests over the weekend deepened concerns about social unrest, political instability and the country’s debt burden. According to CNBC, France’s 10-year government bond yield rose by more than 10 basis points and stayed near levels not seen in decades. The 2-year and 30-year yields were up 6 basis points and 8 basis points, respectively. Paris’s CAC 40 index fell 1.34% in early trading, while the euro lost 0.28% against the U.S. dollar and 0.24% against the British pound.
Hundreds of thousands protested, with more than 2,000 arrests
Hundreds of thousands of people took to the streets over the weekend to protest political paralysis, the cost of living, and the condition of public services such as schools and healthcare. Gatherings in Paris, Lyon and Marseille turned into scenes of burning buildings and cars, along with clashes with police. More than 2,000 people were arrested.
Mike Bell, market strategist at RBC BlueBay Asset Management, told CNBC: 「It looks like either a bond market revolt, a people’s revolt, or both.」 He said France needs to repair its public finances and raise the retirement age. 「If the conversation has not even started and the streets already look like this, it is hard to imagine what happens when they actually try to raise the retirement age.」
OAT-Bund spread reaches highest level since the euro debt crisis
The extra yield France pays over Germany on government debt, known as the OAT-Bund spread, has climbed to its highest level since the eurozone debt crisis in the early 2010s. French yields have also moved above those of Italy and Greece. France’s benchmark borrowing cost has reached its highest level since 2002.
The share of French government debt held by foreign investors has risen from about 48% at the start of 2022 to nearly 60% at the start of 2026.
Markets are watching the election and the 2027 budget
CNBC said markets are mainly worried about next year’s presidential election, with far-right leader Marine Le Pen leading in several polls. Another concern is whether the minority government led by Prime Minister Sébastien Lecornu can pass the 2027 budget, which is still under negotiation. Budget talks have already brought down Lecornu’s two predecessors.
France’s deficit is currently about 5% of GDP, above the 3% ceiling set under the European Union’s excessive deficit procedure.
Strategists and rating analysts focus on liquidity and demand
Sharon Bell, senior European equity strategist at Goldman Sachs, said the situation does not yet require emergency intervention from the European Central Bank, and that the ECB does not want to use its Transmission Protection Instrument, or TPI. She added that the central bank would step in if spreads began to disrupt market liquidity.
Ken Egan, senior director of sovereign ratings at KBRA, said last week’s auction showed that underlying demand for French government bonds 「remains fairly solid.」 Emmanuel Moulin, governor of the Banque de France, told CNBC last week that the rise in yields reflects political uncertainty and that the government could still bring the deficit back to 3% by 2029.



