
Goldman Sachs raised its 12-month price target on Robinhood Markets (HOOD) to $145 from $144 and maintained a Buy rating, saying the company’s preliminary September trading data came in stronger than expected.
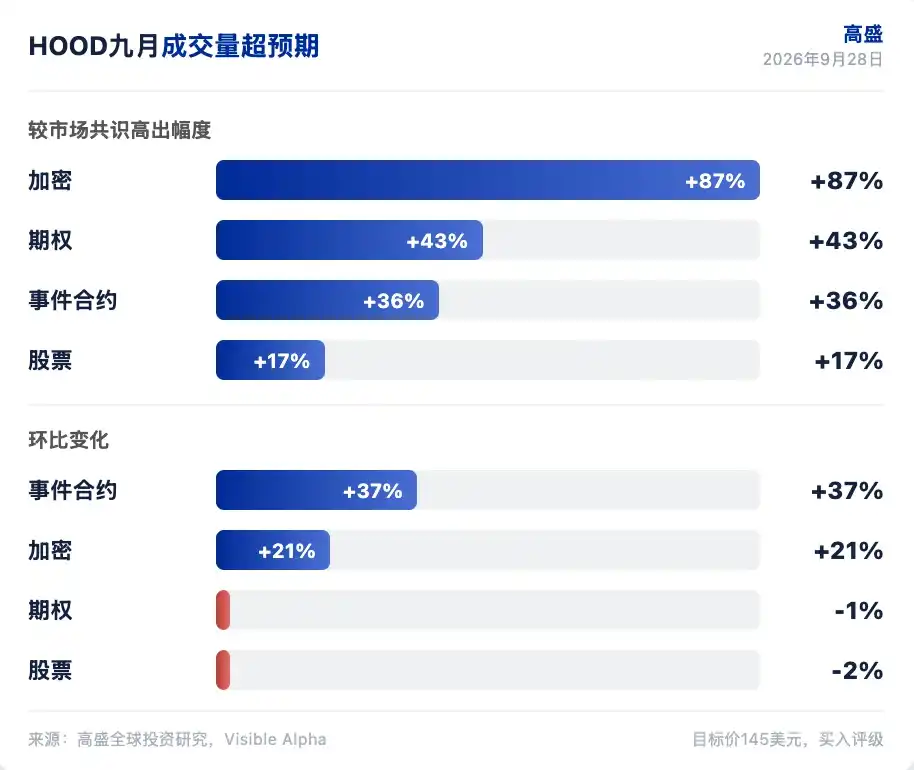
In its preliminary monthly data report dated Sept. 28, 2026, Goldman said Robinhood posted standout gains in crypto and event contracts during September, even as stock and options activity eased slightly from the prior month.
Crypto and event contracts led the upside
According to the report, crypto trading volume rose 21% month over month to $21.9 billion. That was 87% above market consensus and 17% above Goldman’s previous estimate. Event contract volume increased 37% from August, beating consensus by 36% and Goldman’s prior forecast by 6%.
Goldman said those two lines were the biggest upside surprises in the September data. Adjusted HOOD app volume for the month reached $13.55 billion, also above the bank’s earlier expectation.
Stock trading volume fell 2% month over month and options volume slipped 1%, but both still came in ahead of consensus. Stock volume was 17% above market expectations and options volume was 43% above consensus. Against Goldman’s own prior model, stock volume was 1% higher and options volume was in line.
On a year-over-year basis, stock volume increased 38% and options volume rose 32%, indicating retail trading activity remained above the level seen a year earlier.
Goldman revised revenue and earnings estimates
Goldman analyst James Yaro said the preliminary September figures support higher revenue expectations. The bank raised its net revenue forecasts for 2026 through 2028 by 1%, 4%, and 4%, respectively. Its adjusted earnings-per-share estimates changed by -1%, +4%, and +3% over the same period.
Goldman now expects 2026 net revenue of $5,404.8 million, up from $5,359.4 million. Its 2027 forecast increased to $7,104 million from $6,852 million, and its 2028 estimate rose to $8,272.2 million from $7,927.7 million.
Adjusted expenses, excluding stock-based compensation, were raised by 1%, 4%, and 6%, respectively. Adjusted EPS for 2026 was trimmed to $2.51 from $2.53, while the 2027 estimate increased to $3.30 from $3.18 and the 2028 estimate rose to $3.89 from $3.76.
Steeper rate curve added support
Goldman said a steeper interest-rate curve was the second driver behind the higher revenue outlook. After updating its market forward-rate curve, the bank said the implied federal funds rate through the end of 2027 now reflects about 3.5 more rate hikes than in its previous model.
That change, Goldman said, should support Robinhood’s net interest income and contributed to the upward revision in revenue forecasts.
Target price moved only slightly
On valuation, Goldman lowered its Q5 to Q8 price-to-earnings multiple by 1.5 turns to 40x to reflect lower market multiples. The new $145 target price implies roughly 44x 2027 EPS of $3.30.
The increase in the target price was modest. Goldman said Robinhood shares were trading at $116.46, implying 24.5% upside to the new target. The bank added that HOOD trades at a premium to traditional brokers, reflecting the higher-growth profile of its retail trading platform.
Goldman also said the durability of crypto and event contract volumes, changes in the rate curve, and the pace of new product launches will be key variables over the next several quarters. It said the move from $144 to $145 mainly reflects higher earnings estimates offset by a lower valuation multiple.
The ratings, target price, earnings forecasts, and related views cited in this article are drawn from Goldman Sachs Group’s research report dated Sept. 28, 2026. They represent the analyst’s and the institution’s views and do not constitute investment advice.