
IDG Capital has become the leading bidder for the surface mount technology, or SMT, business of Hong Kong-listed semiconductor and electronics manufacturing equipment maker ASMPT, Reuters reported on Oct. 26.
The deal could be valued at more than $1 billion. ASMPT is seeking a $1.5 billion valuation for the business, while market expectations point to a likely transaction range of $1 billion to $1.2 billion. Terms have not been finalized, and the outcome is still uncertain. People familiar with the matter said a deal could be reached in the coming weeks, though negotiations are ongoing.
FountainVest Partners and Triton Partners have also expressed interest and taken part in related discussions. ASMPT, IDG Capital and FountainVest did not immediately respond to Reuters requests for comment. Triton declined to comment.
IDG Capital’s investment footprint and M&A record
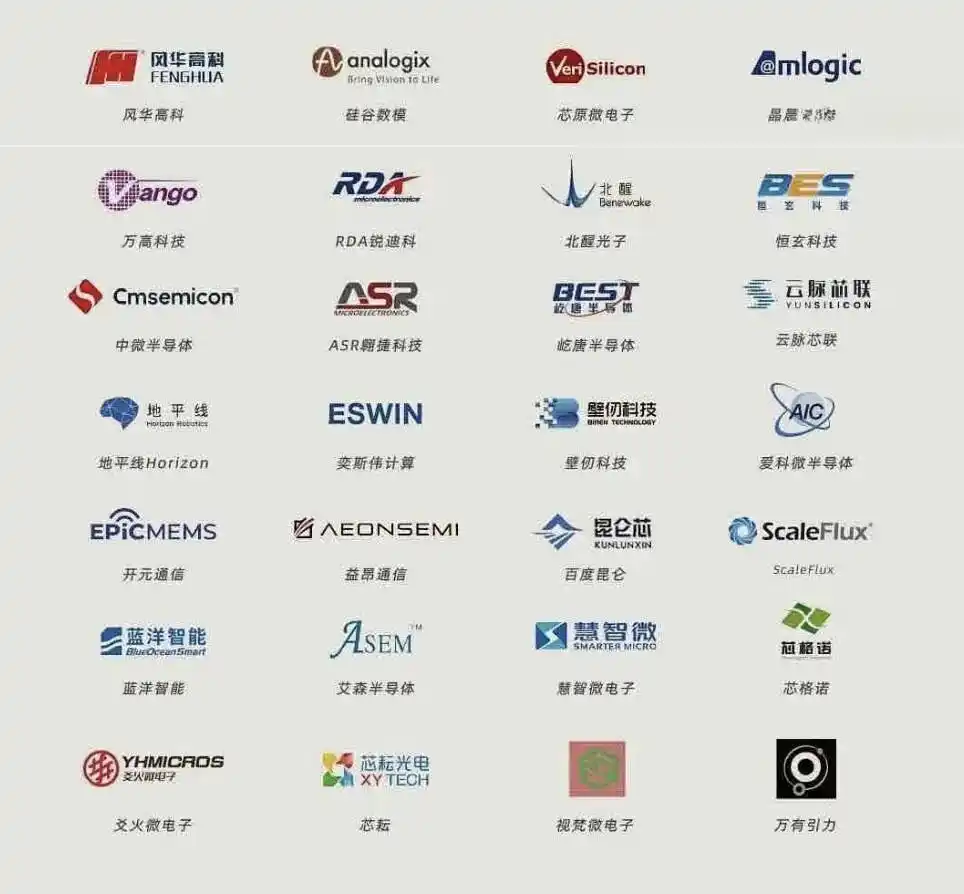
IDG Capital, founded in 1993, has invested in more than 1,700 companies globally, with over 600 exiting through IPOs or mergers and acquisitions. Its semiconductor investments date back years. The firm invested in Fenghua Advanced Technology in 1994 and began building a more systematic semiconductor portfolio in 2003. Companies cited in the original report include Advanced Micro-Fabrication Equipment, Amlogic, VeriSilicon, Bestechnic, ASR Microelectronics, E-Town Semiconductor, Biren Technology, ESWIN, Horizon Robotics and Kunlunxin.
IDG Capital has also completed several acquisitions. In 2017, it partnered with China Oceanwide to acquire International Data Group. In 2025, it acquired Shenzhen Jianyuan Pharmaceutical for 1.6 billion yuan through Sichuan Shuangma. In the autumn of 2025, it bought a majority stake in Danish confectionery brand Lakrids By Bülow. In December 2025, it acquired the China business of French yogurt brand Yoplait for 1.8 billion yuan and became the controlling shareholder.
Why ASMPT is reviewing the SMT business
Public information cited in the report shows that ASMPT was founded in Hong Kong in 1975 and listed on the Hong Kong Stock Exchange in 1989. The company supplies semiconductor packaging and surface mount equipment. Its core operations are split between semiconductor packaging equipment under the SEMI segment and SMT equipment, including DEK printers and SIPLACE placement machines. Its products are used in AI chips, advanced packaging and automotive electronics.
The SMT business provides electronics manufacturers with surface mount equipment, software and related services. It helps customers complete printing, inspection and placement of components on circuit boards. End markets include AI servers, optical transceivers and electric vehicles.
Historical financial data in the report show that SMT was ASMPT’s largest revenue segment in 2023, accounting for about 56.18% of total revenue. In 2024, SMT revenue declined and its share fell to about 49%, while the SEMI advanced packaging business grew against the trend, marking a shift in the company’s business mix. In 2025, SMT’s share dropped again to about 44.7%, while SEMI advanced packaging continued to rise and became the company’s strategic focus.
In January 2026, ASMPT said it had started a strategic review of the SMT business. Options under consideration included a sale, a joint venture, a spin-off, a separate listing, or continued ownership and support for the unit. At the time, the company said the review was intended to support the long-term growth of SMT while allowing the group to focus more closely on expanding its semiconductor solutions and chip packaging operations, with resources directed toward advanced packaging technologies including TCB and Chiplet.
In June 2026, ASMPT also sold its NEXX plating business to Applied Materials.
Latest results and Citi’s view
As demand for servers and related electronics rose with AI infrastructure buildout, ASMPT’s SMT business returned to an upcycle in 2026.
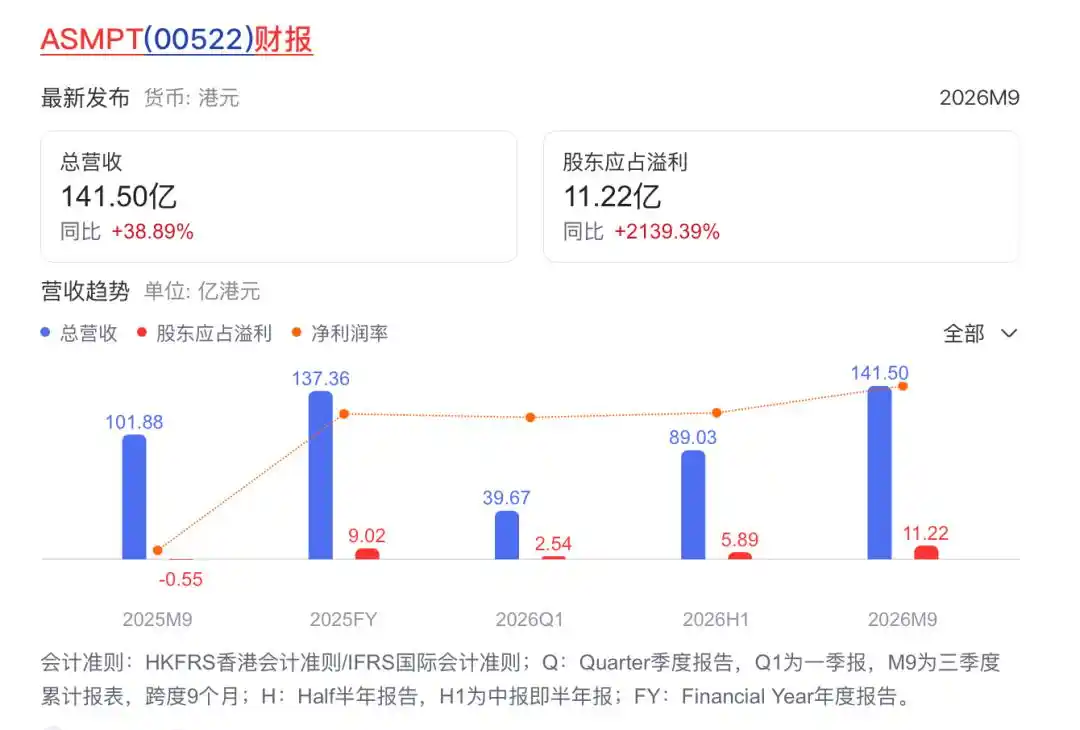
ASMPT’s latest earnings, released on Oct. 28, 2026, showed third-quarter revenue of HK$5.25 billion and profit attributable to shareholders of HK$533 million, compared with a loss a year earlier. Within that, the SEMI advanced packaging business posted revenue of HK$2.93 billion, up 68% year over year, with new orders of HK$4.42 billion. SMT revenue reached HK$2.31 billion, up 29.8%, with new orders of HK$4.43 billion.
Even so, that rebound has not changed ASMPT’s reassessment of its long-term business mix. Compared with SMT, the SEMI segment is growing faster, and its gross margin is above 60%, materially higher than SMT. The original report said this is the underlying reason ASMPT wants to sell the SMT business: SMT is a quality cash-flow asset, but its valuation ceiling and margin profile are lower than those of advanced packaging equipment.
Citi said a divestment of SMT would be neutral to slightly positive for ASMPT, helping unlock valuation and shifting market focus toward execution on advanced packaging orders.
The report cited Reuters and public materials referenced in the original article, which was published by the WeChat account Zhitung IPO and attributed to author Wang Fei.


