
IOSG’s review points to a builder market dominated by one venue
IOSG researcher Mario Chow said 10 teams have registered their own perpetual markets on Hyperliquid, and most of them locked roughly $40M worth of HYPE to do it. One venue accounted for 97.8% of HIP-3 trading volume over the latest 30-day period, even though its monthly volume just fell 44.2%. The report asks a narrower question: what did the other nine teams actually buy with that capital, using on-chain and public API data rather than project announcements.
Every figure in the report was taken from Hyperliquid’s public API, including perpDexs, metaAndAssetCtxs, daily candleSnapshot data for all 519 registered assets, delegatorSummary, userNonFundingLedgerUpdates, and clearinghouseState{dex}. In the report, “30 days” refers to the full UTC days from Aug. 15 to Sept. 13, 2026, “the previous 30 days” means July 16 to Aug. 14, and “7 days” means Sept. 7 to Sept. 13. HYPE was priced at $79.73. Routing figures in section 7 came from Flowscan because builder-code volume cannot be fully aggregated from the public API.
Ten deployers have appeared, and no eleventh has joined
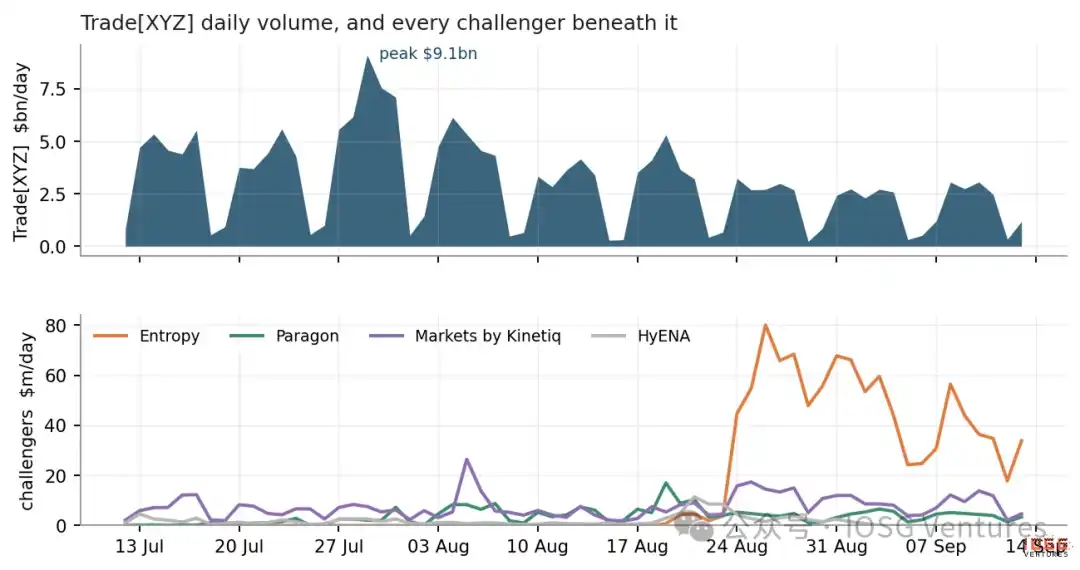
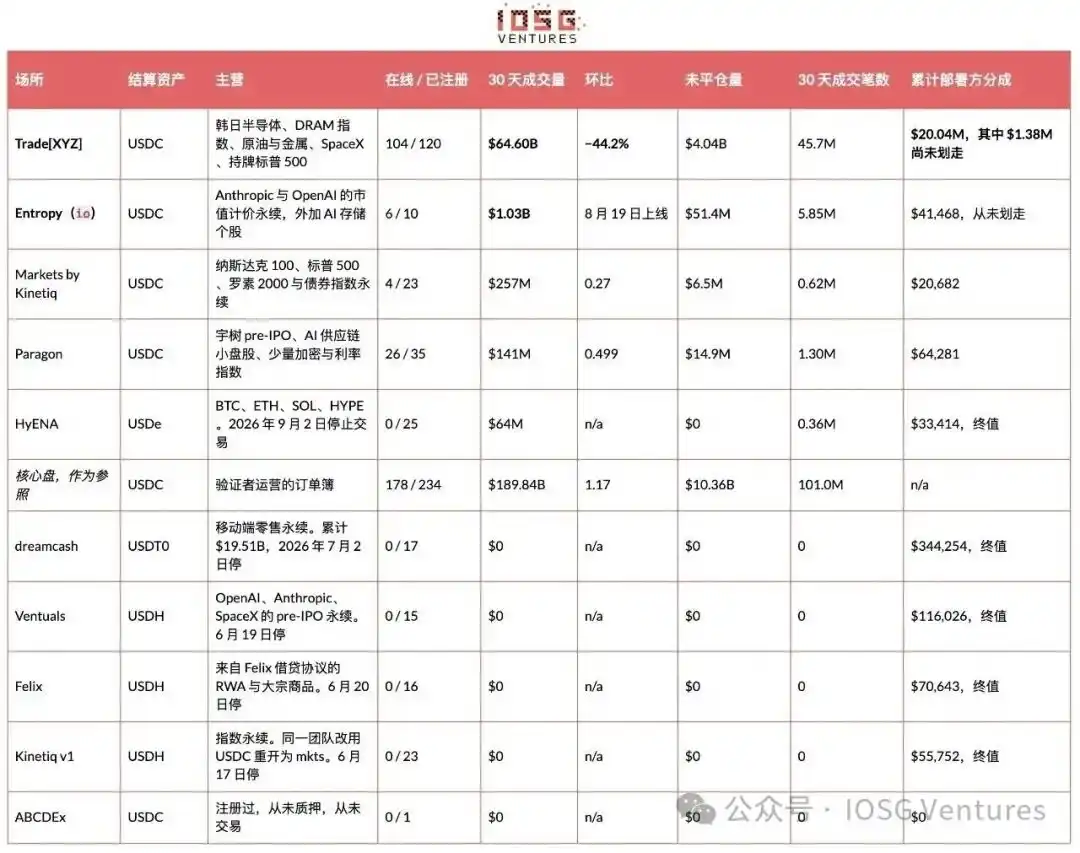
According to IOSG, only 10 teams have ever registered a perpetual DEX on Hyperliquid, and there is still no eleventh entrant. Four are currently trading, five have stopped, and one never opened. Trade[XYZ] remains overwhelmingly dominant, accounting for 97.8% of HIP-3 volume over the latest 30 days and 97.6% over the latest 7 days.
The report summarizes the challengers in blunt terms. Entropy generated $1.03B in volume over 26 days, runs six live markets, and relies on its own oracle setup rather than a broader asset list. It is the only venue that managed to lead on a market where the leader was also quoting. Paragon is described as the only challenger whose order book actually looks like an order book, with 26 live markets and a longer tail of activity. Even after Trade[XYZ] switched on five overlapping instruments in one move, Paragon still posted 49.9% monthly growth. Markets by Kinetiq bought 23 instruments, but 95% of its volume came from two index perps. HyENA has already ended operations: all markets were delisted, open interest fell to zero, and lifetime deployer revenue reached only $33,414.
IOSG noted that “number of trades” was calculated by summing the n field in daily candles over each window. The public API does not allow a count of unique traders.
HIP-3 share dropped from 57.1% to 25.8%, but IOSG says the ratio is easy to misread
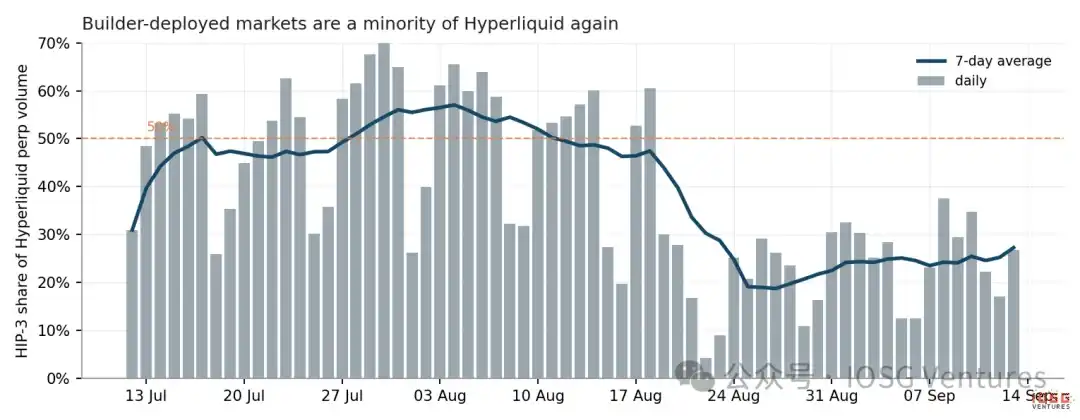
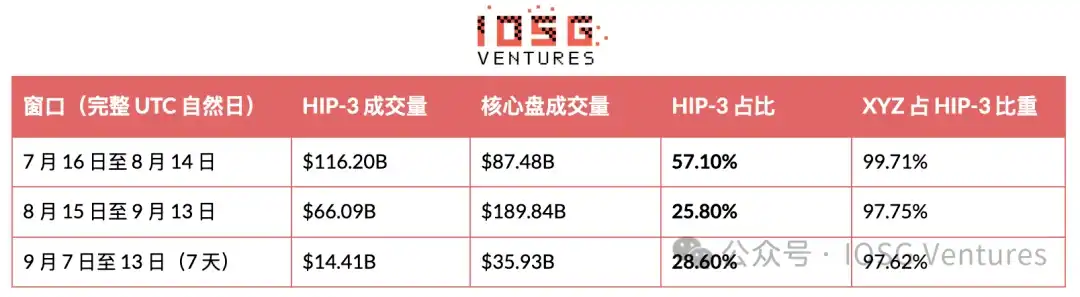
Builder-deployed markets represented 25.8% of total Hyperliquid perpetual volume over the latest 30 days, down from 57.1% in the previous 30-day period. IOSG said the 7-day average moved above 50% in mid-July, approached 57% in early August, then fell below 30% and never recovered after Aug. 20. On Aug. 18, one builder venue briefly traded more than Hyperliquid’s entire validator-run perp set. That did not happen again.
The report argues that this share mostly reflects what happens in the denominator. The numerator is essentially a stock-focused order book, while the denominator is a crypto-heavy book. The more volatile leg has been the crypto side. A 57% reading came during a quiet crypto period. A 26% reading came when the same stock-focused book ran into a stronger crypto tape. Over the same span, core Hyperliquid perp volume rose 117%. In the most recent 7-day window, HIP-3 share even recovered to 28.6%, although Trade[XYZ] itself kept shrinking.
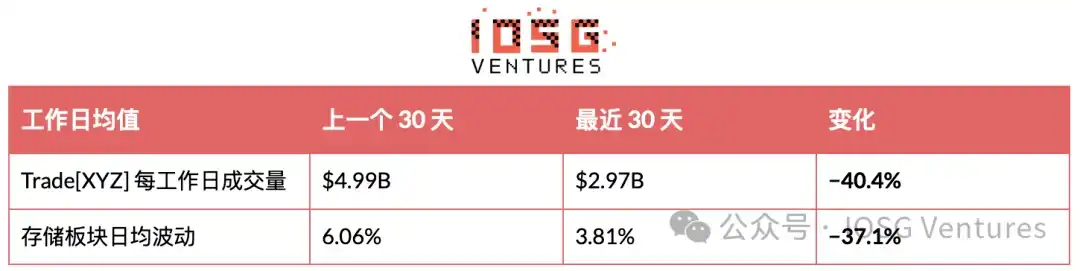
IOSG says the figure that matters is absolute volume, and that is getting worse. Trade[XYZ] posted $64.60B in volume over 30 days, down 44.2% from the previous 30-day period. Its 7-day average volume fell from an early-August peak of $5.36B per day to $2.01B per day. Its own book drew down 62%. Its largest single market, SK Hynix, dropped to $8.50B. The report says both legs of the decline are real, but most of the HIP-3 side cannot be explained by competition alone.
IOSG says the main driver was a quieter storage complex, not just share loss
The easiest explanation for a 44% drop is that the leader is losing. IOSG says the data do not support that reading. If competition were the main cause, the underlying names should still be trading as usual, with Trade[XYZ] simply capturing a smaller portion. Instead, the names themselves became quieter.
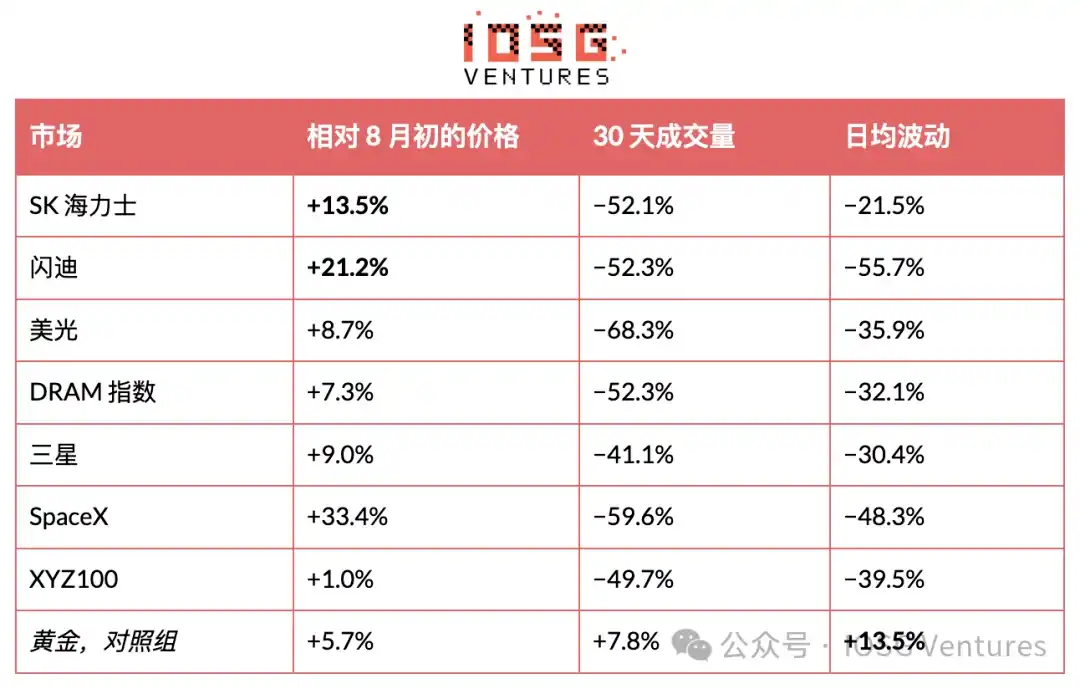
There was no broad selloff, the report says. Using the early-August volume peak as the reference point, every major market in the book is priced higher today. What collapsed was how far those names moved intraday, and venue volume fell almost in step. Because stock exchanges close on weekends while Trade[XYZ] stays open, IOSG used weekday-only data for this part of the analysis. On that basis, the correlation between average daily volatility in the storage complex and Trade[XYZ] daily volume was +0.47 over a 45-trading-day sample. Gold served as a natural control: it was the only large market this month with rising intraday volatility, and its volume rose as well. Silver did not fit the pattern.
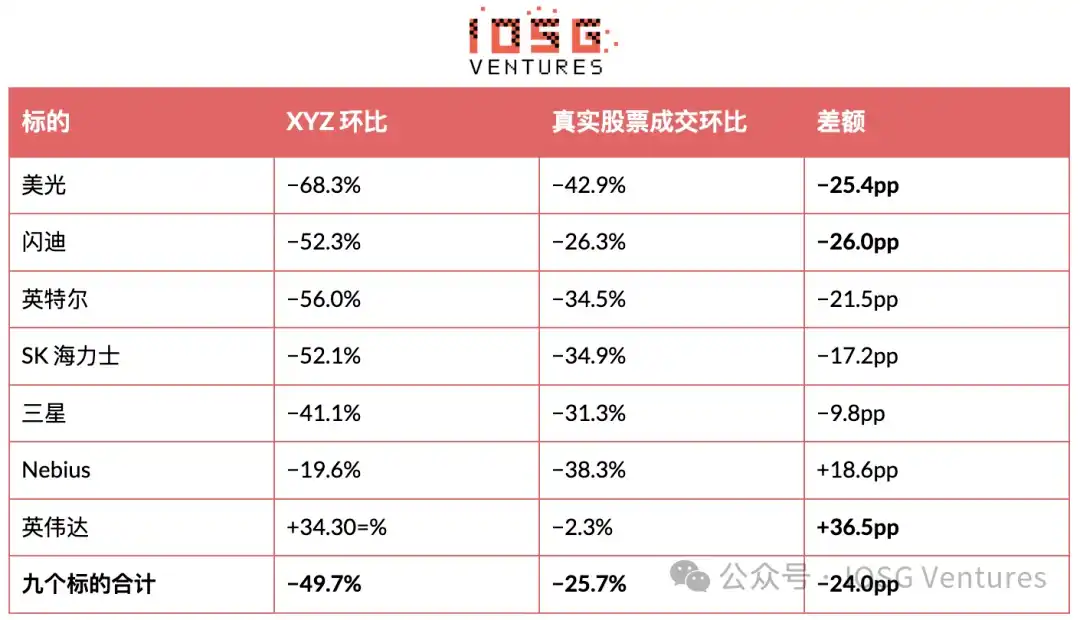
Volatility was only a proxy. IOSG then compared the same nine names against their real stock-market trading volume. That explained only about half the decline. Real trading in the storage and AI group fell 25.7%, which the report treats as one genuine half of the story. Trade[XYZ] volume in those names fell 49.7%, almost twice as much. The extra 24 percentage points did not come from the sector itself.
The biggest gaps appeared in the core names: SanDisk at -26.0 percentage points, Micron at -25.4 points, Intel at -21.5 points, and SK Hynix at -17.2 points. By contrast, Trade[XYZ] outperformed real-market activity in Nvidia by +36.5 points and in Nebius by +18.6 points, though both were smaller books.
Competition does not close the gap, IOSG says. Entropy traded $523M of SanDisk over 30 days, while Trade[XYZ] lost $6.14B of SanDisk volume on its own book. That means the challenger could have absorbed at most about 8% of the missing amount. The rest looks more like a capital rotation. Over the same period, core Hyperliquid perp volume rose 117% while HIP-3 volume fell. Add the two together, and total volume still increased 26%. IOSG’s conclusion is simple: the money did not leave Hyperliquid. It moved from stock-linked books back into crypto books.
The report adds a scale anchor. During the same 30-day period, those nine names traded $2,004.7B on their native exchanges. Trade[XYZ] did $23.5B on them, equal to 1.2%. Its full 104-market book, at $64.60B, was still only 3.2% of the real-market turnover in those nine names. Penetration was highest in SK Hynix at 9.1% and lowest in Broadcom at 0.1%. IOSG says the curve itself explains the business: assets that crypto-native traders cannot easily access elsewhere show higher penetration, while large U.S. stocks that anyone can buy show lower penetration.
The report therefore splits the decline into two parts. About half was sector beta. The other half was venue-specific. IOSG adds that the fee calculations in section 6 use actual traded volume only, so they are not affected by where the volume came from. Still, separating the two matters. The sector half may return. The venue’s own half may not.
Settlement asset remains the dividing line between survival and shutdown
IOSG says six venues have already stopped trading, and the variable that separates them is not asset selection, team quality, or even historical volume. It is the stablecoin used for settlement.
The mechanism is straightforward. Traders have to swap into a specific stablecoin before they can place a first trade, and many do not want the extra step. Felix is the clearest example. Whatever fee advantage once supported USDH was erased once Growth Mode went live. After that, the settlement asset only added friction.
Kinetiq acted as a control case. It was the only operator that survived after shutting down its original venue, because it scrapped the USDH-denominated venue and relaunched the same index products on USDC. Historical volume did not predict anything. dreamcash once did $19.51B, more than the whole June cohort combined, and still shut down. Entropy entered in August with more capital than any previous newcomer and showed no hesitation in choosing USDC.
IOSG also says it is easy, but wrong, to read USDC’s sweep as a fee preference granted by the protocol. Hyperliquid’s own documentation says the opposite. Under Aligned Quote Assets v2, enabled for USDC in late August, Coinbase is the treasury deployer and Circle is the technical deployer. Roughly 90% of the cost-adjusted reserve yield on USDC is directed to the protocol and flows into the Assistance Fund. Interest accrues in 30-day periods and pays on day eight after each period ends, so the first payment will not arrive until early October. As of now, nothing has been paid.
AQAv2 explicitly does not favor HIP-3 with fee or volume-accounting advantages. Other quote assets remain supported for HIP-3 perps. Any fee benefits belonged to AQAv1, which gave eligible collateral assets lower taker fees, higher maker rebates, and better volume credit. USDC is not part of AQAv1 and cannot fit structurally because that version requires a stablecoin to be exclusive to Hyperliquid. The real privileges under AQAv2 point to event contracts and validator-operated perps in later upgrades, not to the market measured in this report.
IOSG’s read is that settlement converged on USDC because of liquidity and a company-level event, not because of fee design. USDH was shut down on July 17, 2026, and holders redeemed 1:1 into USDC. Coinbase acquired the brand assets and became USDC’s treasury deployer. On Hyperliquid today, stablecoin supply is 98.3% USDC, 1.2% USDT, with residual feUSD, USDe, and USDH each at roughly one-thousandth. A venue using a different settlement asset is not giving traders a worse fee schedule. It is asking them to leave the only deep pool.
The report also sketches an estimate for AQAv2 because Hyperliquid has not disclosed official figures. With $6.77bn of USDC on Hyperliquid, SOFR at about 3.6%, and a 90% protocol share, IOSG says the annualized line points to roughly $200M. Third-party estimates based on a $5bn base fall in a $135M to $160M range. The unknown is the cost adjustment inside the AQA rate, which depends on a validator-reported oracle that is not public. Every figure here is an estimate, not an observation.
HyENA and Ventuals show how mechanism design can decide the outcome
HyENA provides a second mechanism in IOSG’s framework. Because it listed crypto assets, it was excluded from Growth Mode. On the same instruments, it quoted around 5 bp while the core venue beneath it quoted around 3 bp, and its execution quality was worse. HyENA spent about $0.88M on asset slots and earned only $33,414 over its entire lifetime.
Shutdown does not necessarily mean exit. HyENA has delisted all 25 markets and open interest is zero, but its stake remains 508,915 HYPE, worth about $40.6M at $79.73. Twelve days later, it still had not begun withdrawing. Felix and dreamcash fully recovered their stake and now read zero. Ventuals is down to 7,967. IOSG says a venue that delists every market yet leaves $40M staked is either unwinding slowly or using that deployer slot for something else.
Ventuals gets a separate section because IOSG sees the next generation of products as a response to its failure. Liquidity was only the symptom. The real problem was funding-rate design. Pre-IPO perps had no convergence anchor, and annualized funding briefly ran toward about 8,700%, meaning longs would be liquidated no matter whether the mark price was right. Entropy capped annualized funding near 10% and settled against the TWAP of its own mark price instead of chasing an outside reference. IOSG says its contract design reads like a repair list for the specific reasons Ventuals failed. For any pre-IPO market, the report says to look at funding and settlement first, then the asset list.
Trade[XYZ] is not really running a U.S. mega-cap stock venue
In Trade[XYZ]’s 30-day mix, the top 10 markets accounted for 66.7%. Even the tail beyond the top six still represented $32.4B on its own. Nvidia was only 3.5%. Apple, Tesla, Alphabet, and Microsoft together made up 3.3%, just a quarter of SK Hynix alone.
IOSG says this is why the standard tokenized-U.S.-equity story misses the real business. Trade[XYZ] is actually running a 24/7 venue for storage and AI capex trades, with oil, metals, and index products layered on top: Korean and Japanese semiconductors, a synthetic DRAM index, SpaceX, its own XYZ100 basket, and a licensed S&P 500 product. Its edge sits in assets that crypto-native traders cannot easily touch elsewhere at 3 a.m. That is also the ground Entropy chose to attack, through SanDisk and Nebius, not through Apple.
IOSG says the obvious answer for why Trade[XYZ] does not list OpenAI is wrong. It is not avoiding private companies. Pre-IPO is actually one of the areas where it performs relatively well. SpaceX alone traded $2.80B in 30 days, equal to 4.3% of the book and ranking ninth. Below it were Unitree at $511M, CXMT at $317M, Zhipu at $156M, MiniMax at $92M, and SHEIN at $27M, with YMTC already registered and pending.
Those names share two features: they have observable secondary-market prices and known share counts. SpaceX runs regular tender offers that produce explicit per-share prices. The Chinese names have active gray-market pre-IPO trading domestically, and share counts can be inferred from corporate records and fundraising rounds. That lets Trade[XYZ] quote them on a per-share basis.
OpenAI and Anthropic do not fit that template. Their secondary trading often happens through SPVs, where what changes hands is a claim on a fund interest and the headline number is a negotiated enterprise valuation, not a clean per-share price. Quoting a per-share price would mean inventing the denominator. IOSG says the bottleneck is quotation convention, not willingness. Entropy’s solution is to abandon per-share pricing and quote the company itself, with one contract equal to $1bn of market value. At the current midpoint, that implies Anthropic near $2.17tn and OpenAI near $1.53tn.
That still is not a moat, the report argues. If the leader wants to add a market-cap-based instrument, it can do so for roughly another $39,900. Trade[XYZ]’s own roadmap also points elsewhere. It already holds 16 registered but inactive instruments, including uranium, aluminum, the U.S. dollar index, VIX, corn, wheat, TTF, KRW, India’s Nifty, Brazil’s Ibovespa, Ibiden, KSTR, plus YMTC and H100. IOSG says that is a macro-and-commodities queue, not a frontier AI lab queue.
One structural detail also stands out. Trade[XYZ] does not set an oracleUpdater, meaning it does not push mark prices with its own deployer key. Entropy and Felix both point to the same third-party updater at 0x94757f8d… Entropy has publicly said RedStone supplies price data for its Anthropic market. IOSG says that explains why two unrelated venues share an updater address, though the address is unlabeled on-chain. The report adds that a self-built oracle is fine for assets with a reference price. Once the mark itself has to be constructed, the nature of the business changes, and that is exactly where Entropy chose to operate.
Entropy won one week on Nebius, then gave it back
There are now nine instruments live on two HIP-3 venues at the same time. The market is no longer split into clean, non-overlapping books. Any name worth listing twice already tends to overlap.
Trade[XYZ] had registered five of Paragon’s core names without turning them on, then activated all five in a single day on Aug. 18. It leads all five now. Filling that gap cost roughly three days of fees and took one afternoon. IOSG says on-chain data cannot tell whether this was a deterrent move or simply a product queue that happened to complete that day.
The outcome is clearer than the intent. Four weeks later, Paragon still held roughly 20% to 25% in four of those five names, and its overall monthly volume still rose 49.9%. Unitree illustrates the point. Trade[XYZ]’s Unitree book is about 11 times larger than Paragon’s. Paragon accounts for only 8.2% of that pair, yet Paragon’s own Unitree volume nearly doubled over the same period. IOSG says the leader did not take volume away from the challenger. It expanded the market around the challenger. Entering a market and owning a market are different things.
Entropy staged the sharper test. For one week, its Nebius volume exceeded Trade[XYZ]’s, something no HIP-3 challenger had done before. The very next week, the leader’s Nebius book rose 61% while Entropy fell 63%, pushing the challenger back to about one-fifth of that pair’s volume. SanDisk tells a quieter version of the same story: Entropy’s share hovered around 13% in recent weeks and came to 8.5% over the full 30 days.
IOSG’s reading is restrained. Entropy proved it could enter a market where the leader was actively quoting. It did not prove it could hold the position. Its total volume has already fallen for three straight weeks, from $417M to $254M.
The counter-signal came from inventory. While weekly volume dropped 39% from the peak, Entropy’s open interest rose 37% to $51.4M. Anthropic alone accounted for $29.9M. Wash volume nets out and does not leave inventory behind, the report says. So falling volume share alongside rising open interest points more to real positioning than empty churn. Those two facts move in opposite directions. IOSG says the tension between them is what should be watched, not either number by itself.
The report still discounts part of the flow. Entropy has no token and has not confirmed any airdrop, but its backend already exposes a pointsMultiplier parameter and its own leaderboard says “coming soon.” That means some activity may be farming expectations rather than using the product, and outsiders cannot separate the two. Scale also matters. Entropy did roughly $1.0B in a month. Trade[XYZ] did $64.6B. That puts Entropy at 1.6% of the leader. IOSG says it won a battle, not the category.
Its inactive registrations hint at where it wants to go next: EWY, SBE, TCNT, and a DRAM index. The DRAM index is Trade[XYZ]’s fourth-largest product, and EWY points straight at Korea. IOSG says the next clash appears more likely to hit the leader’s core terrain than to chase another uncontested pre-IPO listing.
The report also sets out two counting rules. First, only live books are counted. HIP-3 deployers often register assets long before activation. These return an oracle markPx, but midPx is null, isDelisted is true, open interest is zero, and there is no candle history. Trade[XYZ] has 16 such names, mkts has 19, Paragon has 9, and Entropy has 4. HyENA’s 25 are different: they were activated and later shut down. Second, a symbol string is not the same thing as an asset. IOSG gives the example para:STX, which refers to Seagate with a midpoint near 799, while core STX is Stacks at about 0.27. Matching by ticker alone would fabricate a tenth overlapping market that does not really exist.
The economics: fee competition is over, while staking and slots shape the cost base
IOSG says nobody is really competing on price because fees are already at the floor. Two public parameters in metaAndAssetCtxs drive the result: growthMode and deployerFeeScale. The all-in fee is base × (1 + s), where base is the standard perp fee schedule and s is the deployer coefficient. It can range from 0 to 3.00 but is capped at 1.00 in Growth Mode. The deployer receives s / (1 + s), so s = 1.00 means it keeps half. Growth Mode then cuts the all-in number by at least 90%, provided the market does not overlap at all with validator-operated perps. That excludes crypto assets and crypto indexes.
All stock-linked venues independently converged on the same setup: maximum deployer share and Growth Mode turned on. Even Entropy, which arrived with differentiated products and venture backing, did not try to undercut on fees. The only venue outside that template is the one that just stopped trading.
IOSG also explains how to calculate deployer revenue without relying on aggregators. Fee income accumulates in subaccounts tied to fee-recipient addresses. clearinghouseState with a dex field shows balances not yet moved out, and transfers appear in userNonFundingLedgerUpdates as sends where sourceDex equals the venue name. Because transfers are irregular, the measurement has to run between transfer events. On that basis, Trade[XYZ] has accumulated $1,380,592 since its Aug. 27 transfer, against $32.30B in volume, equal to 0.427 bp and about $79,000 per day. Entropy has never transferred out, so the cumulative fee can be read directly: $41,468 on $1.036B of volume, equal to 0.400 bp.
There are two cost lines, and they are very different. Staking is the scarier number, but in principle it comes back. Nobody takes it away if the exit is clean. It is delegated to validators, keeps earning staking rewards, and is returned at exit. The stake is locked for at least 183 days after deployment. It can be slashed by weighted validator vote for malicious market operation, such as pushing bad oracle prices, and it remains slashable during the 7-day unstaking queue. A clean exit therefore takes roughly 190 days at minimum. Felix and dreamcash fully withdrew and now show zero.
Current stake figures are 500,973 HYPE for Entropy, 500,712 for Paragon, 508,915 for HyENA, 588,489 for Kinetiq with one stake covering both km and mkts, and 500,488 for Trade[XYZ] plus another 500,269 at a second address. ABCDEx has only 1,004 HYPE and never staked.
The cost that really does not come back is the asset slot. Every perpetual DEX gets its first three assets free. After that, each new market has to be bought in a 31-hour Dutch auction using HYPE. The opening price is twice the previous clearing price and then decays linearly to a 500 HYPE floor. In the Sept. 14 auction, the market opened at the 500-HYPE floor and also finished there, implying about $39,900 per slot. IOSG says demand for slots has already softened from the prior week’s 582-HYPE clearing price.
The asymmetry is large. Trade[XYZ] needs roughly eight weeks of fees to pay back the bill for all of its listed instruments. Every challenger except Entropy would need more time than HIP-3 itself has existed. Entropy only clears the hurdle because it bought seven slots rather than 30.
Time makes that gap wider, IOSG says. Pausing a market is free and reversible. Once a slot has been paid for, it can be mothballed and reopened later. That is how the inactive queue is built. Reserve slots also accumulate with deployment history under the formula 7 + 0.2 × historical auction deployments, so Trade[XYZ] has about 30 that it can use immediately, while a newcomer has only 7. A venue opening today and planning to launch 20 markets can list 10 at once; the rest have to queue through auctions, one every 31 hours at best. Entropy’s answer was not to play that game. It launched only five markets, then tried to make each one matter.
Staking yield looks better than venue revenue, but IOSG says that is misleading
Every challenger except Entropy has earned more from passive staking on the entry ticket than from running the exchange itself, according to the report. Paragon’s lifetime deployer revenue is $64,281. Its roughly $39.87M stake, at around 2.2% annualized, would generate about $877,000 a year, roughly 14 times as much.
IOSG says that is not a comfort. Those rewards come from newly issued HYPE in future protocol emissions, which makes them inflation rather than operating income. They are effectively a dilution rebate on a forced position, denominated in the same asset operators are already involuntarily long. If HYPE falls 30%, that stake loses $12.0M, more than 10 years of yield. Over the last eight days, HYPE itself has already fallen from $88.37 to $79.73, cutting about $4.3M from each active stake.
The fee pool is not especially large either. Growth Mode pushes observed pricing to around 0.4 bp, with deployers taking half. Trade[XYZ], with 97.8% share and an annualized volume run rate of about $786B, would earn roughly $29M a year in deployer revenue. IOSG says that is less a sign of the leader’s upside than a rough estimate of the whole venue layer’s reward pool at today’s volume and today’s fee floor.
Outside the leader, the venue layer has about $167M of HYPE staked today, while all challengers combined, dead or alive, have earned only $747,000 of deployer revenue over their lifetimes. Set beside a $14M seed round, IOSG says the arithmetic is clear: at current volume and current fee floors, HIP-3 operators cannot be valued on trading fees alone. Any value has to come from something else, whether a token, a frontend, customer ownership, or a product the protocol has not priced yet.
What can still be defended on HIP-3
IOSG says HIP-3 intentionally commoditized most of what a venue might otherwise defend. Staking can be bought. Instruments can be bought. The fee floor is shared. Distribution is shared too, because every HIP-3 market can be reached from the same frontend.
That shifts the screening question. It is no longer “Which assets will you list?” because assets can be purchased. The more useful question is “What do you have that the leader cannot buy for the price of one slot?” IOSG says only one operator on HIP-3 has offered a clear answer so far, and the answer is not an asset list. It is an oracle stack and settlement design.
The report is specific about why Entropy is the exception. The edge is not just in what it lists. The company was founded by researchers and traders from Citadel Securities, Optiver, Millennium, and Polymarket. IOSG says that bench showed up in two places. One was the quote depth visible on day one, which is what made Nebius a real test. The other was the funding-and-settlement design, which reads like a direct response to the way Ventuals died. Entropy also raised a $14M seed round led by Ribbit Capital. Ribbit’s home turf is retail brokerage and fintech distribution, not DeFi. IOSG says that points to an ambition to own customers rather than merely extract protocol incentives. The report also warns not to confuse this company with Entropy Advisors, which is deeply tied to Arbitrum DAO, or with the separate custody startup named Entropy backed by a16z. They are entirely different entities and should not be read as evidence of any relationship with the Hyper Foundation.
Even after all of that, IOSG still sees the field as thin. A shrinking operator controls 97.8% of volume. A ring of challengers has tied up $167M in HYPE and received only $747,000 in cumulative fee income. And the only team that genuinely looks able to quote showed it could take a market for one week, then lost it again.
The easier alternative, IOSG says, is to own the protocol-side share of fees rather than the operator-side share. That line does not come with lockups, slashing risk, or operating burden. But it is not the main body of Hyperliquid’s perp fee base either, and the data already show that HIP-3 clearing 50% share was a quiet-crypto artifact rather than a durable trend.
The routing layer touches only a small share of activity
Builder code is the closest thing HIP-3 has to a distribution business. Frontends can tag orders they originate and earn builder fees without posting collateral. Flowscan counted 819 such codes.
They do not touch much of the market. Routed volume is about $52.6B, roughly 9% of HIP-3’s $587B lifetime volume. Over the latest 30 days, routed volume was about $5.3B against $66.09B of total HIP-3 volume, about 8%. More than 90% of traffic carried no frontend tag at all, which IOSG says is exactly what a maker- and API-dominated market should look like.
The report adds an important counting note. In the routing table, the denominator in the fourth column is the $5.30B routed by builder code over the last 30 days, not the full $66.09B of HIP-3 volume. If the latter were used, the largest single router, CoinDCX, would be only 0.7%. The top 10 names in that table account for 59.7% of routed volume, while Flowscan counts 819 builder codes in total. That leaves the remaining 809 codes to split the other 40%.
IOSG highlights two items. First, Entropy’s $423M of routed volume all occurred in the latest 30 days. Its own venue did $1.03B in the same period, which means roughly 40% of its market flow came through frontends it controls. The retail-brokerage ambition implied by Ribbit’s seed round shows up in the numbers, not just in the narrative, and it is a different business from being a deployer. Second, dreamcash offers an even cleaner lesson. Its venue has been dead since July 2 and now reads zero, yet its builder code still routed $17.3M in the latest 30 days and $3.54B cumulatively. Venue operation and frontend operation can be separated cleanly, and only one of those businesses requires roughly $40M to enter.
The report also warns about a common trap in third-party dashboards. Venue leaderboards often default to cumulative volume, which makes a venue that shut down months ago still look meaningful. dreamcash reads as a 3.3% HIP-3 share in an all-time view while showing $0 in any recent window. Before citing any share figure, IOSG says, check the time window behind it.
For that reason, the frontends worth watching are mostly not deployers. Coinbase announced on Sept. 12 a simplified perp interface inside its wallet, powered by Hyperliquid and covering crypto, tokenized stocks, and prediction markets for users outside the U.S. Kraken’s parent company is separately discussing the integration of Hyperliquid-related perps into a regulated U.S. venue. Neither company will post 500,000 HYPE to do it.
IOSG’s conclusion: hard to be optimistic about one more HIP-3 venue
Put together, the numbers leave IOSG skeptical about the case for another HIP-3 deployer. All HIP-3 volume outside the leader totaled $1.49B over the last 30 days, equivalent to roughly $18.1B annualized. At the observed 0.400 bp fee level, that implies about $725,000 a year in deployer revenue, to be split across four venues. Those same four venues have about $167M of HYPE staked today. The same capital, left in passive staking at 2.2%, would generate about $3.67M a year.
In other words, running those exchanges earns about one-fifth of what passively staking the same capital would earn.
IOSG says this does not look like an undeveloped market. It looks like a market already priced close to zero. The reasons were measurable throughout the report: slots cost about $39,900 each, so asset choice is not defensible; the fee floor is shared, so there is little room to cut price; distribution is shared too, and builder code only touches 9% of flow; settlement assets have converged 6-to-6 on USDC; and AQAv2 explicitly offers no fee tilt to HIP-3, meaning the protocol is not subsidizing this layer.
The ceiling is the harder part. Trade[XYZ], with 97.8% share and every structural advantage, reaches only 1.2% of real-market volume on the nine names it actively quotes, and its relative share is still sliding on the core storage names. For a new entrant, the problem is not simply that the leader is large. It is that the leader is already small against the underlying market, and still getting smaller.
The report leaves one exception. A team could still matter if it controls rights nobody else can buy, an oracle stack nobody else can replicate, or funding and settlement mechanics that can survive in a thin market. Entropy is the only example IOSG says fits that description right now, and even it was pushed back after one week. The report’s broader point is that two independent data sets now say the same thing: an asset list is not the answer.
What could change the view
IOSG lists several conditions that could alter the conclusion.
- Entropy would need to hold one contested market for a month rather than a week, and hold SanDisk share rather than drifting around 13%. The report says the most important signal is rising open interest while traded share falls, because it is more reliable than volume alone.
- Entropy’s DRAM index and Korea-linked names would need to launch. Those go directly after the leader’s core ground rather than another uncontested pre-IPO story, making them a cleaner test than Nebius.
- Token economics would have to make the equity story work. The fee story does not work on its own, and there is no token today.
- The pre-IPO category would need to prove it can persist. Anthropic faded after its first week, and OpenAI has moved from $5.3M on opening day to around $4M. If even one of them stabilizes, the category becomes more than a launch spike.
- The first AQAv2 payment in early October will offer the first observable reading on the size of the protocol’s USDC income line against the current $135M to $200M estimate range.
- The fee floor would need to move. Hyperliquid signaled in early August that later upgrades may allow HIP-3 deployers to raise fees on individual instruments by up to 3x, effectively taking back some of the Growth Mode discount. There is no timetable yet, and section 6 relies on today’s floor.
- Permissioned markets would need to ship. HIP-3* was announced on Sept. 3 as an optional on-chain whitelist that lets deployers restrict which wallets can trade a market, aimed at compliance and institutional access, and it is still only on testnet. IOSG says this is the first mechanism that could make access rights rather than assets scarce.
- A team with exclusive data or licensed index rights, tied to an asset that genuinely has 24/7 crypto-native demand, would also change the picture. The report says that is the only setup that fully breaks the slot-grab logic.
- There would need to be evidence that the leader’s volume cannot survive the end of Growth Mode. Its observed 0.427 bp is about one-tenth of what the same book would charge under standard rates. If the exemption is load-bearing, the leader is less secure than its share implies.
- HyENA unstaking its 508,915 HYPE would confirm whether the venue is truly over rather than dormant.
Limits noted by the report
IOSG closes with several caveats. The “slot-grab” argument rests on measured share changes, but motive remains inference. Five names launched on the same day could also reflect a rollout pipeline that happened to finish together. The Entropy analysis is based on only 26 days of data. Its lead on Nebius and the reversal that followed both come from one week on one mid-sized market and should not be pushed further than that. Team backgrounds and fundraising came from company statements and media coverage rather than on-chain verification. The volatility result in section 2 is a correlation over 45 trading days, not a causal decomposition, and both volume and realized volatility may be driven by the same factor, with cooling AI capex trading cited as the most direct candidate. Trade count is not trader count, and the public API cannot identify unique users. Capital-return figures use HYPE at $79.73 and a 2.2% staking yield, with the latter a protocol parameter rather than a contractual promise and one that can fall as network-wide staking rises.