Individuals in mainland China who have held virtual assets for years often run into the same problem when they start reviewing their tax position: records are scattered across multiple platforms, assets have moved through several wallets, some tokens came from work compensation while others came from trading, and the amount that finally reached a bank account does not always match the profit shown on a platform.
In a long-form article, Foresight said the practical starting point is to sort out how the income was generated, what kind of taxpayer the individual is, and how transactions and costs can be evidenced. Based on publicly verifiable rules as of Oct. 24, 2026, the article focuses on how individuals can prepare documents, build a list of questions, and communicate with tax authorities. Its emphasis is on identifying income, rebuilding cost records, organizing cross-border documentation, and turning complex transaction flows into business facts that tax officials can review.
Tax residency comes first
The article begins with Article 1 of China’s Individual Income Tax Law, which distinguishes resident individuals from non-resident individuals. A person who has a domicile in China, or who does not have a domicile but stays in China for a cumulative 183 days or more in a tax year, is treated as a resident individual. Resident individuals are taxed on both China-source and foreign-source income.
It adds that “domicile” has a specific meaning in tax law and must be assessed with reference to habitual residence formed through household registration, family ties, and economic interests. Nationality, the place where a bank account was opened, or offshore residence status alone will usually not settle the residency analysis. People who work across borders over long periods should keep entry and exit records, employment materials, and residence documents.
For individuals without a domicile in China, the article says foreign-source income rules and related conditions may require separate analysis. In those cases, yearly days of presence, consecutive years, departure records, and the identity of the income payer should be organized before determining the actual obligation. For ordinary mainland residents, the review should start from actual domicile and day-to-day economic and living ties.
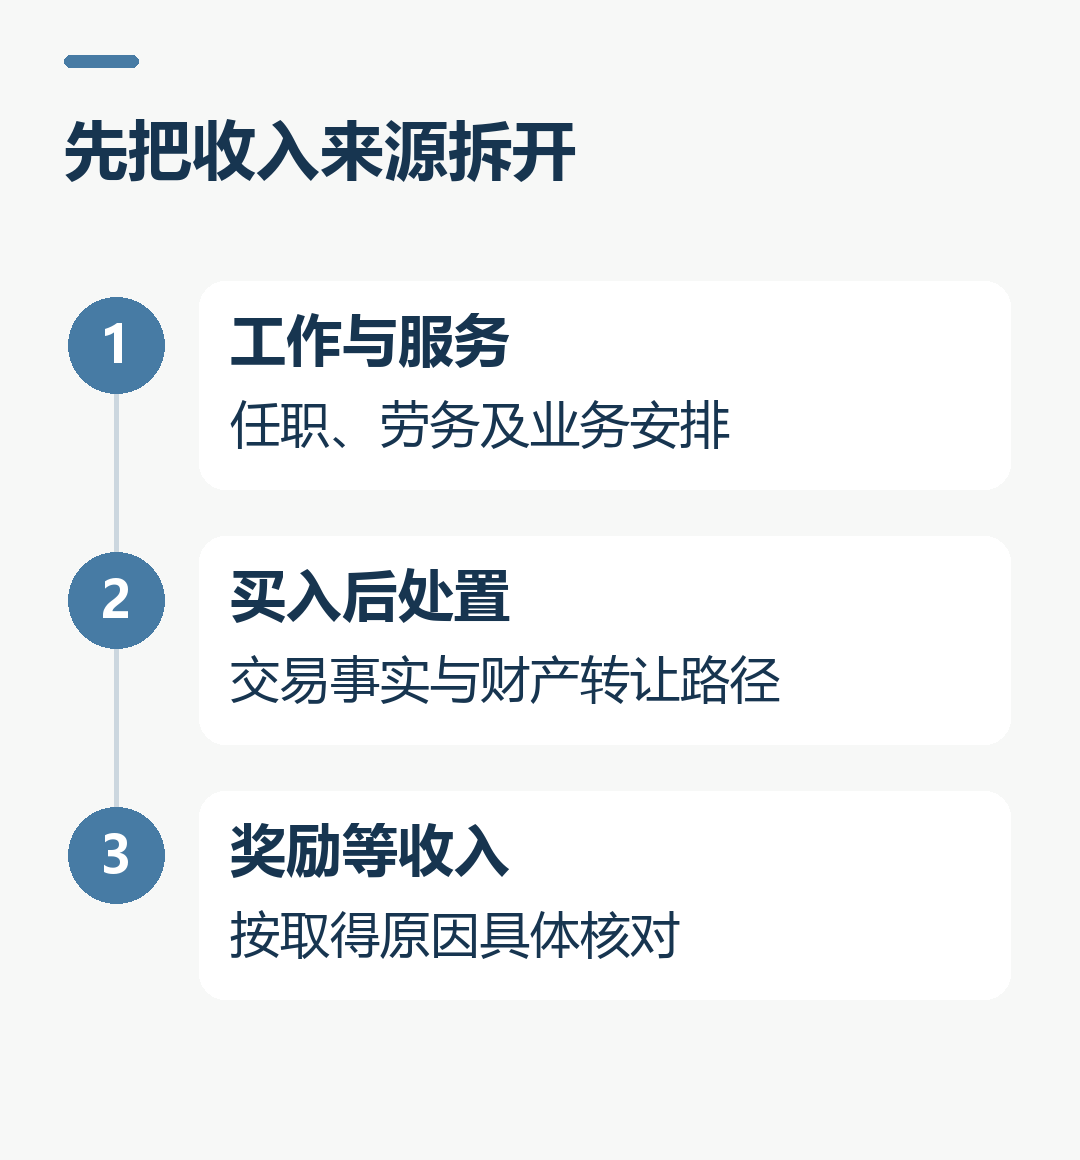
The source of income is a separate question. According to the article, using an offshore platform or placing assets with an offshore wallet service provider does not directly determine where the income is sourced. Wages, labor remuneration, business income, and property transfers each follow their own rules and need to be analyzed with reference to where work was performed, what transaction actually occurred, and what legal rights were involved.
It gives two examples. If a person provides services in mainland China to an offshore company and receives digital assets as compensation, a tax review will first look at the employment or service relationship and the work actually performed. If another person disposes of assets previously purchased for their own account, the focus shifts to the transfer itself and the relevant sourcing rules. Even if both payments land in the same wallet, the legal analysis is not the same.
The article suggests preparing an annual overview of tax status and income, listing residence and work arrangements, income types, payers, platforms, and wallets. That overview can help a tax adviser identify issues quickly and keep the process from getting buried in thousands of line items at the outset.
Income should be separated by legal nature
Citing Article 2 of the Individual Income Tax Law, the article says wages and salaries, labor remuneration, business income, and property transfer income must be analyzed separately. Digital assets are only the form in which income is received or settled. The legal relationship behind the income still controls the classification.
Compensation received in an employment setting should be checked against the labor or appointment relationship, salary terms, and actual payment records. Consideration received for independently provided design, development, consulting, or similar services should be reviewed in light of the nature of the services and the business arrangement. If the income comes from an ongoing organized business with personnel and equipment, business income rules may need to be considered as well.
For assets bought and later sold by the individual, the article says property transfer income is an important route to examine. Article 6 of the Individual Income Tax Law provides that taxable income from a property transfer is the balance after deducting the original value of the property and reasonable expenses from transfer proceeds. Article 3 sets a 20% proportional tax rate for that category. Whether a specific transaction falls into that bucket still depends on the facts and the applicable interpretation.
The article also notes that online discussions often cite Guo Shui Han [2008] No. 818. That reply dealt with a situation in which an individual acquired players’ virtual currency online and then resold it at a markup, and it treated the income as property transfer income. Foresight says the original business context of that document matters, and any analysis involving assets such as Bitcoin should still return to current general rules and the specific facts rather than skipping that step.
Airdrops, staking rewards, lending returns, and incentives distributed by different platforms should also be recorded according to why they were received. Whether the recipient provided services, paid consideration, or assumed a specific obligation when obtaining the asset can affect the income classification. The article recommends sorting these items by facts first, then taking uncertain items to the competent tax authority for confirmation.
It also points out that once an asset is later sold, a second layer of recordkeeping begins. If wages or labor remuneration were measured at the time of receipt, the cost basis used when the asset is later disposed of should connect back to that earlier treatment. Keeping acquisition and disposal records separately but consistently makes it easier to explain that the same economic benefit has already been addressed at a different stage.
Transaction logs need to be rebuilt into real-world trades
The article says exchange exports usually include purchases, sales, swaps, deposits, withdrawals, rewards, fees, and internal transfers. Wallet records may also show contract interactions and several intermediate movements. Grouping those records before any calculation starts can eliminate a large amount of duplication.
For transfers between wallets controlled by the same person, the first task is to match the outgoing and incoming records and prove control over both ends. Exchange deposits and withdrawals should also be linked to on-chain records. Once that is done, a summary table can distinguish a change in asset location from an external transaction, reducing the risk that transfer amounts are counted as income more than once.
Trade records should preserve the transaction time, asset type, quantity, consideration, fees, order number, and settlement method. For crypto-to-crypto swaps, the quantities of both assets and the measurement data used at the time should also be retained, because those details support later analysis of both the disposal leg and the acquisition leg.
If the individual used multiple accounts, the article says it is necessary to identify whether each account belongs to the individual, a family member, or another party. Facts involving collection, payment, or custody on behalf of others should be explained separately, with supporting agreements and fund records. Calculating personal income solely from the gross amount credited to a bank account can pull in money that has nothing to do with the taxpayer’s own income.
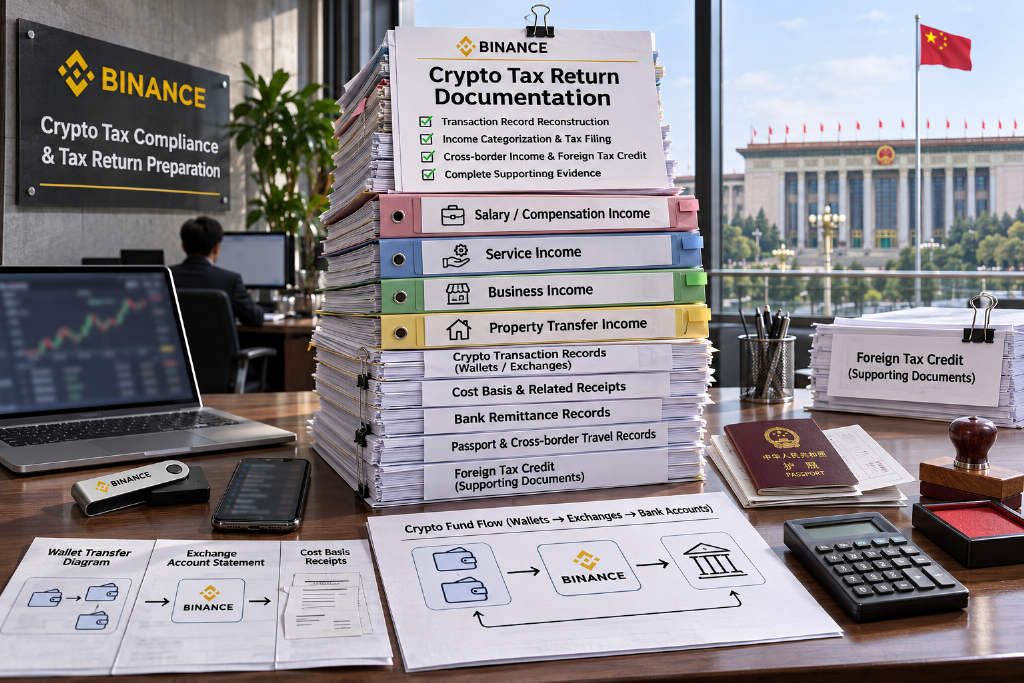
One practical method is to assign an internal reference number to each business event. Bank payment, exchange purchase, wallet transfer, final sale, and bank receipt should be linked in a single chain where possible. Missing steps can be marked with an explanation, and any supplementary materials that can still be obtained can be listed alongside them. That creates a clearer working file for later discussions.
Where the data volume is large, the article says software tools can be used, but the original export files and calculation rules should be preserved. If a tool classifies an operation as a sale, a reward, or an internal transfer, the basis for that classification should be reviewable. Automated results are better used for filing preparation after spot checks have been completed.
Cost basis and valuation records matter directly
On cost preparation, the article cites Articles 16 and 17 of the Implementing Regulations of the Individual Income Tax Law. It says the original value of transferred property, reasonable expenses, and the method used to compute taxable income all depend heavily on the quality of the supporting documents. If a taxpayer cannot provide complete and accurate evidence of original value, and that value cannot be determined under the prescribed method, the competent tax authority may assess it.
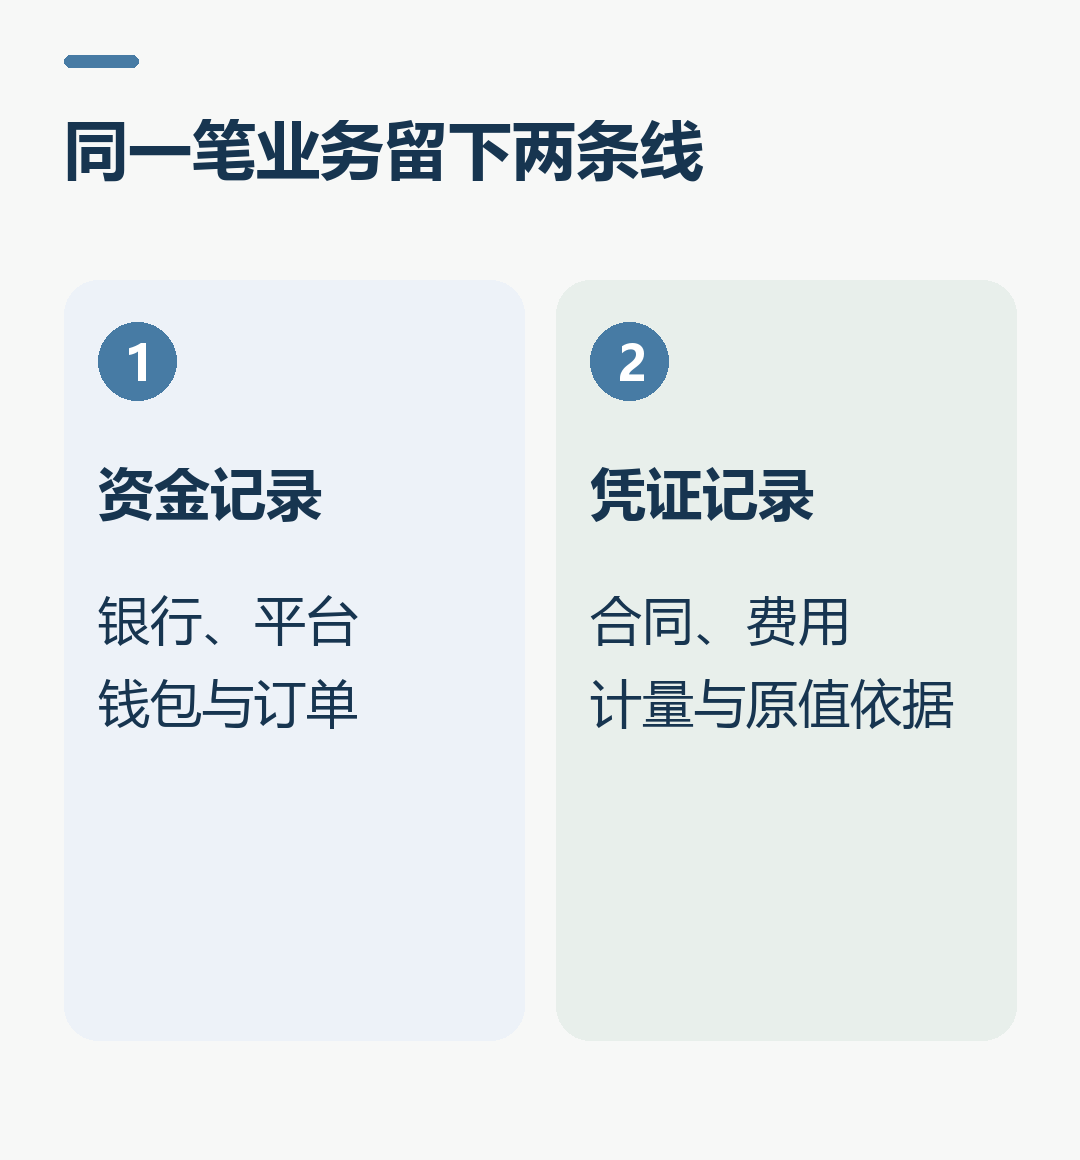
The clearest purchase evidence is a match between a bank payment and an exchange execution record. If assets were acquired through other channels, the article says taxpayers should preserve transaction agreements, proof of payment, the receiving address and transaction hash, and communications that help explain the counterparty and the purpose of the transfer.
It gives a hypothetical example under the property transfer income framework: if transfer proceeds equal RMB 300,000, the recognized original value is RMB 200,000, and reasonable expenses are RMB 10,000, then taxable income would be RMB 90,000, and the tax at 20% would be RMB 18,000. The article adds that this result depends on both the classification and the amounts having already been confirmed. In practice, each figure should be tied back to execution records, cost evidence, and expense documents so that tax officials can review them item by item.
Cases involving multiple purchases and partial disposals are more complicated. Which lot of cost belongs to which disposal, whether a consistent cost method may be used, and how losses should be handled all need to be checked against the applicable rules. The article says individuals can prepare transaction-by-transaction matching tables and calculations under different methods, but should avoid simply adopting the default tax settings of offshore software.
Fees, platform commissions, and on-chain costs should also be recorded separately. Whether a given expense directly served the relevant transaction, and whether it can be included in original value or reasonable expenses, depends on the facts and the applicable rules. A breakdown by fee type and linked transaction is more useful than a single annual total.
On valuation, the article says taxpayers should distinguish between asset pricing and foreign currency conversion. Article 8 of the Implementing Regulations includes physical items, securities, and other forms of economic benefit within individual income and sets out valuation methods. When digital assets are received as compensation, the time of receipt, quantity, contract terms, and market price data should be retained to support the taxable value.
Even if a stablecoin is quoted in U.S. dollar terms, the actual consideration and fees still need to be checked against the records. Article 32 of the Implementing Regulations also sets out rules for converting foreign-currency income and distinguishes between tax already paid and additional tax paid after year-end. The article recommends listing asset valuation prices and exchange rates separately in the working papers so each step can be reviewed.
If historical records are incomplete, the article says taxpayers can first ask the original service provider for supplementary exports, then rebuild the file using bank statements, on-chain records, and documents kept at the time. The rebuilt schedule should identify which data came from original records, which were reconstructed from other materials, and what method was used, leaving the competent authority to judge the evidentiary value.
Foreign-source income and foreign tax credits require separate support
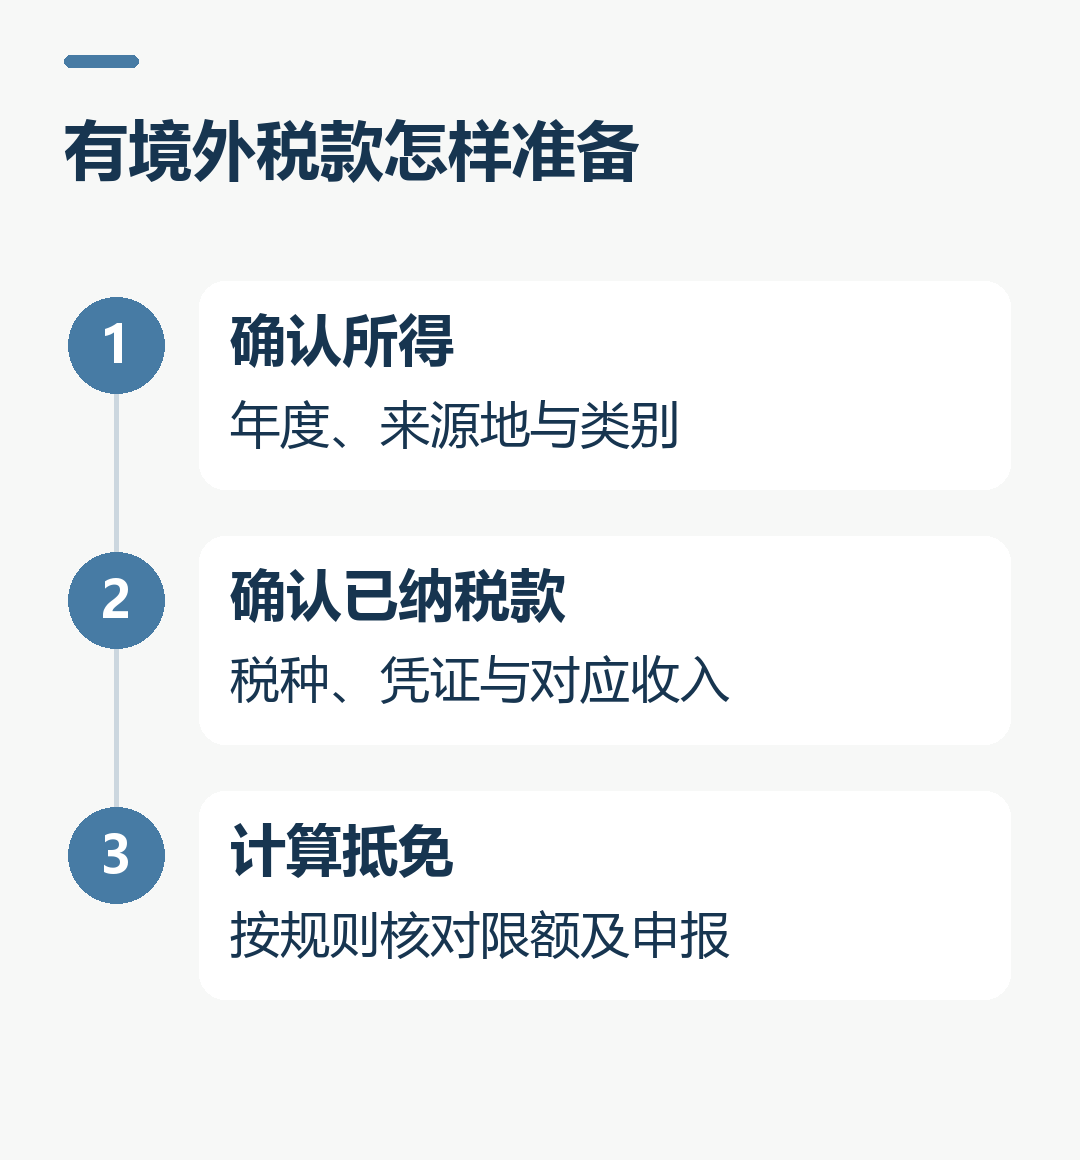
For income that is determined to be foreign-source income of a resident individual, the article points to Ministry of Finance and State Taxation Administration Announcement No. 3 of 2020, which provides rules on categorized calculation, foreign tax credits, and filing. Article 13 of the Individual Income Tax Law states that resident individuals who obtain foreign-source income should file and pay tax between March 1 and June 30 of the following year.
Before filing, the income category must be identified and then calculated under the corresponding rules. The article says comprehensive income, business income, and other income such as property transfer income are not computed in the same way. Different sources should not be merged into one net figure and reported directly. Where there are many items, they can be grouped by country or region, income category, and tax year.
Article 7 of the Individual Income Tax Law allows a credit for individual income tax lawfully paid overseas, but the credit is capped by the amount computed under Chinese tax rules. Announcement No. 3 of 2020 adds calculation and documentation requirements. Taxpayers should keep offshore tax returns, tax payment certificates, the relevant tax year, and the income records tied to those payments.
The article draws a clear line between trading fees or platform service charges withheld by offshore service providers and foreign income tax. When preparing credit materials, the taxpayer needs to confirm what kind of tax was actually paid, who levied it, and which item of income it relates to. Matching tax to income on an item-by-item basis makes it easier to review the credit limitation.
If no income tax was imposed overseas on the relevant income, there is no foreign tax amount available for credit. Whether a tax obligation arises in mainland China still depends on the person’s status, the nature of the income, and the sourcing rules. The article recommends keeping offshore treatment documents separate from domestic calculations so differences between the two systems can be explained more clearly.
For missed filings over multiple years, the article says the first step is to rebuild the records year by year, then discuss supplementary filing, corrections, and related handling with the competent tax authority. The specific procedure, tax due, and any additional liability depend on the reason for the omission and the applicable rules. A complete list of issues and documentation gaps is usually easier to move forward than repeated submissions of incomplete numbers.
Cross-border tax information may become more complete
The article also discusses the Crypto-Asset Reporting Framework, or CARF, promoted by the Organisation for Economic Co-operation and Development. CARF is designed to require relevant service providers to collect and report user and transaction information, with participating jurisdictions exchanging that information under applicable arrangements. It sits alongside the Common Reporting Standard, or CRS, which covers financial accounts, and the two frameworks do not cover exactly the same ground.
Hong Kong published a bill on May 22, 2026 to implement CARF and the revised CRS, and the proposal is still moving through the legislative process. According to the tax authority explanation cited in the article, and assuming the bill is passed, CARF-related amendments are proposed to take effect on Jan. 1, 2027, while the revised CRS is proposed to take effect on Jan. 1, 2028. When platforms will actually collect and exchange specific information still depends on the relevant implementation and exchange arrangements.
For individuals, that could mean platforms ask for tax residency status, taxpayer identification numbers, and related supporting documents. The article says those forms should match the person’s actual circumstances and should be updated when status changes. Keeping copies of what was submitted can also help explain differences in platform records across years.
The scope of information exchange depends on the laws of participating jurisdictions, the obligations imposed on service providers, and the exchange relationships that have been established. Whether a specific item of information is transmitted, and when, must be judged under those arrangements. For now, the article says the practical priority is still to make sure the individual’s own income and cost records are complete and can be matched against platform data.
That preparation can also help with routine account and bank inquiries. If a bank asks about the source of funds, the individual may be able to provide contracts, acquisition and disposal records, filing materials, and account mapping documents. The article says tax preparation and source-of-funds explanations overlap in terms of documentation, so organizing the materials in advance can reduce the pressure of finding evidence at short notice.
How to frame questions for tax authorities
Before any formal communication, the article recommends preparing a two- or three-page factual memo covering tax residency, the years involved, how the assets were acquired, the main transaction process, income and cost calculations, and any offshore treatment that has already taken place. Detailed transaction logs can go into appendices, while the main text should help the reviewing officer understand the business facts first.
The question list should focus on points that actually need confirmation. The article gives examples such as how to classify and measure compensation for development services, whether a certain disposal should be treated as property transfer income, how crypto-to-crypto swaps should be recorded, how cost should be matched for staggered purchases, and what evidence should be added where records are incomplete.
It also suggests submitting a small sample of the proposed calculation method. A few representative transactions can be selected, with the original records, conversion steps, and proposed reporting result laid out clearly. That allows the competent authority to point out adjustments directly. Once the method is confirmed, the same approach can be extended to the rest of the year’s data, which the article says usually saves time.
Any consultation result should be documented with the date, channel, facts submitted, and response received. General policy explanations, handling opinions on specific facts, and final filing outcomes should be archived separately. If the facts later change, only the changed part should be explained and checked again, rather than treating one response as if it covered every transaction.
The article adds that tax handling should also take account of source-of-funds issues and financial regulatory requirements. Mainland restrictions on virtual currency-related business remain in force, and tax materials should truthfully reflect the transactions and fund flows involved. Cases involving unusual sources, collection or payment on behalf of others, or other disputes should be assessed and handled with professional support.
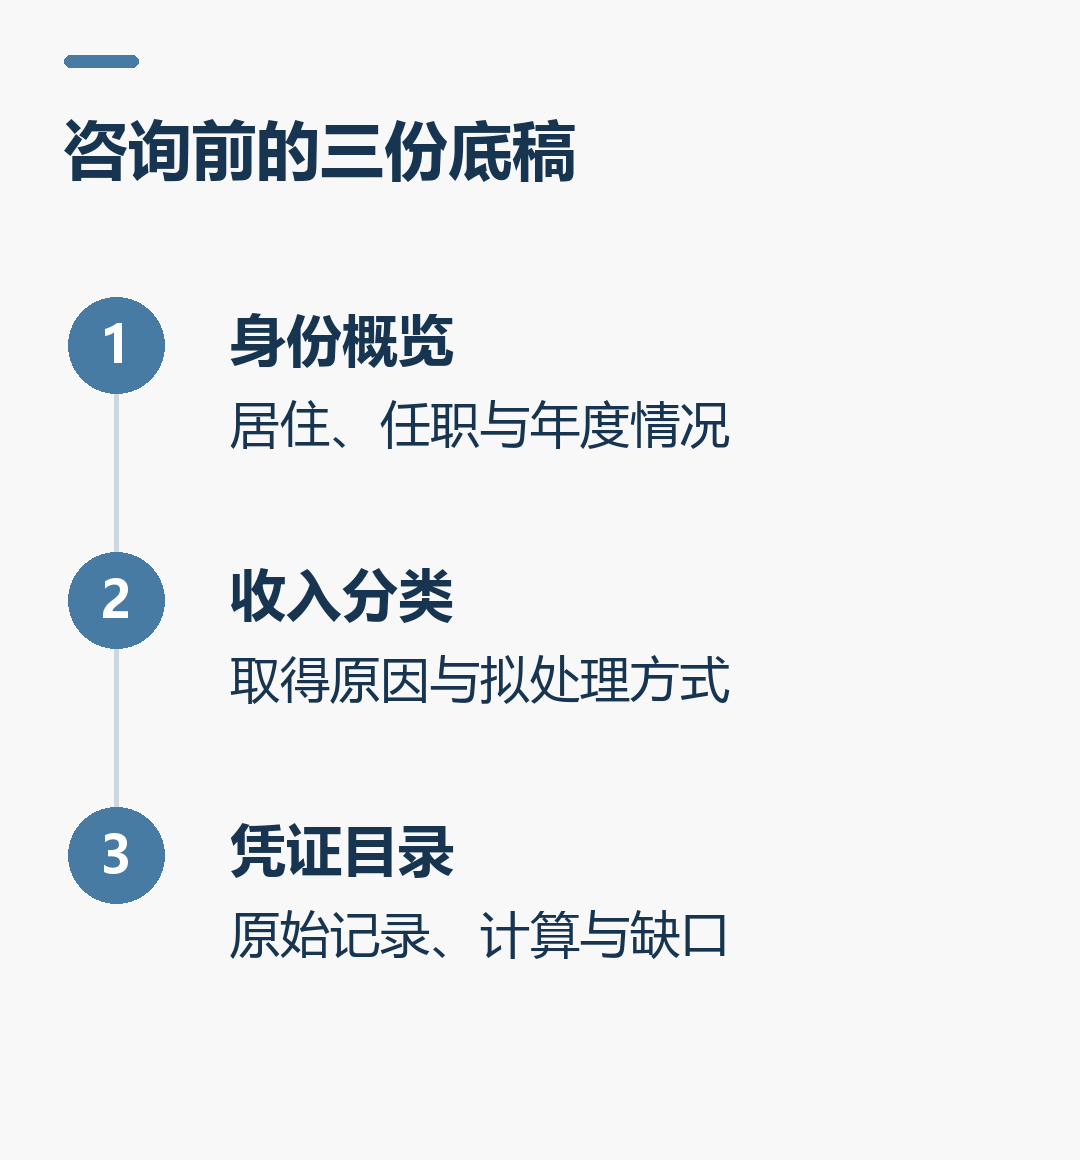
For people with a long trading history, the article says the most useful first deliverables are an annual status table, an income classification table, and a transaction-by-transaction evidence index. Those three working papers can connect records spread across banks, platforms, and wallets, giving tax advisers and the competent authority a common factual base for later filing, supplementary submissions, and corrections.
Disclaimer included in the original article
The original piece states that it is provided only for legal, policy, and industry research exchange. It says the discussion is intended as an objective analysis of digital finance, stablecoins, digital assets, and related regulatory developments, and does not constitute investment advice, legal advice, tax advice, or any other professional advice. It also says the article should not be treated as a recommendation, promotion, or solicitation for any financial product, digital asset, or commercial project.
The disclaimer adds that the regulatory rules, market data, and institutional information cited in the article mainly come from public materials and may change with laws, regulatory policy, market conditions, and project developments. Readers are asked to make their own judgments based on the latest public information and comply with the laws and regulations applicable in their own jurisdiction. The author and the publishing platform say they do not assume responsibility for investment, trading, or other commercial decisions made in reliance on the article.
A separate note at the end says markets involve risk and investment requires caution. It repeats that the article does not constitute investment advice and that readers should consider whether any opinion, view, or conclusion in the piece fits their own circumstances before acting on it.