
Multicoin Capital says the main mismatch in today’s on-chain finance is not whether real-world assets can be tokenized, but whether DeFi’s current market structure was ever built for them in the first place. In a lengthy new essay, the firm argues that most core DeFi primitives were designed for highly volatile, speculative, permissionless crypto assets. As U.S. Treasuries, equities, corporate credit, commodities, FX and other real-world assets move on-chain, tools such as AMMs, perpetual futures and open-ended floating-rate lending pools become much less suitable.
The piece is the fourth installment in Multicoin’s on-chain markets series. The firm says its earlier essays covered application-controlled execution, adverse selection in DeFi and how different categories of real-world assets could come on-chain. This latest article shifts the focus from tokenization itself to the infrastructure that would be needed once those assets arrive.
DeFi 1.0 matched native crypto assets
Multicoin defines crypto assets in the essay as native on-chain assets such as BTC, ETH, SOL and HYPE. It uses RWA to describe assets that originate outside crypto, including stocks, bonds, commodities, currencies and other traditional financial instruments.
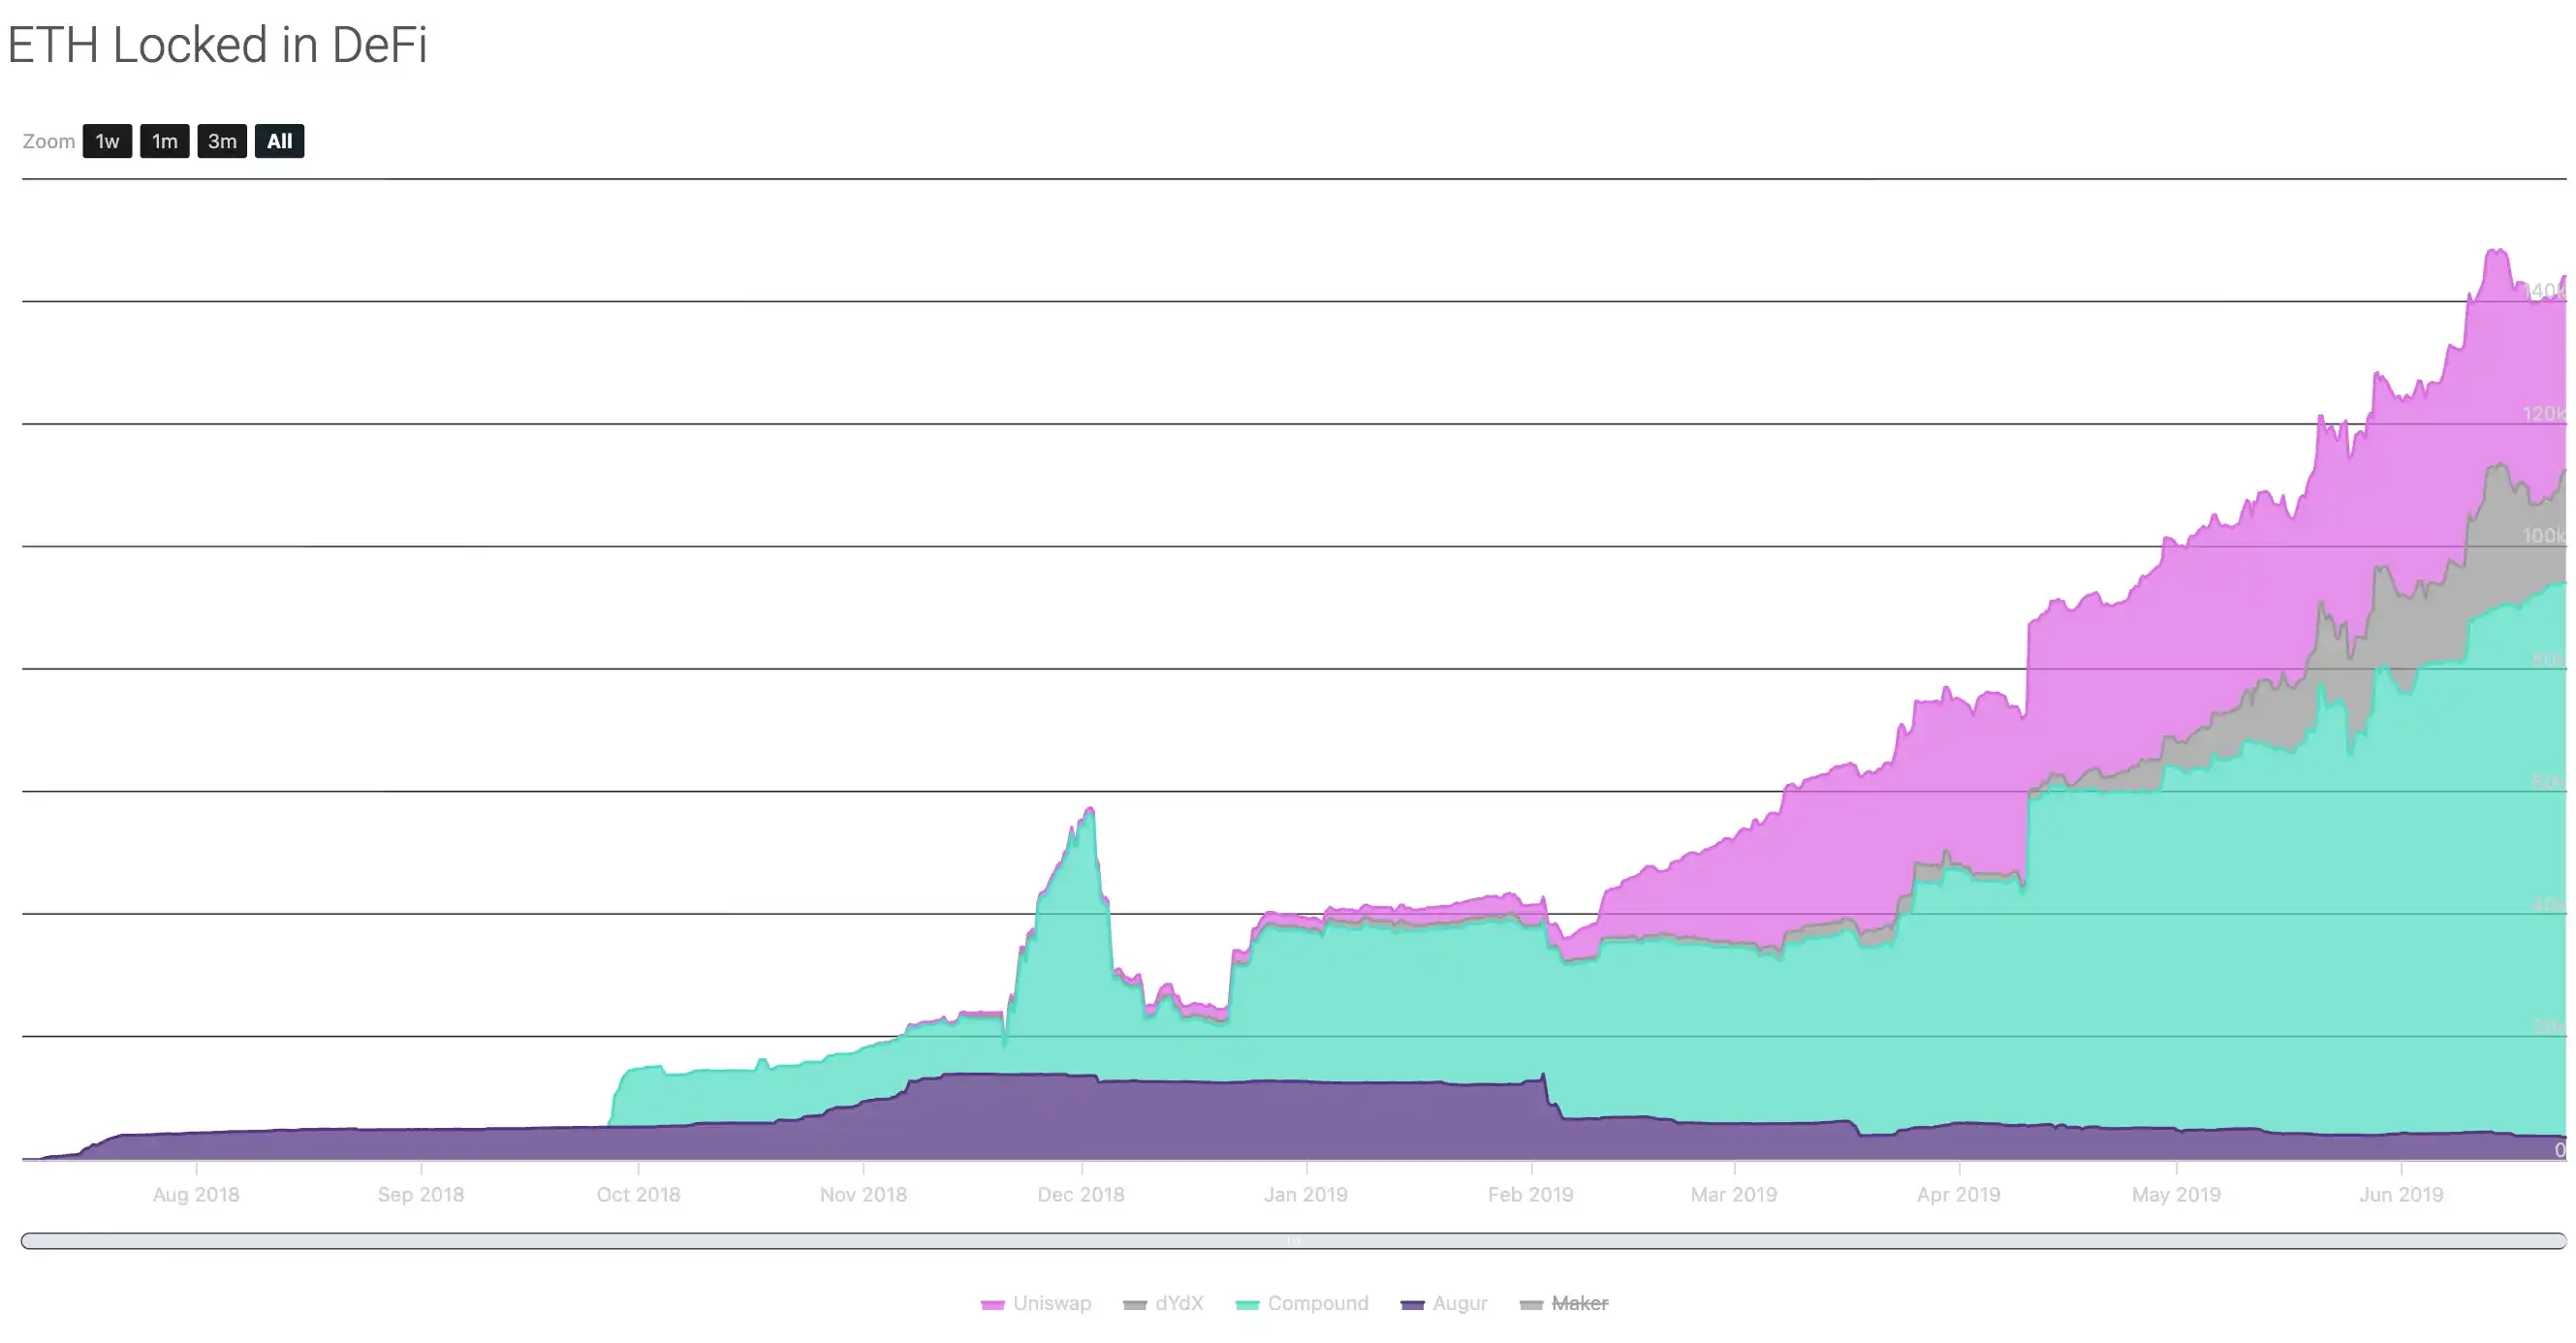
Because the first assets on blockchains were native crypto assets, early DeFi products were built around them. The paper points to AMMs such as Uniswap, vAMMs such as Perpetual Protocol, CDP stablecoin systems such as Sky, formerly MakerDAO, synthetic assets such as Synthetix, open floating-rate lending pools such as Compound and Aave, and perpetual futures venues such as dYdX.
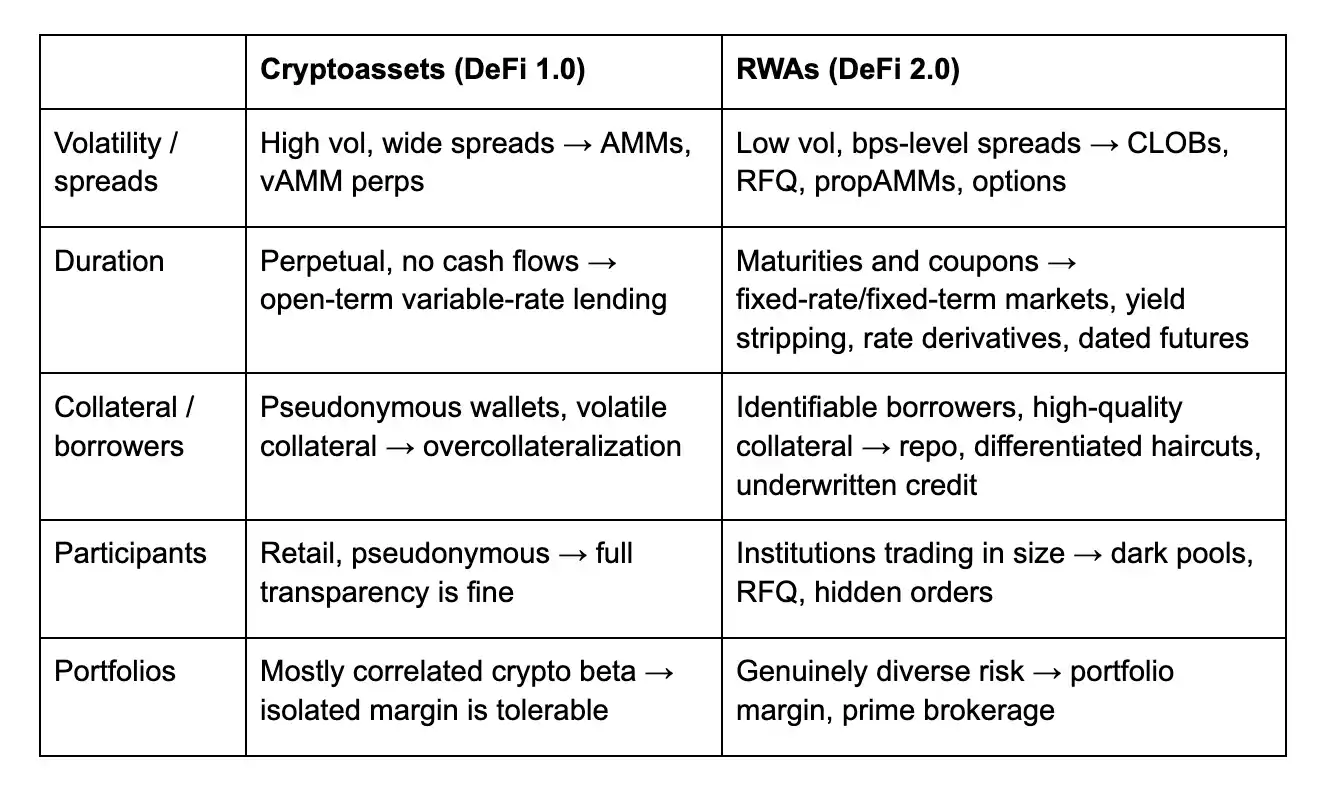
According to Multicoin, those designs worked relatively well because the underlying markets shared a common set of traits: high volatility, large speculative flows, excess long-tail token supply and permissionless access. That made products that might look inefficient in traditional finance workable in crypto.
The paper says AMMs are less capital-efficient than professional market makers, overcollateralized CDPs are an expensive way to lever long exposure, and floating-rate lending makes funding costs hard to predict while concentrating risk in a small number of pools. But in early crypto markets, the first challenge for a new asset was often getting any liquidity at all, not improving execution by a few basis points. AMMs solved that by letting anyone create a market quickly and start price discovery.
The same logic applied to lending. Anonymous borrowers had no balance sheet, no credit history and no legally enforceable repayment obligation that a smart contract could easily access. Protocols therefore relied on overcollateralization rather than formal underwriting. Multicoin says that was acceptable because many users were not borrowing to fund a business activity. They were borrowing to lever into volatile crypto assets or to extract liquidity without selling those assets. If the collateral could move 100% in a month, a few hundred basis points of borrowing cost mattered far less.
Perpetual futures fit that market structure as well. BTC, ETH, SOL and HYPE do not have maturity dates, legal claims or contractual cash flows. Traders often want continuous leveraged price exposure rather than a product with expiry. Removing the expiry date and using a synthetic perpetual structure made the product simpler and more closely aligned with the underlying asset. For short-term leveraged trading in volatile crypto, a floating funding rate was not the key constraint.
RWA change the properties of the underlying market
Multicoin’s central argument is that DeFi 1.0 was not an early version of traditional finance. It was a system built for a specific asset set and a specific user base. Change the asset base, and the primitives that make sense change with it.
The essay says the next wave of on-chain assets will bring a different mix of characteristics: lower volatility and tighter spreads, defined maturities and more predictable cash flows, stronger collateral and more identifiable borrowers, larger institutional participants, and more diverse portfolios and risk exposures.
That leads to a different set of tools becoming more important. Multicoin groups these under a DeFi 2.0 label: central limit order books, request-for-quote systems, propAMMs, fixed-rate lending, vaults, rate derivatives, repos, dark pools, portfolio margin, options and dated futures.
It adds that many of these products are not new to DeFi. In several cases, the infrastructure was built years ago, before the right assets were available on-chain in enough size.
Lower-volatility assets make execution quality matter more
For a newly launched token or a memecoin, the first question is often how to get a market started. For U.S. Treasuries, Apple stock or EUR/USD, Multicoin says that is not the problem. Those markets already have professional market makers, deep liquidity, lower volatility and very tight spreads. Execution quality matters much more.
The essay draws a simple contrast. A memecoin trader may not care about a few basis points if the token can swing 30% higher or lower in an hour, and may tolerate 2% slippage without focusing on it. In Treasury or FX markets, 10 basis points can represent the entire economics of the trade.
That is why Multicoin sees CLOBs, RFQ systems and propAMMs as a better fit for these assets. Professional market makers can price inventory using external reference prices, volatility, order flow and internal risk limits instead of posting liquidity mechanically on an AMM curve. The firm notes that these models have existed in DeFi for years, but become much more important once small differences in execution have a large economic impact.
It also says those assets are easier to seed with market makers for several reasons. There is already a large professional market-making industry trading them, along with many off-chain venues available for hedging. More attractive, more liquid assets also tend to create more retail demand. And gap risk is much lower than it is in memecoins or high-beta crypto assets, reducing the chance that market makers are caught badly offside in environments where public chains can have higher latency.
Options, structured yield and vaults may find a better home in RWA
Multicoin revisits earlier DeFi options efforts, including Ribbon, Katana and Friktion, which built automated covered call and put-selling products years ago. Some attracted attention, but the firm says the underlying assets were usually a poor fit.
A covered call strategy makes more sense for a stock that may rise 10% in a year, where giving up some upside in exchange for extra yield can be a reasonable trade. Applying that to SOL is much harder, the paper says, because SOL can move 50% in a month. The holder may be surrendering too much upside for a yield pickup that is not large enough. Multicoin acknowledges that markets can price this, but says crypto options have historically had far less liquidity than equity options.
The firm also argues that crypto options have often been less necessary because traders looking for steep risk-reward profiles could get that experience by simply going 3x long HYPE perpetuals. Options require timing decisions and include the risk of losing the entire premium.
As stocks, indices, commodities, currencies and other lower-volatility real-world assets move on-chain, Multicoin says options could finally become much more useful. Deeper options liquidity would open the door to covered calls, collars, downside protection, volatility trading and structured income products. In that reading, older DeFi options infrastructure was not conceptually wrong. It arrived before the assets it was best suited to serve.
The paper extends the same argument to vaults. Early DeFi vaults mainly automated crypto-native strategies such as yield farming, looped lending, market making and option selling on volatile tokens. With RWA on-chain, vaults could package Treasury ladders, equity covered calls, diversified credit portfolios, basis trades or mixes of fixed-rate and floating-rate exposure. The primitive is the same, but the strategy set becomes much broader.
Fixed-rate, fixed-term credit should matter more than open-ended pools
Asset maturity and cash flow structure also change the shape of lending markets. BTC, ETH, SOL and HYPE do not have expiry dates, so open-ended floating-rate loans from protocols such as Aave and Compound naturally matched traders who did not know how long they would hold a position.
Multicoin says it wrote about the opportunity for fixed-rate markets in DeFi as early as 2021, but the timing was too early because the underlying assets still did not demand that structure. A company borrowing $100 million for three years to fund an acquisition or capital expenditure plan needs to know whether annual interest expense will be $5 million or $10 million. An asset manager buying a bond at a 6% yield and financing it at 4% is expressing a 2% spread trade. If financing jumps to 6%, the trade economics disappear.
The essay says open-ended lending is structurally inefficient for another reason. Lenders want to retain the ability to withdraw on demand, while borrowers want capital for as long as possible. To accommodate withdrawals, protocols need extra liquidity buffers. That, in Multicoin’s view, helps explain the aggressive utilization curves seen in many DeFi lending pools, which are designed to stop the pool from being fully borrowed out. Some lender capital remains idle, creating a spread between what borrowers pay and what lenders receive, before adding fees charged by protocols such as Aave and Kamino.
Fixed-rate, fixed-term markets offer a different trade-off. Borrowers and lenders commit to a maturity date instead of allowing lenders to remove capital at any time. More lender capital stays deployed, and borrowers know their funding cost in advance. The cost is that liquidity becomes segmented by tenor: a three-month loan and a one-year loan are different markets. But that segmentation is also how true time-based price discovery begins and how a yield curve can eventually emerge.
Multicoin points to Morpho Midnight as one example. It creates fixed-term markets where rates are discovered through bid and ask quotes for specific maturities, and lenders can trade positions before maturity. If liquid three-month, six-month, one-year and multi-year markets develop, the market can begin to answer what capital costs at different points in time. That makes it much easier to price loans, bonds, forwards, swaps and other duration-sensitive instruments.
The paper also cites Pendle and Exponent as examples of products whose total addressable market changes as the asset base expands. These protocols split yield-bearing assets into principal and yield components, allowing users to trade fixed and floating income streams separately. Historically, on-chain yield opportunities were fairly narrow: staking rewards, lending rates, perpetual funding and, later, protocol points. One of the most prominent uses of yield tokenization became leveraged exposure to DeFi points programs.
With RWA, the range of cash flows broadens to Treasury rates, credit spreads, dividends, floating-rate loans and other contractual income streams. Yield stripping then becomes less about amplifying protocol incentives and more about separating and trading principal and income as a general-purpose financial tool.
Multicoin applies the same framework to rate derivatives. It notes that Pendle’s Boros lets users trade fixed versus floating perpetual funding at specific maturities. Today the underlying reference rate is still crypto-native. If the hedged benchmark becomes Treasury yields, corporate borrowing costs or other real-world rates, the structure becomes much more compelling.
Dated futures and forwards also fit this transition. A company hedging an FX payment due in six months does not want a perpetual instrument. Neither does a producer locking in the future sale price of a commodity, nor a bond investor hedging duration. Those exposures are dated, so the hedge instrument should be dated too.
Better collateral and identifiable borrowers change credit underwriting
Multicoin says early crypto credit started from a simple assumption: protocols knew almost nothing about the borrower. An Ethereum or Solana wallet did not come with financial statements, a credit score or a legally enforceable repayment promise. Overcollateralization solved that by making borrower identity largely irrelevant. If a user wanted to borrow $100 in USDC against ETH, Maker could require $150 in ETH and let liquidators close the position if it became unsafe.
That may be sufficient for anonymous borrowers posting volatile collateral, but it becomes much less efficient for many real-world assets. A Treasury bill is not ETH, the paper says. It has lower volatility, deeper outside liquidity and a value lenders can mark with more confidence. Requiring $150 of Treasuries to borrow $100 simply because that is how crypto lending evolved wastes much of the benefit of high-quality collateral. For Treasuries and other strong collateral, a 66% loan-to-value ratio is not sensible in Multicoin’s view.
RWA, together with more developed identity and legal frameworks, also make the borrower itself underwritable. If the borrower is a real company or fund, lenders can examine balance sheets, cash flows, management, contracts and liabilities. If the borrower is identifiable and the collateral is legally enforceable, lenders do not have to rely exclusively on collateral value.
The essay says some protocols are already starting to link repayment behavior to off-chain credit profiles and to penalize borrowers who default on-chain. It points to Maple as an example of a protocol already underwriting institutional borrowers instead of treating them as anonymous wallets.
Multicoin is blunt about why early low-collateral lending networks struggled. In its view, they fundamentally failed because the only borrowers they could attract were those unable to obtain financing in traditional markets. It cites Goldfinch’s lending to small and medium-sized businesses in emerging markets, where weak credit or geography often prevented access to attractive funding. That naturally created heavy adverse selection.
The firm adds that if U.S. regulation eventually opens the door for real businesses to access permissionless credit within a KYC and AML framework, the market could widen significantly and give global retail users access to attractive risk-adjusted lending yields.
Institutional size brings demand for dark pools, confidentiality and prime brokerage
RWA also change the identity of the trader and the size of the trade. Blockchain transparency is often treated as a feature, but the paper says that becomes more complicated when order sizes are large. Buying $20,000 of BTC is one thing. If an asset manager needs to buy $100 million of stock or bonds, exposing the full order can become extremely costly.
Traditional finance spent decades building ways to help institutions trade size without revealing intent. That is why block trading, RFQ, hidden orders, crossing networks and dark pools exist. DeFi has begun to move in the same direction. Multicoin highlights Renegade, which uses MPC and ZKP to match orders privately and settle them on-chain, Silhouette, which is building a dark pool on Hyperliquid, and portfolio company Zama, which is developing FHE primitives that applications on general-purpose chains can use to add confidentiality directly.
The essay draws a distinction between hiding settlement and hiding trading intent. Some institutions may be comfortable with trades becoming public after execution. During execution, however, Multicoin says most or all institutions will likely want confidentiality to avoid being front-run.
The firm also revisits the issue of fragmented margin systems. It says it discussed years ago how DeFi derivatives suffer from poor capital efficiency because most protocols use isolated margin. That leaves room for a crypto-native prime broker that can both extend credit against positions and net a trader’s exposure across protocols to reduce margin requirements.
That capability becomes more important as assets and positions become larger and more varied. If a Treasury position hedges an interest rate future, the system should recognize that hedge. If Alice is long SPY and short BTC in equal size, she may deserve more favorable margin treatment. Some protocols have started to offer portfolio margin, but Multicoin says a full DeFi prime broker has not appeared yet.
It cites portfolio company Project 0, which is building on Solana to bring collateral from multiple DeFi venues into a unified margin and credit system. Today that mainly improves capital efficiency within crypto markets. The value would be much larger if users could hedge Treasury exposure with rate futures, equities with options, commodities with forward futures and FX exposure with forward contracts.
Multicoin says this is another case where RWA expand the total addressable market of an existing DeFi primitive. Portfolio margin is useful when traders hold several crypto positions, but most crypto assets still share substantial underlying beta. Its value is greater when a portfolio contains genuinely different risk sources such as equities, credit, rates, commodities, FX and crypto.
In that future setup, the paper says, users would maintain a single balance sheet across asset classes rather than prefunding each venue separately. Third-party prime brokers would aggregate and net exposures across the full portfolio.
Where value could be captured
Multicoin’s answer is that the opportunity spans the stack.
The first and most obvious expansion comes from the size of the underlying asset base. Crypto assets are still only a relatively small portion of global financial assets. Equities, sovereign and corporate debt, commodities, currencies and other real-world assets are larger by orders of magnitude. Even if only a small share of those assets and their related trading activity move on-chain, the opportunity set for DeFi protocols expands materially.
But the firm says there is another dimension that matters just as much. Real-world assets often require more financial infrastructure around every dollar of asset value. A memecoin may need only a spot market, a perpetual market and maybe a lending pool if there is collateral value or demand to short it. A Treasury instrument can trade in spot markets, be financed through repo, serve as collateral, sit inside fixed-income portfolios, be hedged with futures or rate derivatives, and be embedded inside structured products. A single stock can support spot trading, securities lending, options, forwards, covered call products, portfolio margin and index exposure.
That means the opportunity is not only that more assets will sit on-chain. Each dollar of asset value can generate much more financial activity around it.
Base layers
More complex financial markets mean more transactions. Market makers update quotes, traders place and cancel orders, credit positions are funded and refinanced, options are settled, collateral moves between venues and portfolios are rebalanced. If blockchains become the execution and settlement layer for that activity, Multicoin says L1 and L2 networks can benefit from a larger and more persistent demand for block space than pure crypto speculation alone provides.
Core protocols
Exchanges can capture trading activity, lending protocols can keep part of the credit spread, rate markets can monetize duration and yield trading, and options or structured product protocols can charge for risk transfer. In many cases, the protocol already exists and only the addressable market is changing. Pendle does not need to remain mainly a market for staking yield and points. Boros does not need to remain mainly a market for perpetual funding. Options protocols do not need to stay confined to BTC and ETH volatility.
Aggregation and prime brokerage
As more venues and asset classes come on-chain, users will not want to manage financing, collateral and execution across a dozen separate protocols. That creates room for DeFi-native prime brokers that can look across the full portfolio, decide where capital should sit, how much leverage makes sense and where a trade should be executed. Multicoin says that function is already highly valuable in traditional finance and could become even more important on-chain as markets grow more fragmented and composable.
Applications and order flow
Customer-facing applications decide where a large share of activity ultimately goes. They choose routing, collateral placement, the credit market a user borrows from and the products the user sees in the first place. Multicoin says this is why control over order flow matters: it lets the holder direct flow toward the venue and liquidity provider with the best economics.
DeFi 2.0 is not a new invention so much as the right assets arriving
Multicoin closes by arguing that DeFi has already experimented with most of the primitives RWA need: order books, RFQ, options, structured products, fixed-term lending, yield stripping, rate derivatives, dark pools and portfolio margin. The problem, in its view, is that they were built for the wrong asset class at the time.
It offers a series of examples. Friktion built covered call vaults, but the underlyings were high-volatility crypto assets. Pendle split principal and yield, but much of the tradeable yield was driven by protocol points. Boros launched rate derivatives, but the reference rate was still perpetual funding. Project 0 unified margin, but most positions were still different forms of crypto exposure.
The firm is clear that the defining primitives of DeFi to date, including AMMs, perpetual futures, open floating-rate lending, vAMMs and overcollateralized stablecoins, are not going away. AMMs will still serve long-tail assets. Perpetuals will still be the main instrument for crypto speculation. Pooled overcollateralized floating-rate lending will still fit anonymous borrowers who want leverage on existing crypto assets. But if the industry’s direction is toward RWA, Multicoin says a different set of primitives is needed to support that path.
In its framing, phase one of RWA was putting assets on-chain and tokenizing them. The next phase is making them useful once they are there.
The firm says its liquidity and venture businesses are making what it describes as some of the biggest bets of their existence on opportunities emerging from DeFi 2.0 primitives. It believes those building blocks will support the next generation of on-chain assets, which it says are the assets people around the world actually want to hold. The next essay in the series, it adds, will examine why RWA need DeFi in the first place.