
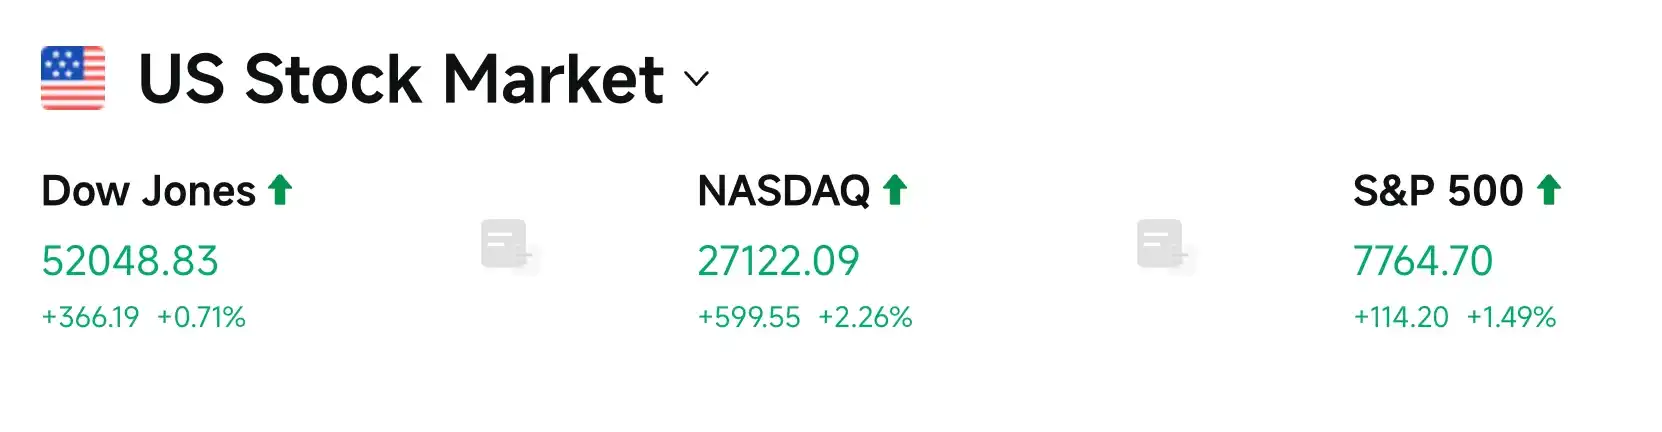
Positive signals from high-level China-U.S. trade talks in New York helped lift risk appetite across markets, sending major U.S. indexes higher with technology shares in the lead. The Dow Jones Industrial Average rose 0.71%, the S&P 500 gained 1.49%, and the Nasdaq Composite climbed 2.26% to a record close. Gold slipped as the dollar strengthened, while Bitcoin moved above $87,000 and reached its highest level in nearly eight months. Energy was the only major S&P 500 sector to finish lower on the day.
Oil falls while Fed hawkishness keeps rate pressure in focus
St. Louis Federal Reserve President Alberto Musalem said on Monday that strong demand and commodity-price shocks have spread beyond oil, and policy rates may still need to move higher to contain inflation. He said, 「Inflation is not a risk. It is here.」 He also argued that even after excluding supply-side factors such as oil, underlying inflation could still be several percentage points above target and moving in the wrong direction. In his view, earlier and more gradual tightening is preferable to delayed and aggressive action.
CME FedWatch data showed the probability of a 25-basis-point rate hike in October rising to 56.5%, with a 43.5% chance of no change. By December, the probability of a cumulative 50-basis-point increase stood at 43.9%.
International oil prices dropped for a fourth straight trading session. West Texas Intermediate crude fell 4.51% to settle at $95.78 a barrel, while Brent crude lost 3.4% to $100.34 a barrel. Both marked their lowest settlement levels since Sept. 8. The report said Saudi exports shifted quickly toward the Strait of Hormuz, with about 14 million barrels loaded over the weekend. At the same time, expectations that Donald Trump could meet Iranian President Masoud Pezeshkian during the U.N. General Assembly helped unwind geopolitical risk premium.
Robert Yawger, a commodity specialist at Mizuho, said the odds of an agreement were higher than they had been over the previous weekend. Capital Economics, however, said the gap between U.S. and Iranian demands remained wide and that meaningful progress was still uncertain. U.S. retail diesel prices also hit a record $6.51 per gallon. Senators from the Midwest called for an export ban, but the report said there was no support for that step inside the administration. Analysts warned such a ban could backfire by pushing up prices for other refined products in the domestic market.
In Treasuries, the 10-year yield fell about 4.5 basis points to 4.951%, slipping below the 5% threshold, while the 2-year yield edged up to around 4.75%, flattening the curve further. Anshul Sehgal, Goldman Sachs’ co-head of global FICC, said long-duration bonds near a 5% yield looked attractive, but the asymmetric upside in AI computing infrastructure looked even better. He added that higher interest payments were, in effect, helping fund AI buildout.
U.N. agenda and AI policy comments add to the market backdrop
The 81st session of the United Nations General Assembly general debate has begun, and Iranian Foreign Minister Abbas Araghchi has arrived in New York. The Trump administration is planning to contribute $5 billion to create an 「Allied Trust and Reconstruction Partnership」 fund and is seeking matching commitments from eight Middle Eastern countries, for a total of $10 billion. The money would be used to rebuild war-damaged energy infrastructure and reduce reliance on the Strait of Hormuz. Some Middle Eastern officials said reconstruction would be premature without a peace agreement with Iran.
Denmark, Greenland, and the United States are set to sign a security agreement at the U.N. on the morning of Sept. 22 local time. According to the report, the U.S. plans to reopen a Cold War-era base in southern Greenland and add new military presence there. Rare earth-related stocks rallied on the news. Trump also wrote on social media that 「whoever wins artificial intelligence wins victory,」 and said he would encourage AI and superintelligence development, with the Justice Department stepping in only if needed. That added to expectations of a lighter regulatory approach toward AI.
Muse drives a re-rating in CPU demand and AI infrastructure names
Meta’s AI agent Muse reached the top of the free app charts on both iPhone and Google in the United States within a week of launch, with downloads quickly surpassing those of its predecessor. The Philadelphia Semiconductor Index rose 4.29%, its best single-day performance since Aug. 4. CPU-related stocks rallied broadly, optical communications names followed, and cybersecurity shares also ranked among the day’s leaders.
Evercore analysts said Muse was a tangible sign that Meta’s roughly $200 billion in AI spending was beginning to translate into returns, potentially opening new room in advertising, subscriptions, and transaction revenue sharing. Goldman Sachs strategists described the product as a direct-to-consumer agent factory that could lift efficiency and create a multiplier effect for compute demand. At the same time, SpaceXAI launched Grok 4.7, claiming twice the speed of peers at half the price, intensifying competition in the personal agent segment. The report also said OpenAI is developing a competing feature, setting up a broader battle in personal AI assistants.
Trump’s comments about encouraging AI rather than stifling it, together with the positive tone from China-U.S. trade consultations, helped fuel gains in technology shares. Risk appetite also spilled over into crypto-related names and Greenland-linked rare earth stocks. Chinese stocks listed in the U.S. posted a modest rebound, with the Nasdaq Golden Dragon China Index up 0.71%.
Elsewhere, SoftBank-backed SB Energy delayed its IPO after valuation concerns, but Nvidia added another $1.5 billion in commitments, bringing its total investment to $3 billion. The report said that move showed hyperscale data-center demand still had backing from major industry players. Google also introduced the $899 Googlebook as it pushes into the premium notebook market and tries to make Gemini the core user experience. Even so, the report noted that capital remains heavily concentrated in AI compute and infrastructure, market breadth is still weak, and investment-grade CDS in credit markets has deteriorated to its worst level in five months.
Stock and sector moves
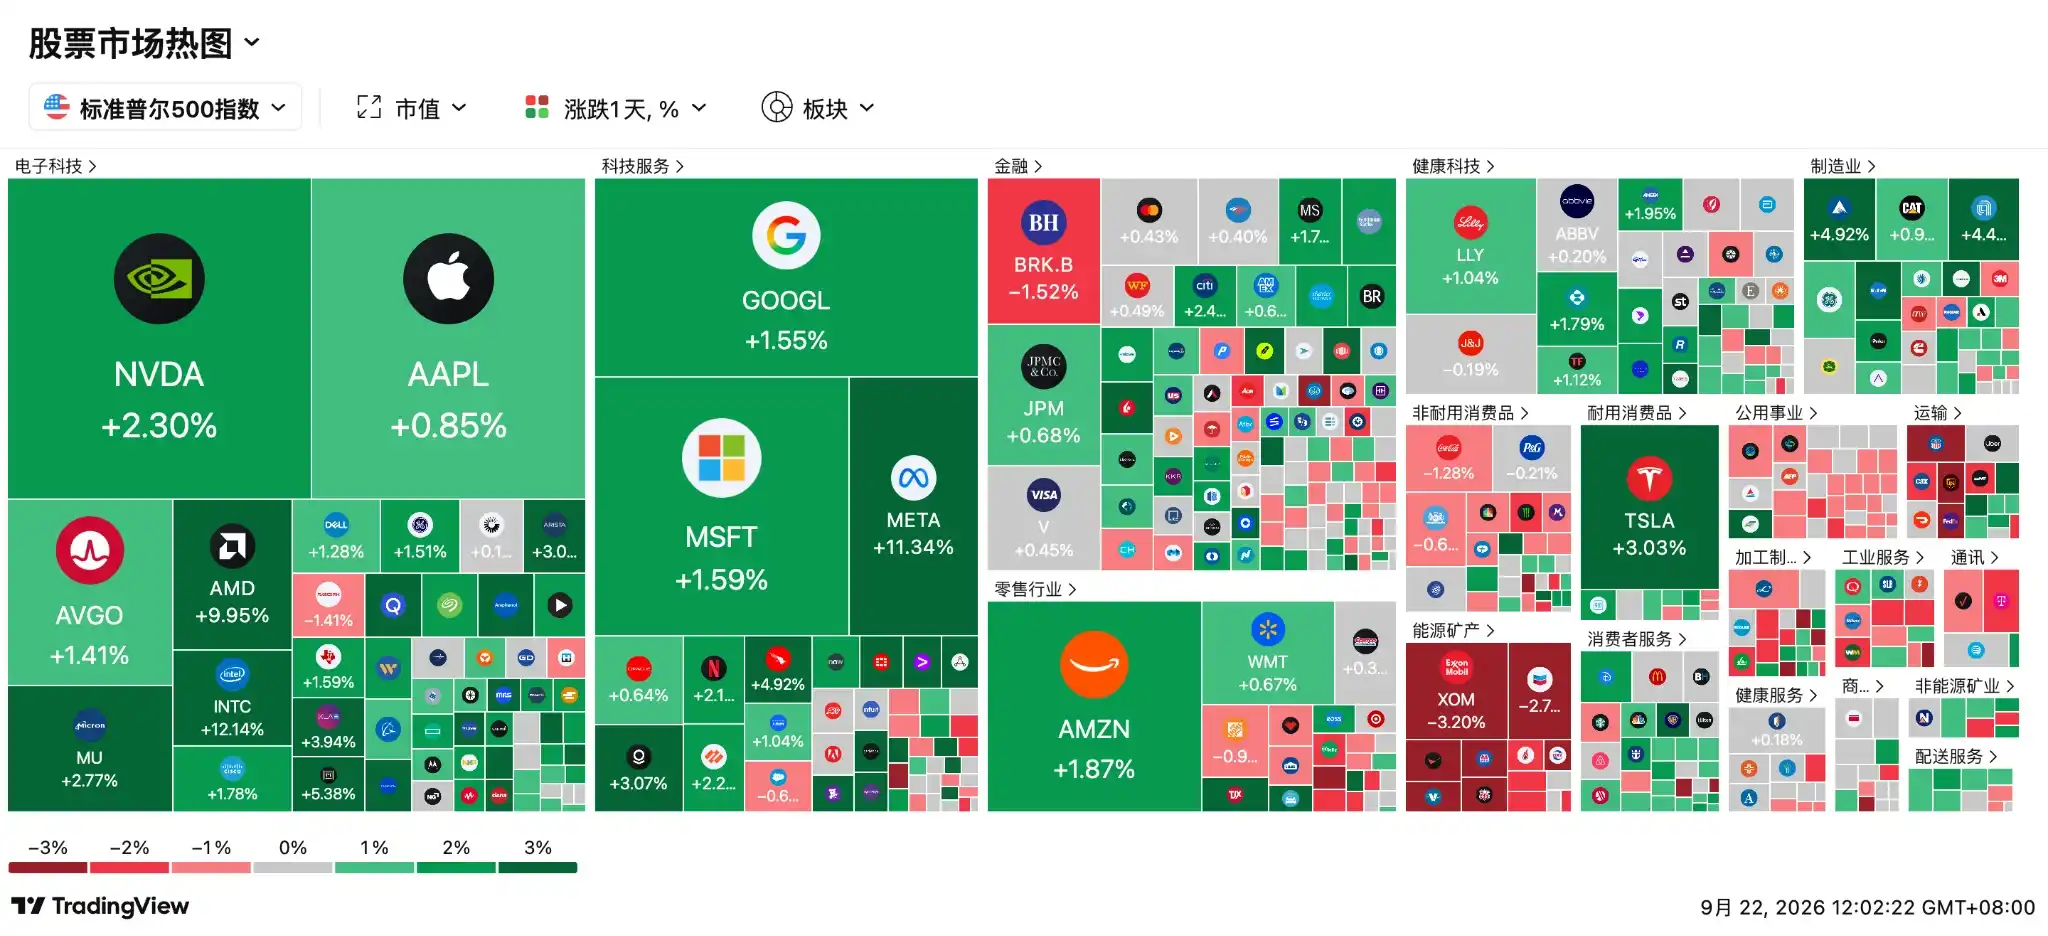
- AMD rose 9.95%, pushing its market capitalization above $1 trillion for the first time. It became the fourth U.S. chip giant to enter the trillion-dollar club after Nvidia, Broadcom, and Micron. The report tied the move to rising server demand for CPU task scheduling and system I/O as AI agents such as Meta’s Muse gain traction. Raymond James named AMD a strong buy and set a $641 price target.
- CPU-related stocks surged across the board. Arm Holdings jumped 17.16%, its biggest gain since April 2025. Intel climbed 12.14%, its largest one-day rise since May, and the report said it is working with AUO on advanced Micro LED packaging tied to next-generation CPO data-center interconnects. Qualcomm gained 9.29%.
- Meta Platforms advanced 11.43%, adding more than $190 billion in market value in a single session and posting its best performance since April 2025. Muse remained at the top of the U.S. iOS free app rankings. Evercore ISI analyst Mark Mahaney said Meta had played a trump card and that hundreds of billions of dollars in AI R&D spending were now entering the monetization phase. Wells Fargo raised its price target to $796.
- AI applications and software also moved higher. Datadog gained more than 6%, CrowdStrike and Zscaler each rose nearly 5%, and Palo Alto Networks added more than 2%.
- Critical Metals surged 38.63%. The report said the move was driven by an upcoming security agreement involving Denmark, Greenland, and Trump at U.N. headquarters, with plans to place Arctic security into a NATO multilateral framework and reports that U.S. forces could reactivate Cold War-era facilities. As the holder of the Tanbreez rare earth exploration license in Greenland, CRML drew speculative buying.
- Rare earth and critical minerals stocks posted outsized gains. Greenland Mines soared 230%, Greenland Energy jumped 140%, USA Rare Earth and TMC the metals each rose more than 9%, and MP Materials gained nearly 6%.
- Warner Bros. Discovery rose 10.79%. The report said a months-long $100 billion merger process moved closer to completion after attorneys general from California and 11 other states, along with the Writers Guild of America, reached a settlement with Paramount Skydance. Paramount committed to at least $1.5 billion in additional domestic film and television investment over five years, and the deal is expected to close in early October.
- Moderna gained 12.27%. Three abstracts on its personalized mRNA neoantigen therapy developed with Merck were accepted for presentation at the ESMO congress from Oct. 23 to Oct. 27. Novo Nordisk fell nearly 8% after weaker-than-expected Q2 sales of Wegovy tablets and a cautious full-year outlook. Eli Lilly rose 1.04% after breaking ground on a $6.5 billion oral weight-loss drug facility in Houston.
- The Magnificent Seven were mostly higher: Tesla rose 3.03%, Nvidia 2.30%, Amazon 1.87%, Google 1.55%, Apple 0.85%, and Microsoft 1.59%. The report said Tesla benefited from a new round of supply-chain factory inspections in the Yangtze River Delta tied to humanoid robots and from suppliers receiving Optimus component orders. Nvidia’s move came as Jensen Huang pushed back against calls for slower regulation and added $1.5 billion to SB Energy. Amazon blocked direct ordering access from Meta’s Muse, while Google launched the Gemini-integrated Googlebook starting at $899.
What markets are watching next
Sept. 22, Tuesday
- Trump is expected to meet representatives from Gulf states including Saudi Arabia, the UAE, Qatar, Bahrain, Kuwait, and Oman. The focus is on energy infrastructure security and shipping through the Strait of Hormuz and the Bab el-Mandeb.
- Trump is also expected to meet Volodymyr Zelenskyy and Sanae Takaichi. The Russia-Ukraine discussion will be watched for any mutual halt to attacks on energy infrastructure, while the U.S.-Japan meeting is expected to center on trade, security, and industrial cooperation. Timing has not been finalized.
- Stanley Druckenmiller is expected to visit South Korea. Markets are watching whether talks with Samsung, SK Hynix, and Doosan lead to investment arrangements.
- The Alibaba Apsara Conference runs from Sept. 22 to Sept. 24, with attention on models, agents, Agentic Cloud, and a 「five-layer full stack」 release, especially pricing, customer adoption, and revenue conversion.
- The GMIF Global Memory Industry Innovation Summit runs from Sept. 22 to Sept. 23. Investors are watching HBM, DRAM, NAND supply-demand trends and expansion plans.
- SpaceX’s 14th Starship test flight is tentatively scheduled, with materials indicating a first orbital attempt. The company has yet to confirm the launch window and mission targets.
- At 22:30, the United States, Denmark, and Greenland are set to formally sign a security and military base reopening agreement at the U.N. in New York.
Sept. 23, Wednesday
- Iranian President Masoud Pezeshkian is expected to speak at the U.N. General Assembly. Markets will watch for negotiation terms, ceasefire guarantees, and arrangements for keeping the strait open.
- Meta Connect runs from Sept. 23 to Sept. 24, with focus on smart glasses, XR devices, and AI features, especially pricing, shipment plans, and service revenue.
- Qualcomm’s Snapdragon Summit will be held from Sept. 23 to Sept. 25 Beijing time. Investors are watching for a 2-nanometer Snapdragon launch, power-efficiency improvements, and customer adoption. Rumored specifications and launch devices still await official confirmation.