


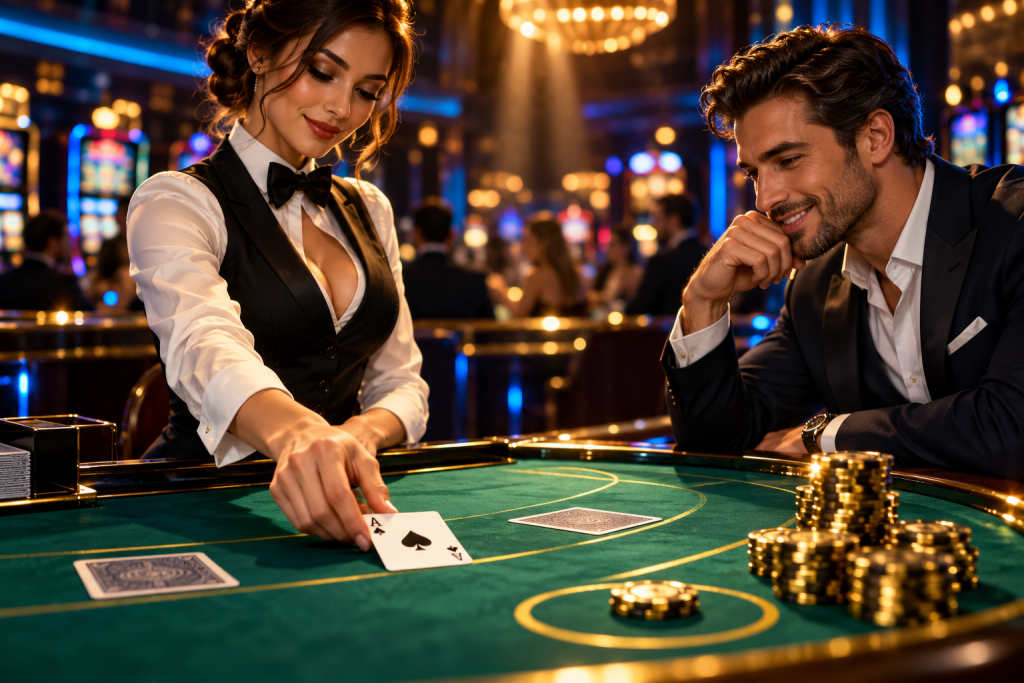
The Dealer's Ace and the Offer on the Table
You have a decent hand, the dealer turns over an ace, and before anyone acts the dealer asks a question that sounds like a safety net: insurance. It is not a refund on your hand, and it is not a way to protect the chips you already have in the circle. It is a separate wager, placed on a strip marked on the layout, that pays only if the dealer's down card makes a blackjack.
The sequence matters. Insurance is offered only when the dealer's upcard is an ace, and only before the dealer checks the hole card. You decide based on what you can see: your own two cards, the dealer's ace, and the cards already on the felt. If you take it, you place up to half your original bet in the insurance area. If the dealer then reveals a ten-value card underneath, you lose your main bet but the insurance bet is paid at 2 to 1. If the dealer does not have blackjack, the insurance bet is collected and the hand continues as normal.
What this means in practice is that the insurance wager is a bet on the identity of one unseen card. You are betting that the hole card is a ten, jack, queen or king. Nothing about your own hand changes that probability. A 16 against an ace is already a difficult spot, and insurance does not repair it; it is a second, independent wager with its own arithmetic.
What the Payout Really Represents
A 2-to-1 payout sounds generous, but the price is set against the composition of the deck. In a standard 52-card deck, sixteen cards are worth ten and thirty-six are not. When the dealer shows an ace, four of those ten-value cards are already accounted for by the ace, the dealer's hole card and your two cards, but the underlying ratio is what drives the bet's edge.
To break even on a bet that pays 2 to 1, the event you are betting on needs to happen more than one time in three. If the hole card were a ten-value card exactly one third of the time, the bet would return, on average, the amount wagered. The actual proportion of ten-value cards in a fresh deck is below that threshold, which is why the insurance bet carries a higher house edge than the main blackjack hand played with basic strategy. The house edge and the return to player for the same bet under the same rule set always sum to 100%, and for insurance the edge is materially larger than for a well-played hand.
The arithmetic is easiest to see with a single deck. With the dealer showing an ace, the player can see three cards: the ace and their own two. If neither of the player's cards is a ten-value card, there are sixteen ten-value cards left among the forty-nine unseen cards, which is just under one third. If the player holds one ten-value card, the proportion drops further. If the player holds two, it drops again. The bet only approaches a fair price when the remaining deck is unusually rich in ten-value cards, which is information a player does not have without tracking cards, and which most players will never act on.
Even Money Is the Same Bet in Disguise
When a player has a blackjack and the dealer shows an ace, the dealer may offer "even money." The words are friendlier than "insurance," but the underlying wager is identical. Taking even money means accepting a 1-to-1 payout on the blackjack right now, instead of risking the push that happens if the dealer also has blackjack.
The mechanics are the same as placing insurance for the full allowable amount. If the dealer has blackjack, the main bet pushes and the insurance bet pays 2 to 1, which nets the player the equivalent of a 1-to-1 win on the original stake. If the dealer does not have blackjack, the player wins the main bet at 3 to 2 and loses the insurance bet, which also nets the same amount. The result is identical either way: the player locks in a smaller payout than the natural blackjack would otherwise return.
What the player gives up is the chance to win at 3 to 2 when the dealer does not have blackjack, which is the more common outcome. The decision to take even money is therefore the same decision as taking insurance, just presented with different language. The table below shows how the two offers line up.
| Offer | What the player is doing | Dealer has blackjack | Dealer does not have blackjack | Net result |
|---|---|---|---|---|
| Insurance on a normal hand | Side bet up to half the main wager | Main bet loses, insurance pays 2 to 1 | Insurance loses, hand continues | Depends on the hand outcome |
| Even money on a player blackjack | Insurance for the full allowable amount | Main bet pushes, insurance pays 2 to 1 | Main bet pays 3 to 2, insurance loses | 1 to 1 on the original stake either way |
How the Decision Point Fits into a Round
Understanding insurance requires seeing where it sits in the sequence of a hand. A round of blackjack moves through a fixed order: players place their main wagers, the dealer deals two cards to each position and two to the house with one card face up, and then the dealer checks for blackjack when the upcard is an ace or a ten-value card. The insurance offer happens inside that check, before any player has hit, stood, split or doubled.
If the dealer has blackjack, the round ends immediately for most players. Those who took insurance collect on the side bet; those who did not lose their main wager unless they also have a blackjack, in which case the hand pushes. If the dealer does not have blackjack, the insurance bets are swept and play proceeds. The player who took insurance has now lost that side bet and still has to play out the main hand against a dealer ace, which is one of the stronger dealer upcards.
This is the part many new players misread. They think of insurance as protecting the hand they are about to play. It does not. The main hand is still live, still facing an ace, and still subject to the same decisions. Insurance only pays in the specific case where the dealer's blackjack would end the round, and in that case the main bet is usually lost anyway. The side bet does not soften a loss on a hand that later busts or loses to a dealer total.
Why the House Edge on Insurance Is Higher
Every bet on a blackjack table carries its own edge, and the edges are not equal. The main hand, played with a published basic-strategy chart that matches the table's rule set, carries one of the lower house edges in the casino. The insurance bet carries a much larger one because the payout does not match the underlying frequency of the event.
The comparison is structural, not a matter of luck on any given hand. A player can win an insurance bet, and will win it sometimes. But the price of the bet is set so that, over a large number of identical decisions, the amount returned is less than the amount wagered. The gap is wider than on the main game, which is why the bet is generally described as a poor-value wager for a player who is not counting cards.
Card counting changes the picture because it gives the player a running estimate of how many ten-value cards remain in the shoe. When that proportion rises far enough, the insurance bet can become a positive-expectation wager for the counter. That is a specialised skill, it requires sustained tracking of every card dealt, and it is not available to a player who is simply watching their own hand. For everyone else, the insurance bet is a separate wager with a worse expected rate of loss than the main game.
| Bet | What it pays | What the player is wagering on | How the edge compares |
|---|---|---|---|
| Main blackjack hand | 1 to 1, with 3 to 2 on a natural blackjack under common rules | Beating the dealer's total without exceeding 21 | Lower house edge when played with the correct basic strategy for the table's rules |
| Insurance side bet | 2 to 1 | The dealer's hole card being a ten-value card | Higher house edge; the payout is below the break-even frequency for a fresh deck |
| Even money on a blackjack | 1 to 1 net on the original stake | The same ten-value hole card, repackaged | Same higher edge; the player surrenders the 3-to-2 payout on the more common outcome |
What Basic Strategy Charts Say About Insurance
Published basic-strategy charts are built from a specific rule set: the number of decks, whether the dealer stands or hits on soft 17, whether doubling after splitting is allowed, and whether surrender is offered. A chart derived from one rule set may not be exactly correct for a table with different rules. That is why the charts themselves are usually presented with a note identifying the rules they assume.
On the insurance question, the charts are nearly uniform for a player who is not counting cards: do not take it. The recommendation is not a moral judgment and not a guarantee about the next hand. It is the arithmetic consequence of a bet whose payout is below the break-even frequency of the event it covers. The same charts that tell a player to hit a 16 against a dealer ten, or to split a pair of eights, also tell the player to decline insurance, because every entry in the chart is the play that minimises the expected loss under the stated rules.
A player who wants to use a strategy chart should first read the rule assumptions printed with it, then compare them to the table where they are sitting. The number of decks is usually posted on the table or the shoe. The dealer's soft-17 rule is printed on the layout. Doubling and splitting rules are also on the felt. If the chart's assumptions do not match the table, the chart is not the right one for that game.
The Procedural Mistakes That Cost Players on Insurance
The first mistake is taking insurance reflexively because it sounds protective. The word itself does the work of persuasion, and the dealer's neutral offer is not advice. A player who takes insurance on every dealer ace is adding a high-edge side bet to a game that is otherwise one of the better-value table games when played correctly.
The second mistake is taking even money on a blackjack because a certain payout feels better than a chance at more. The player is accepting the same high-edge side bet, but the framing hides it. The hand is already a winner unless the dealer also has blackjack, and the dealer will not have it more often than they will. Accepting even money converts a strong position into a smaller, guaranteed-by-mechanism payout at the cost of the higher expected value of the natural blackjack.
The third mistake is trying to hedge a weak hand with insurance. A player holding a 15 or 16 against a dealer ace is in a losing position, and insurance does not change that. The side bet only pays if the dealer has blackjack, in which case the main bet is lost regardless. If the dealer does not have blackjack, the insurance bet is lost and the weak hand still has to be played. The two wagers are independent, and adding the second one does not improve the first.
FAQ
Can I take insurance for less than half my original bet?
Yes. The insurance wager may be placed for any amount up to the table's posted maximum, which is commonly half the main bet. The payout is always 2 to 1 on the amount placed in the insurance area. Taking a smaller amount does not change the edge on the bet; it only changes the size of the side wager.
Does insurance pay if the dealer draws to 21 later in the hand?
No. Insurance is settled immediately when the dealer checks the hole card, before any further cards are drawn. It pays only if the dealer's two-card starting hand is a blackjack. A dealer who later draws to a total of 21 with three or more cards has not made a blackjack, and the insurance bet is not paid on that outcome.
Is insurance ever a good idea for a player who is not counting cards?
Published basic-strategy charts, derived from the specific rule set in use, point away from insurance for a player who is not tracking the proportion of ten-value cards remaining. The bet's payout is below the break-even frequency of the event in a fresh deck, which gives it a higher house edge than the main hand. Individual results will vary hand to hand, but the arithmetic does not change.
Gambling can be addictive. Please play responsibly. If you or someone you know is struggling with gambling addiction, call the National Problem Gambling Helpline at the helpline printed in the footer below or text the helpline printed in the footer below. Help is available 24/7. Must be 21+ to gamble. Please check your local laws and regulations.
Play responsibly
Gambling should be treated as paid entertainment, never as a way to earn income or recover losses. 1-800-MY-RESET (1-800-697-3738)
18+ or 21+ depending on where you are; follow the minimum age that applies to you.
This article is general information about how these mechanics work. It is not legal advice and not a recommendation to gamble or to use any particular operator. Availability and legality differ by jurisdiction — check the rules that apply where you are.