
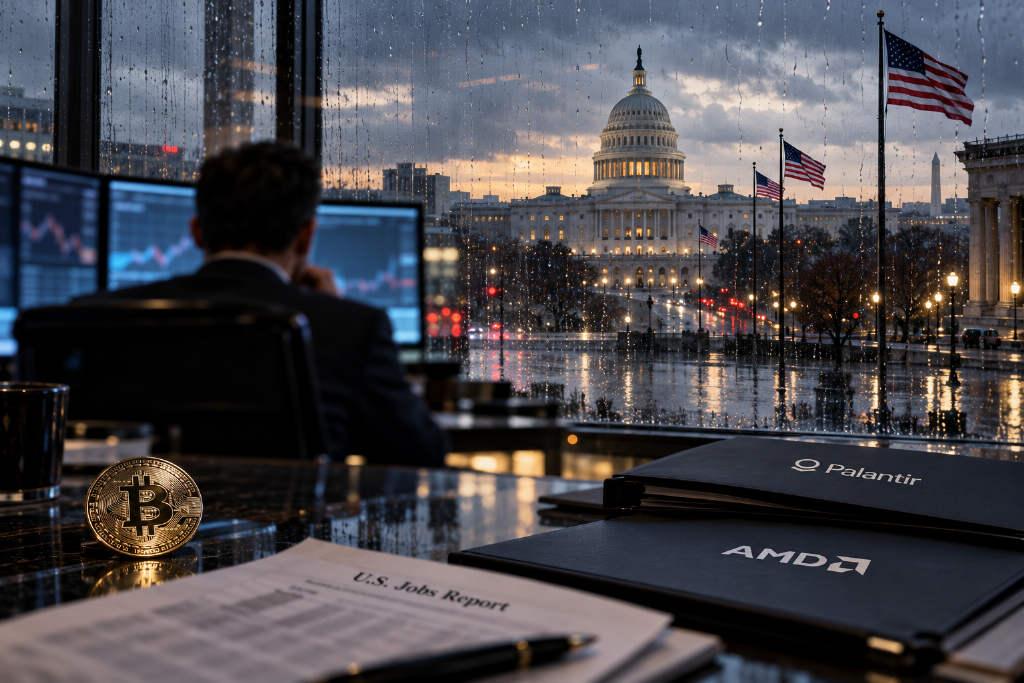
Bitcoin is entering November with three major market tests approaching in quick succession: the U.S. midterm elections, the October nonfarm payrolls report, and earnings from major technology companies tied to the AI trade. The sequence could reshape expectations for the Federal Reserve’s December rate decision and add fresh volatility to risk assets.
With BTC already below $80,000 and down about 8.7% over the past 30 days, the report said the latest price was hovering around $77,565. Market attention is now centered on whether the area near $77,000 can hold as support.
U.S. midterm elections put policy and regulatory outlook in focus
The U.S. is set to hold its midterm elections on Nov. 3 local time, with all 435 seats in the House of Representatives and about one-third of Senate seats up for election. The outcome will determine the balance of power in Congress for the next two years and could affect the environment for fiscal policy, financial regulation, and crypto legislation.
For the digital asset sector, the report said traders will be watching the regulatory path for stablecoins, digital asset trading platforms, and prediction markets. A different congressional makeup could change the direction of bill negotiations and administrative oversight.
At the same time, the article stressed that the midterms do not directly determine Fed interest rates, and there is not enough basis to say any specific election outcome would automatically lift or pressure Bitcoin. Vote counting in some districts could also continue for several days, which may prolong policy uncertainty if control of Congress is not immediately clear.
Nonfarm payrolls on Nov. 6 may reset December Fed expectations
According to the official schedule from the U.S. Bureau of Labor Statistics, the October nonfarm payrolls report will be released at 8:30 a.m. Eastern Time on Nov. 6, which the article noted is 9:30 p.m. Friday in Taiwan. Markets will focus on headline job creation, the unemployment rate, average hourly earnings, and any revisions to prior employment data.
The report also pointed to the Fed’s Oct. 28 rate meeting, where officials kept the federal funds target range at 3.75% to 4.00%. The vote was 10-2, with two officials favoring a 25-basis-point increase, showing that inflation risk remains a source of disagreement inside the central bank.
That makes the November labor report more important for markets. If job growth and wage gains come in well above expectations, traders may increase bets that the Fed will keep rates high or even raise them again. That could push up the U.S. dollar and Treasury yields, adding pressure to risk assets including BTC.
If employment cools sharply, the case for further tightening may weaken. But the article said an overly weak report could also revive recession concerns, which does not automatically mean Bitcoin would rebound. The next Fed rate decision is scheduled for Dec. 9 Eastern Time, making this payrolls release one of the key data points for reassessing the year-end rate path.
Palantir and AMD earnings add another test for risk sentiment
Beyond politics and macro data, technology earnings are another major focus this week. Based on company announcements cited in the report, AI software company Palantir (PLTR) is scheduled to release third-quarter results after the close on Nov. 2 Eastern Time, while chipmaker Advanced Micro Devices (AMD) will report after the close on Nov. 3. The article converted those times to early Tuesday and Wednesday in Taiwan.
Markets will be watching Palantir’s AI software demand and enterprise contract growth, along with AMD’s performance in data center and AI accelerator businesses. Qualcomm and AppLovin are also scheduled to report this week, offering more signals on chip demand, AI commercialization, and capital spending across the technology sector.
For Bitcoin, the importance of these earnings lies in broader risk appetite. The article said BTC and technology stocks have both faced selling pressure recently, suggesting that some capital may be reducing exposure to AI growth names and cryptocurrencies at the same time. If earnings renew concerns about returns on AI investment, that could weigh further on sentiment.
Still, Bitcoin and the Nasdaq do not always move in lockstep, and strong earnings from technology companies do not guarantee gains in crypto assets.
$77,000 and the 50-week moving average are key levels to watch
On price action, the article said a verifiable Binance quote on Nov. 1 showed BTC at about $77,723, up 0.3% over 24 hours, with a market capitalization of roughly $1.56 trillion. It also said Bitcoin was down more than 10% over the past 30 days.
From a market structure standpoint, the area around $77,000 has become an important short-term zone. If the price moves lower, traders may also look to the 50-week moving average previously highlighted by Galaxy Research.
In an October report, Galaxy Research head Alex Thorn said the 50-week moving average near $76,540 is an important reference point in his framework for judging whether Bitcoin’s bear market has ended. The article added that Galaxy’s warning condition is not an intraday break below that level. Instead, it would require a weekly close below it and roughly a month without reclaiming it. The moving average itself also changes over time.
That leaves the $77,000 area as a near-term observation zone, while the region around $76,500 serves as a medium-term technical reference. The article said neither level should be treated as guaranteed support.
Three events, three channels of market impact
In its closing section, the report said the U.S. midterms, nonfarm payrolls, and technology earnings could affect markets through different channels. The election mainly shapes policy expectations. The jobs report directly influences economic pricing and rate expectations. Tech earnings feed into confidence around AI investment and broader global risk appetite.
The outcomes could also offset one another. A softer labor report, for example, might cool expectations for further rate increases, but disappointing earnings from technology companies could still lead investors to cut risk exposure.
The article also noted that Bitcoin is influenced by other factors, including flows into and out of U.S. spot ETFs, spot selling pressure on exchanges, and leverage in derivatives markets. It said price moves should not be attributed to a single macro event alone.
For Bitcoin, the real test in the first week of November is whether political uncertainty, rate expectations, and technology-sector risk sentiment will push more capital out of the market or help create new buying interest while BTC trades back near $77,000. Before the payrolls report and corporate earnings are released, the article said there is still not enough evidence to confirm that the $77,000 area has formed a stable bottom.


