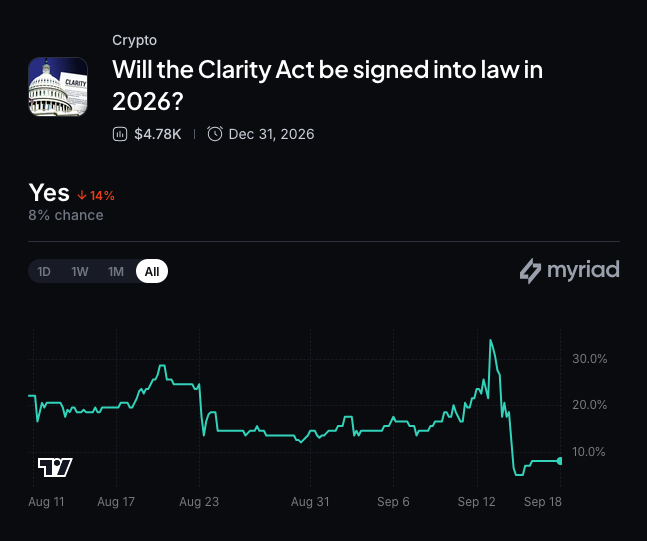
U.S. crypto policy took a clear turn this week. After the Senate failed to move the Clarity Act forward, momentum shifted away from Congress and toward regulators.
On Tuesday, the Senate failed to advance the landmark crypto market structure bill in a procedural vote that highlighted how President Trump’s crypto dealings have weakened Democrats’ willingness to work with Republicans on rules for an industry that Democrats themselves say needs oversight.
Democrats voted as a bloc against advancing the bill. Republican Senators Susan Collins of Maine, Josh Hawley of Missouri, and Jerry Moran of Kansas also voted no. Senator Thom Tillis of North Carolina initially voted yes, then switched to no, a procedural step that preserved the option of bringing the bill back later.
The final recorded tally was 49-50, well short of the 60 votes required to advance the measure. That result came after more than a year of difficult bipartisan negotiations.
Talks continued until the vote began
Negotiations were still underway in the Capitol basement right up to the start of the vote. According to Crypto In America, a Democratic staffer said Tillis was willing to delay the vote to keep negotiating, but a staffer for Senate Banking Committee Chair Tim Scott abruptly ended the talks without explanation.
After that, both sides blamed each other. Republicans accused Democrats of never being serious about passing the bill. Democrats said Republican leaders forced the vote before negotiations were finished in order to protect what one staffer called Trump’s “grift.”
Senator Cynthia Lummis of Wyoming, the bill’s chief architect, said: 「Senate Democrats proved they were never truly serious about protecting consumers and preserving American leadership. I sat at the table with Senate Democrats working in good faith to get this done while they played games.」
Supporters say the bill is still alive
Some of the Democrats who voted no said the legislation is not finished.
Immediately after the vote, Senator Angela Alsobrooks of Maryland told Crypto In America: 「It’s not going to die. You know why it’s not going to die? Because over 70 million Americans are engaging in an industry that is unregulated, and we have a responsibility to regulate.」
Alsobrooks was joined by six other Democrats involved in the negotiations: Senators Kirsten Gillibrand of New York, Mark Warner of Virginia, Cory Booker of New Jersey, Catherine Cortez Masto of Nevada, Ruben Gallego of Arizona, and Raphael Warnock of Georgia. The group described this week’s vote as 「a setback, but not the end」 and said it remained 「committed to working in a bipartisan fashion」 to pass the Clarity Act.
According to three sources familiar with the discussions, that statement came as early efforts were already underway to restart bipartisan talks and test whether both sides were willing to return to the table.
Industry attention is moving to regulators
Even so, fatigue is building across the crypto industry. Many are now looking to regulators to write the rules instead of waiting for Congress.
Kristin Smith, president of the Solana Policy Institute, said Congress passed the GENIUS Act and pushed hard on the Clarity Act, but lacked the political will to get it over the finish line. She said the industry is now looking to regulators for guidance because that is the more viable path at the moment.
SEC and CFTC are already acting
SEC Chair Paul Atkins explicitly linked the agency’s new innovation exemption to the Senate’s failure to advance the Clarity Act. The SEC released the measure on Thursday. It opens a path for tokenized U.S. stocks to trade onchain and has added fresh excitement across the industry as regulators take a more central role.
The Commodity Futures Trading Commission is moving as well. Staff issued a no-action position for passive software providers, and the agency submitted a broader crypto markets rulemaking proposal to the White House for review. The details of that proposal have not been made public.
For the crypto industry, clarity is arriving in one form or another. For now, it is coming from regulators rather than Congress.
The reporting cited in the Decrypt piece came from Crypto In America, a newsletter written by Eleanor Terrett.