
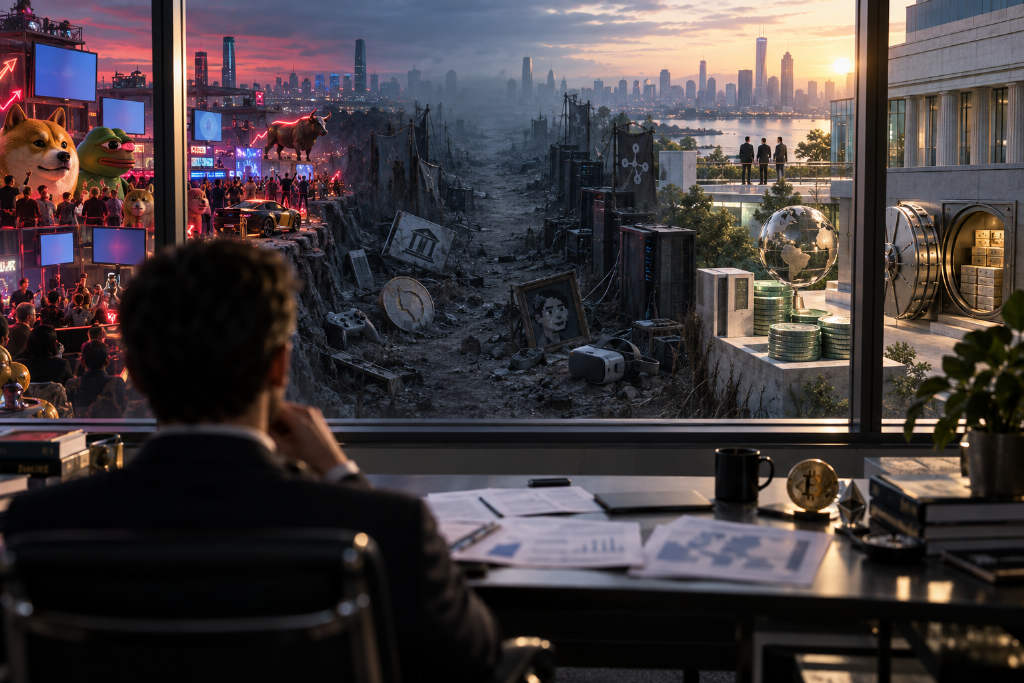
TechFlowPost has published a market analysis arguing that a large share of crypto’s idealistic experiments have effectively run their course by 2026. The piece, written by 100y_eth and translated by Saoirse for Foresight News, says concepts once attached to crypto’s most ambitious vision — decentralization, community ownership, code as law, trustless verification, creator economies, network states, and new forms of governance — brought a wave of builders into the industry, but most of the products built around those ideas did not last.

The article lists a long chain of sectors that drew attention over the past cycle: DAOs, fan tokens, ve (3,3), NFTs, IP NFTs, music NFTs, Bitcoin inscriptions and Runes, Bitcoin layer-2 networks, Play-to-Earn, Move-to-Earn, metaverse projects, fully on-chain games, gaming guilds, decentralized social, decentralized identity, on-chain reputation, soulbound tokens, algorithmic stablecoins, restaking, InfoFi, appchains, modular blockchains, zkEVM, Rollup-as-a-Service, intent-based trading, chain abstraction, DePIN, decentralized energy, ReFi, DeSci, data markets, and decentralized AI compute. Its conclusion is blunt: most of these experiments failed.
Bitcoin ecosystem projects lost steam
The analysis begins with Bitcoin-related experiments. Inscriptions, Ordinals NFTs, and Runes used fields such as SegWit and OP_RETURN to store arbitrary data on Bitcoin transactions. That narrative once fueled the view that Bitcoin could also become a venue for token issuance and NFTs. In 2023, inscriptions pushed Bitcoin network fees sharply higher, and some argued those fees could help offset the decline in block rewards.
Now, according to the article, their impact on network fees is close to negligible. Ordinal Maxi Biz, once a leading Ordinals NFT collection, reached a floor price of 1.5 BTC at its peak. Recent trades were around 0.018 BTC. Magic Eden, previously the largest Bitcoin NFT marketplace, stopped its Bitcoin NFT trading business in March this year.
The piece makes a similar point about Bitcoin layer 2s. Technologies such as Taproot and BitVM had encouraged the market to believe that programmable, scalable networks could be built on top of Bitcoin’s security. Many projects raised money from major venture firms. But the overall ecosystem now looks weak, the article says. BOB, the Bitcoin layer-2 project with the highest total value locked, has seen TVL fall 96.6% from its peak to $9.24 million. Corn, BEVM, and Lorenzo have fully pivoted, while Botanix has shut down.
Ethereum kept its lead while many L1 and L2 challengers failed to break through
The report compares Ethereum’s share of DeFi TVL with that of other public blockchains from 2021 to 2026 and says the competitive landscape has changed far less than many expected. New chains and layer-2 networks often claimed they could outperform Ethereum on scaling, incentives, contract security, or go-to-market execution. Still, many never found product-market fit and ended up as chains with little real usage.
Its assessment is that, aside from BNB Chain, TRON, Solana, and Base, most chains failed to take meaningful market share away from Ethereum.
Infrastructure narratives cooled: modular stacks and restaking both pulled back
Modular blockchains were one of the hottest infrastructure themes in 2022 and 2023. Starting from data availability layers, the market produced shared sequencers, Rollup-as-a-Service providers, and many rollup designs. The article says the modular thesis itself was not flawed. Arbitrum, Base, and Robinhood Chain are described as still operating steadily. But many of the startups that drew attention during that cycle either pivoted or shut down. In that sense, the broader modular boom is presented as a failed industry experiment.

Restaking followed a similar arc. EigenLayer started the category, and projects including Symbiotic, Karak, Babylon, and Solayer followed. TVL for the sector climbed to nearly $30 billion at its peak before falling back to about $8 billion, a deeper drawdown than in several other DeFi segments.
The article’s explanation is straightforward: the market has plenty of reusable security, but not enough real demand from businesses that need to consume that security. It says EigenLayer has made a soft pivot toward EigenCloud for AI agents, Symbiotic has shifted toward high-performance chains, and Karak has become a collateral trading platform.
Algorithmic stablecoins remain a cautionary zone
Algorithmic stablecoins aimed to create decentralized on-chain money without full collateral backing, promising better capital efficiency. Terra’s UST, now USTC, became the best-known example. Its circulating supply rose past $18 billion, putting it among the top crypto assets by market value.
The article says UST collapsed to zero after external attacks combined with flaws in the underlying mechanism, taking the wider Terra ecosystem down with it. FEI, IRON, and ESD are cited as other failed examples. FRAX began with an algorithmic design but later shifted to a fiat-collateralized model. The report says that after Terra, algorithmic stablecoins became almost untouchable inside crypto.
NFTs, blockchain gaming, and metaverse projects all retreated
NFTs broke into mainstream attention after taking off on Ethereum in 2021 and later expanding into ecosystems such as Solana and Klaytn. The report highlights how far blue-chip collection prices have fallen: CryptoPunks dropped from 125 ETH to 32 ETH, BAYC from 150 ETH to 8 ETH, Pudgy Penguins from 35 ETH to 3.8 ETH, and Azuki from 30 ETH to 0.8 ETH. OpenSea’s monthly trading volume shrank from a $5 billion peak to roughly $30 million.
Play-to-Earn was built around the idea that players should own in-game economies and share in the value created by a game. But for that model to hold, the game has to generate real economic value or convince users to keep paying. The article argues that neither condition was met at scale, and most projects collapsed.
Axie Infinity, the game that drove the first major P2E wave, once reached 6.5 million monthly active wallets and generated peak fees of $103.8 million. It now has fewer than 100,000 monthly active wallets and less than $50,000 in monthly fees. Metaverse land NFT projects such as Sandbox and Decentraland also faded. Sandbox land NFTs fell from around $15,000 to $50, a 99% drop. Move-to-Earn apps such as StepN and Sweat lost momentum quickly. AAA-style blockchain games including Star Atlas and Otherside still have not officially launched, and fully on-chain gaming has not reached a mass mainstream audience.

Decentralized social and InfoFi also failed to keep their early promise
Decentralized social was often framed as the clearest version of the “users own the internet” idea. Projects such as Farcaster, Lens, and DeSo promised user-controlled social graphs, permissionless access, and censorship resistance.
According to the article, however, most of these products struggled to retain real users once short-term token incentives faded. Activity dropped sharply across the segment. The data shown for Farcaster indicates that after a spike in March 2026, both daily active users and on-chain interaction volumes moved lower.
The report makes a similar case about InfoFi. Kaito helped define the category by tying online attention and content creation to financial rewards. It says the model initially produced a good amount of quality content, but later devolved into traffic farming and reward extraction, with spam taking over. After X shut off the relevant API access, Kaito’s Yaps, Cookie DAO’s Snaps, and Wallchain’s Quacks all ceased operations.
2026 brought a broader wave of closures and pivots
The article says many in the market already believed idealistic crypto experiments had mostly ended in 2024 and 2025, as attention shifted from grand narratives to areas such as stablecoins and tokenized assets that looked easier to commercialize. But it argues conditions kept deteriorating.
At that stage, innovation had stalled and both capital and traffic were leaving, yet older projects could still survive on prior funding and operational inertia. In 2026, that buffer ran out. The result, the piece says, was a wave of shutdowns and strategic pivots across centralized exchanges, data tools, base-layer chains, layer 2s, infrastructure projects, DeFi products, games, and NFT platforms.
A barbell market emerged, with the middle hollowed out
The report’s main conclusion is that crypto has turned into a barbell market. One end serves speculative demand. The other serves steadier business demand tied to the real economy. Native on-chain products sitting in the middle, with less clear risk-return characteristics, have suffered the most.
It gives three reasons for the collapse of that middle ground.

- First, most products never found product-market fit. Some examples that once looked successful now appear, in the article’s telling, to have been inflated by airdrops rather than real utility.
- Second, the risk-reward profile has worsened. The article says stablecoin farming that once produced 15% to 20% annualized returns now struggles to offer 5% to 10%. Users have split into two groups: those moving toward RWA for lower-risk returns of 3% to 7%, and those moving toward meme coins, perpetuals, and prediction markets in search of outsized upside.
- Third, hacking risk has risen. As large-model AI tools improve, the report says on-chain attacks are becoming more frequent. Lower expected returns, combined with a higher risk of losing principal, have made many ordinary on-chain products less appealing.
At the same time, the sectors at both ends of the barbell have continued to post stronger data, even as the rest of the market weakened.
The speculative end: meme coins, prediction markets, and perpetual DEXs
Meme coins stayed resilient
The article says speculation is not unique to crypto, but blockchains have become an efficient vehicle for it because they combine smart contracts, transparent on-chain records, and instant settlement. As conventional DeFi became less attractive, users moved into meme coins, prediction markets, and decentralized perpetual trading.
Demand for meme coins is described as a line stretching from DOGE in 2013 through SHIB, BONK, and PEPE. In 2024, Solana names such as WIF, POPCAT, MEW, GOAT, and FARTCOIN drove another boom. The article says the real structural shift came from shturl.c, launched in 2024, because it allowed anyone to create a meme coin with a single click.
Even as spot DEX volume fell by nearly 80% over the past year, the report says shturl.c’s revenue remained resilient. Revenue doubled from its recent low and topped $2 million in August and September 2026. The platform uses a “graduation” system in which a token moves from a bonding curve to an AMM pool after reaching a market cap threshold. The share of tokens that completed graduation rose from less than 1% on average to more than 3%.
Robinhood Chain is presented as another striking example. It was initially positioned as a public chain for tokenized real-world assets, but the article cites Blockworks data showing that meme coins accounted for more than half of spot trading volume after launch. In other words, a chain pitched around RWA found its growth engine in meme trading.
Fomo is also highlighted. Built by former dYdX employees, it lowers interaction friction, includes a social feed, and supports Apple Pay. The article says average daily revenue has surpassed $400,000, with growth accelerating sharply in the second half of 2026 after the platform started in June 2025.
The report argues that falling DeFi yields and lower entry barriers have helped meme coins become a relatively independent sector with less sensitivity to the broader market. In the past, traders had to search for opportunities on X and Telegram, use tools such as Dexscreener, connect a wallet, and trade on a DEX. Now meme culture spreads on TikTok, and apps let users buy tokens directly through Apple Pay.

Prediction markets expanded rapidly
Prediction markets are described as one of the fastest-growing segments of the past year. The article says trading volume surged 3,032% year over year and rose 320% during the year, with growth still intact. Platforms such as Kalshi and Polymarket helped take the market from almost negligible scale in 2024 to the $50 billion range by mid-2026.
Valuations climbed with it. Kalshi was valued at $750,000 in 2019. After several fundraising rounds, its valuation reached $22 billion in May 2026, and its next round is targeting $40 billion. Polymarket’s valuation rose from $18.58 million in 2020 to $15 billion, with the next financing target above $20 billion.
The article is careful, though, not to overstate the utility case. Information discovery and hedging are often cited when the sector is discussed, but it says those real-world use cases remain limited for now. Kalshi’s volume mostly comes from sports and crypto. Polymarket covers more categories, yet sports, crypto assets, and politics still dominate activity.
It also compares weather contracts with sports contracts. Weather positions tend to build earlier, which suggests a hedging motive. Sports positions often pile in close to the event date, which looks much more speculative. Another data point in the piece says 56.1% of wallet addresses on Polymarket have never interacted with a DEX. That does not prove they are all completely new to crypto, but it does suggest prediction markets have become a first blockchain product for many users.
Perpetual DEXs held up better than spot venues
Decentralized perpetual futures exchanges did not match the explosive growth seen in meme coins or prediction markets, but the article says they showed unusual resilience in a weak market. Since 2025, perpetual DEX trading volume has remained above spot DEX volume, and the decline in perpetual activity has been much smaller than in spot trading. That, in the report’s view, shows speculative demand for derivatives is stronger than demand for spot exposure.
Two drivers are cited. One is a steady stream of new protocols. After Hyperliquid’s success, Lighter, Aster, Variational, Grvt, and edgeX all launched. Jito, Jupiter, and Ondo Finance, which were not originally focused on perps, also added perpetual products. A second driver is the rise of RWA perps. Contract markets once centered mainly on BTC and ETH, but platforms are now listing commodities and US equities as geopolitical tension and AI-related equity moves attract interest. The article points to SK Hynix perpetuals on Hyperliquid as an example, noting that ordinary investors outside South Korea may find the stock itself difficult to access, while the perpetual contract saw strong trading volume.
The report closes the loop by noting that perpetual futures as a concept began with BitMEX. BitMEX itself is now in decline and close to shutting down, it says, yet the category keeps expanding. Coinbase, Robinhood, Kalshi, the Singapore Exchange, and CME are all moving into related products.

The real-economy end: stablecoins, RWAs, and vaults kept growing
The article stresses that not all growth is speculative. The other side of the barbell includes businesses that are less flashy but more stable: stablecoins, tokenized real-world assets, and vault products. These segments, it says, kept growing even as token prices and on-chain TVL weakened more broadly.
Venture funding tied to native on-chain projects has clearly slowed in both count and size, according to the report. But blockchain businesses connected to the real economy are raising larger rounds. It cites Rain’s $250 million Series C, Airwallex’s $320 million Series H, Gauntlet’s $125 million raise, and OpenFX’s $94 million financing as evidence that this group has established a more independent product-market fit less tied to crypto cycles.
Stablecoin supply flattened, but payment usage accelerated
One of the more interesting points in the piece is that stablecoin supply did not surge over the past year. Total supply grew only about 11%, and after October 2025 it was largely flat. With Treasury tokenization and private credit tokenization expanding quickly, stablecoin supply growth moderated.
But the article says that should not be read as stagnation. In a falling market, holding the line on supply is already meaningful. More important, payment use cases have accelerated. Monthly payment volume on crypto payment card products such as RedotPay, KAST, EtherFi, and Plasma One rose from $438.1 million in July 2025 to nearly $1.32 billion in July 2026, almost tripling.
The report says stablecoins began as an intermediate asset for crypto trading but are moving deeper into real payment flows and are likely to become the main settlement currency for tokenized real-world assets as that ecosystem matures.
RWA stayed on an expansion path
RWA is described as one of the defining growth stories of 2025 and 2026. The market wants to use blockchains to modernize aging financial infrastructure and put a wider range of real-world assets on-chain. Early products focused on US Treasuries and money market funds because they were relatively simple to structure. The market then moved into private credit, and more recently into stocks and equity-like instruments.
The article argues that the value logic of these assets is distinct from crypto price action. That independence, along with efficiency gains and lower access barriers, gives the segment room to grow even when broader crypto markets are weak.

Vaults recovered close to prior highs
Vaults do not connect to real assets as directly as RWAs do, but the article describes them as a new generation of on-chain asset management modules. They lend capital into markets that accept RWA as collateral, which gives them an indirect link to the real economy.
As of August 28, Bitcoin was down 35% from its high, while selected vault TVL was only 4% below its historical peak. The article takes that gap as a sign that vaults are moving on a more independent track. The first phase of RWA focused on bringing assets on-chain. The next phase, it says, is about using those assets, and that should support demand for vault products as RWA-backed borrowing expands.
Why crypto companies are starting to look alike
The report ends by pointing to a business pattern now visible across the industry. Crypto companies with very different origins and original business models are building many of the same products and competing in the same areas. Platforms are adding perpetual futures, prediction markets, meme coin trading, stablecoins, RWA trading, and vault products.
The logic, as the article lays it out, is simple. Only a small number of sectors can both resist broader market weakness and generate real revenue. That is why, even with a near-term market rebound, many crypto firms are still crowding into the same countercyclical segments.
At the same time, the report does not say every native crypto project is finished. Some have survived and still appear to have found product-market fit. It cites EigenLayer, which still attracts substantial ETH restaking, and MapleStory Universe, which it says continues to post strong data despite skepticism around blockchain gaming.
Its final takeaway is that crypto now operates in a barbell structure. Looked at negatively, only a narrow set of sectors still offers real growth. Looked at another way, some crypto businesses have finally matured enough to find durable business models.
