


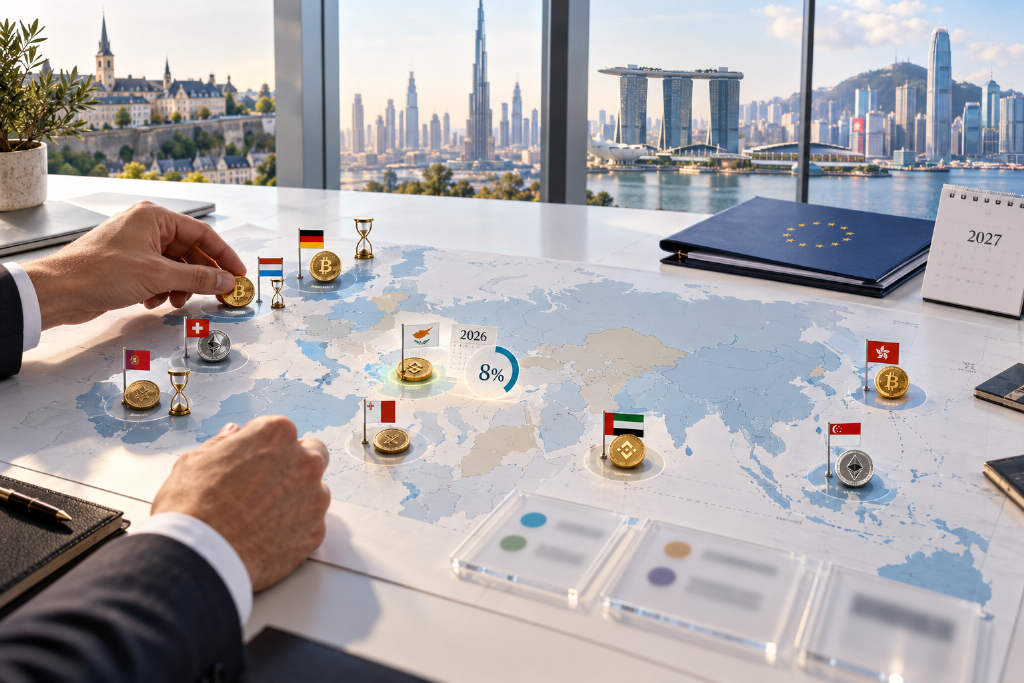
The global map for crypto taxation is being redrawn. A common claim says more than 30 countries have 0% crypto tax. The article says that statement is not entirely wrong, but it is easy to misunderstand.
A jurisdiction with no capital gains tax does not automatically make a person’s crypto profits tax-free. What usually matters is classification: are the gains treated as investment returns, professional trading income, employment or other income, or business profits? Singapore and Hong Kong may not tax capital gains in substance, yet profits can still be taxed if they are treated as business income. Switzerland generally exempts private investment gains, but wealth tax still applies. Germany, Portugal, and Luxembourg rely heavily on holding periods. Cyprus, which still appears on many older zero-tax lists, changed course: from 2026, qualifying profits from crypto disposals are taxed at 8%.
The key word is classification. The real question is not whether a destination sounds low-tax on paper, but what exactly is exempt, what is not, and where the phrase “0% crypto tax” stops holding up.
Switzerland: capital gains relief does not remove wealth tax
Switzerland’s appeal is straightforward. Assets held as private wealth generally benefit from an income tax exemption on capital gains, and privately held crypto assets are usually included. Unlike Germany, Switzerland does not impose a uniform one-year holding requirement.
But the article points to two conditions. First, the activity must remain private investment. If it is classified as professional trading or self-employment, the gains can become taxable. Second, crypto holdings are included in taxable wealth, and the amount due depends on cantonal and local tax bands.
That makes Switzerland different from places that tax only realized gains. An investor may sell nothing during the year and still owe wealth tax because of the holdings themselves. The more accurate description, the article argues, is that private capital gains are generally exempt, not that “crypto is untaxed.”
Cyprus: older zero-tax lists are out of date
Cyprus stands out because the rules changed.
From Jan. 1, 2026, qualifying profits from crypto disposals are subject to a flat 8% income tax. The scope includes selling crypto, crypto-to-crypto exchanges, spending crypto, and gifts that generate gains. Both capital gains and trading gains are covered.
Loss treatment is also limited. Crypto losses generally can only offset crypto gains of the same person in the same tax year and cannot be carried forward under this special regime. Crypto acquired through mining is not covered by the same special treatment.
For that reason, treating Cyprus in 2026 as a zero-tax destination for ordinary crypto disposals relies on outdated guidance. The article also says the island’s non-domicile regime does not change that conclusion: a benefit for one category of income does not mean all income of a resident is exempt. Cyprus now belongs in a low-tax discussion, not a zero-tax one.
Portugal: long-term holders still have the edge
Portugal’s rules are more specific than its old reputation as a “crypto haven.”
For qualifying crypto assets that are not securities, gains are not taxed if the assets are disposed of after being held for at least 365 days. Gains that do not qualify for the exemption are generally taxed at 28%, although aggregation rules and other exceptions can change the result.
This structure favors patient investors more than short-term traders. Even so, the article says the one-year rule is not a complete answer to every crypto tax question in Portugal. The exemption applies to a defined category of disposal gains. It does not mean every token, every business activity, or every type of crypto income receives the same treatment. Buying selected assets and holding them for the long term may fit the exemption well; more complex on-chain portfolios and frequent activity require a closer look.
Monaco: no personal income tax for most residents, but residence must be real
Monaco does not levy personal income tax on most residents. French nationals are the main exception because of the France-Monaco tax treaty.
For people who qualify, Monaco is one of the clearest European jurisdictions for tax-free personal investment gains. The important condition is that the person must genuinely reside in the principality. Monaco’s own rules do not determine how another country views that person’s tax residence. A Monaco address on its own does not prove that the former home country has stopped treating the person as a tax resident.
The tax advantage is simple. For most qualifying residents, there is no personal income tax. The difficult part is proving that the rule truly applies and that the evidence can withstand scrutiny.
Luxembourg: the six-month rule is often overlooked
Luxembourg is not always prominent in crypto relocation discussions, but the article says its private investor rules deserve attention.
If an individual disposes of crypto within six months of acquisition and total speculative profits for the year reach at least EUR 500, the gains are generally taxed as speculative income. Outside that window, genuine private investment gains are generally not taxed.
Its holding threshold is shorter than the one used in Germany or Portugal. Still, this is an investor rule, not a blanket exemption for crypto businesses. When short-term gains are taxable, they are taxed at ordinary personal income tax rates, not under a special low crypto tax schedule. Luxembourg’s appeal is narrow but clear: for private investors, holding longer than six months may produce a better result.
Malta: first identify the token, then the context
Malta is often reduced to a simple line that long-term crypto gains are tax-free. The article says the real framework is more detailed.
Tax guidance distinguishes among coins, financial tokens, utility tokens, and hybrid assets. Coins held as capital assets fall outside capital gains tax. But if a business exchanges coins, or sells tokens held as trading stock, the profit is treated as ordinary income.
Financial tokens can lead to different outcomes. If a token is treated as a security under the relevant rules, a disposal may fall within capital gains tax. The article also says there is no universal rule under which every crypto asset becomes exempt after six months or one year. Purpose and context matter, not just time. Malta may be favorable for genuine investment holdings, but “Malta = 0% crypto tax” leaves out too much to stand as a conclusion.
Germany: the one-year exemption is strong, but it is not the whole story
Under Germany’s current framework, crypto assets held privately are generally tax-free when sold after more than one year, regardless of the size of the gain.
If the asset is sold, exchanged, or spent within that one-year window, however, the gain may be taxable under the private disposal rules. Those rules also include an annual EUR 1,000 tax-free threshold. The article stresses that this is a threshold, not a deduction. Once the threshold is reached, the full relevant gain may become taxable.
Two distinctions matter. First, a crypto-to-crypto swap can itself be a disposal event. Conversion into euros is not required. Second, crypto held by a business is subject to different rules from crypto held privately.
At the time of writing, the one-year exemption remained the current rule. The article says reform proposals had already been reported, so anyone planning a move or a disposal strategy should separate current law from proposed changes. For patient private investors, Germany may be more favorable than its high-tax reputation suggests. For frequent traders, the outcome may be very different. The article also says the risk of this 0% treatment being changed is not low.
United Arab Emirates: personal investing and business activity are separate tracks
For people seeking zero tax on qualifying personal crypto investment gains, the United Arab Emirates is presented as one of the clearest non-European options.
Qualifying personal investment income is excluded from the business activities that can bring an individual into the corporate tax system. But that does not mean every crypto-related activity in the UAE automatically receives a zero rate.
If an individual carries on a business in the UAE and annual turnover exceeds AED 1 million, that person may fall within the corporate tax regime. Qualifying personal investment income is not counted toward that threshold. Under the standard corporate tax system, taxable income up to AED 375,000 is taxed at 0%, and income above that level is taxed at 9%.
The article notes that these are profit thresholds, which are different from the AED 1 million turnover test for individuals. The real dividing line is whether a person is managing personal investments or conducting a taxable business, not whether the asset involved is crypto.
Singapore and Hong Kong: no capital gains tax does not mean all trading profits are exempt
Singapore does not tax capital gains in substance. Profits from individuals buying and selling financial instruments, including digital tokens, are generally treated as personal investment gains. But if a business trades tokens in the ordinary course of business, those trading profits are taxable.
When authorities distinguish capital gains from taxable trading income, they look at factors such as investment purpose, trading frequency, and holding period. So the article rejects any simple rule that all crypto profits generated in Singapore are tax-free. Singapore can appear on a list of places with no capital gains tax, but not on a list where all crypto income is untaxed.
Hong Kong follows a similar split. Capital gains are outside profits tax, so crypto held as a long-term investment may qualify. But Hong Kong-sourced crypto business profits may be taxable. Source depends on the profit-generating operations and where those activities take place.
That makes “Hong Kong has no capital gains tax” a useful starting point, but “all crypto trading strategies are tax-free” an unreliable conclusion. The article also notes that Hong Kong is a separate tax jurisdiction, not a sovereign state.
So where is crypto really at 0%? The article gives three answers
The piece breaks the answer into three groups.
- First, jurisdictions that do not generally impose personal capital gains tax. The UAE generally keeps qualifying personal investment income outside the tax net. Singapore does not tax capital gains in substance. Hong Kong excludes capital gains from profits tax. Monaco does not levy personal income tax on most qualifying residents who genuinely reside there, while French nationals are treated separately. The article adds that Hong Kong is a separate tax jurisdiction and that the list covers only the destinations discussed, not a complete global ranking.
- Second, jurisdictions that exempt qualifying private investment. Switzerland generally exempts private investment gains, though wealth tax still applies. Malta excludes qualifying coins from capital gains tax, while trading income and some token categories are treated differently.
- Third, jurisdictions where 0% treatment depends on a holding period. In Luxembourg, private investment gains are generally exempt after more than six months. In Germany, privately held crypto is generally exempt after more than one year under current rules. In Portugal, qualifying crypto assets can be exempt after at least 365 days if the relevant conditions are met.
Cyprus does not belong in those zero-tax groups. Under its 2026 regime, the tax rate for covered disposals is 8%.
DeFi makes comparisons harder
Once a portfolio goes beyond a simple buy-hold-sell pattern, cross-country comparisons become much less direct.
A capital gains exemption does not automatically answer how mining, token rewards, investment returns, or business trading are treated. For active crypto users, the article says at least four questions need to be separated:
- How are token disposals treated?
- How are tokens received as income or rewards treated?
- Could the activity amount to a business?
- Do the assets actually held fall within the exemption being relied on?
A favorable answer to the first question does not solve the other three. Someone who held BTC for two years and someone who earns tokens, rotates positions, and trades derivatives may live in the same country and still need completely different tax analysis.
Low tax does not mean low transparency
The article closes with a practical point. A low headline rate matters only if the rules actually apply to the person involved. The first step is to determine which jurisdiction has taxing rights, not to assume that changing address solves the issue.
Low tax also does not mean low transparency. Under the EU’s DAC8 framework, crypto reporting rules apply to reportable activity from 2026, and first reports will be made in 2027 under each country’s implementation rules. Tax exemption and reporting obligations are not the same thing.
So the more useful question is not simply “where is crypto taxed at 0%?” It is whether a person’s actual portfolio, trading activity, and income profile can qualify for that treatment in a given jurisdiction, and whether the basis for that treatment can be documented and proven.
