
Goldman Sachs selected 10 energy and power stocks in a report dated Oct. 8, 2026, assigning Buy ratings to all of them and estimating an average total return potential of 27% based on closing prices from Oct. 7, 2026.
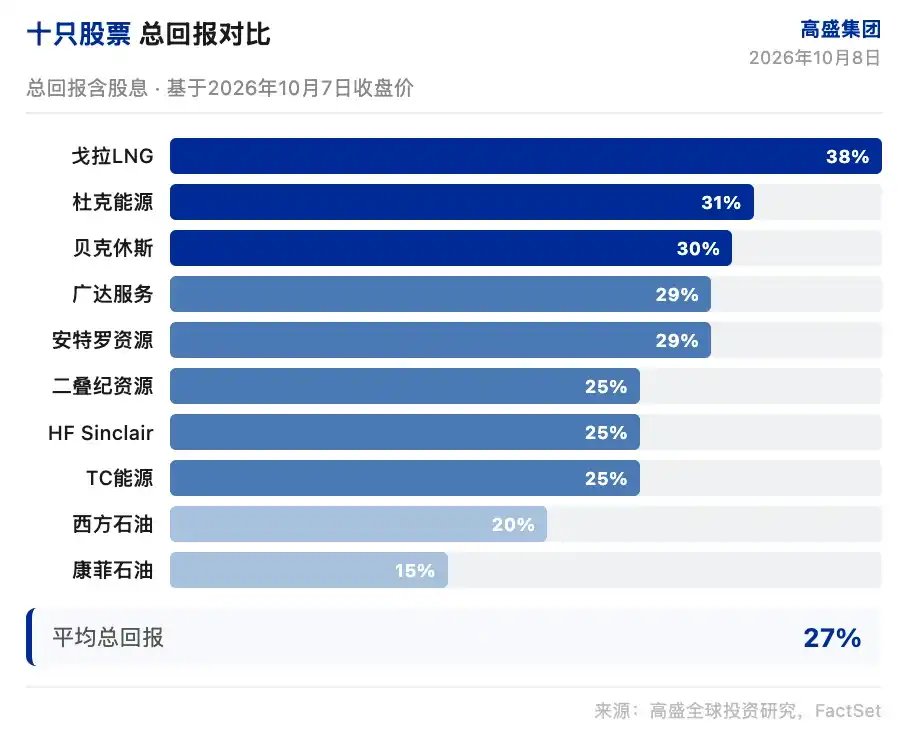
The report covers four themes: oil and gas exploration and production, power and LNG, refining, and natural gas upstream and midstream. Goldman said its central call is that these stocks offer attractive risk-reward at current levels, with a dense set of fourth-quarter catalysts ahead.
Oil and gas E&P names on the list
ConocoPhillips carries a $146 price target and 15% total return potential. Goldman said free cash flow is approaching an inflection point as four major growth projects — NFE, NFS, Port Arthur, and Willow — move into production. The company also plans to cut $1 billion in costs. Under a long-term Brent assumption of $75, Goldman expects annual compound growth in free cash flow per share of 20% to 25%.
Goldman said ConocoPhillips’ capital return framework targets returning 45% of operating cash flow to shareholders through the cycle. It expects the payout ratio to approach 50% in the second half of 2026 to make up for weaker performance in the first half. Near-term milestones include Willow’s winter construction season and summer module sealift, while Goldman expects first oil in early 2027.
Occidental Petroleum has a $69 target and 20% total return potential. Goldman noted that it upgraded the stock to Buy from Hold on Aug. 30 and added it to its Americas Conviction List. Goldman estimates average free cash flow yield of 13% for 2027 to 2028, above the 11% average for large-cap peers. The company is targeting $4 billion in incremental sustainable free cash flow by 2030.
Goldman said Occidental’s deleveraging path is visible, with its $10 billion core debt target likely to be reached in early 2027. It also pointed to more than 4 billion barrels of oil equivalent in resource opportunity tied to enhanced oil recovery technology.
Permian Resources has a $27 target and 25% total return potential. Goldman expects free cash flow per share to grow at roughly a 20% annual compound rate from 2025 to 2028. The company has completed $1.05 billion of bolt-on acquisitions year to date. Goldman also projects an average free cash flow yield of 16% for 2027 to 2028, above the 13% average for E&P peers.
According to the report, improving Waha gas pricing and continued ground game execution provide additional upside for Permian Resources.
Power and LNG names tied to grid buildout and data centers
Quanta Services has a $902 target and 29% total return potential. Goldman said the company is a key beneficiary of grid and data center construction, with power accounting for about 80% of revenue. Through the acquisitions of Cupertino, Dynamic Systems, and Tri-City, Quanta has built capabilities across the full data center construction value chain.
Goldman expects Quanta Services to deliver revenue CAGR of about 15% through 2030. It said 765-kilovolt and other large transmission projects should be major drivers over the next several years, and estimated that the company will participate in multiple large projects beyond baseline grid EPC work.
Duke Energy has a $147 target and 31% total return potential. Goldman said the company is relatively insulated from election risk because there is no gubernatorial election in North Carolina. Duke’s data center pipeline stands at 15.4 GW, including 7.8 GW under signed ESAs and 5.2 GW under construction.
Goldman expects Duke’s 2026 FFO-to-debt ratio to reach about 14.5%, against a long-term target of 15%. It said management could raise earnings guidance from 5% to 7% on the fourth-quarter earnings call. Goldman’s 2027 EPS estimate implies a valuation of about 16x earnings, in line with the average across its coverage.
Baker Hughes has a $71 target and 30% total return potential. Goldman said the integration with Chart Industries creates growth opportunities, with strong order momentum in IET and durable profitability in OFSE. It expects Baker Hughes’ IET segment to reach an EBITDA margin of about 25% by 2031, with additional margin expansion available in the Chart business.
Goldman added that OFSE is increasingly tilted toward production-oriented oilfield services, which it views as a more defensive earnings profile.
Golar LNG has a $67 target and 38% total return potential, the highest in the group. Goldman said the company has a clear path to about $1.2 billion in run-rate EBITDA by 2030, versus about $260 million in 2025. Its fourth FLNG vessel has already reached FID, and Goldman expects a commercial contract announcement in the near term.
Each MKII vessel can add about $400 million in run-rate EBITDA, according to the report. Goldman also said the company’s strategic review could include a sale, something management has already mentioned. Contract commodity price exposure tied to its Argentina assets was cited as another possible source of value.
Refining: Goldman sees room for earnings estimate revisions
HF Sinclair has a $142 target and 25% total return potential. Goldman said that even after the refining sector’s year-to-date strength, consensus earnings estimates still have room to move higher. The firm pointed to HF Sinclair’s exposure to niche refining markets in the Rockies and Mid-Continent, steady non-refining earnings contribution, and a strong balance sheet.
Goldman said crude slate flexibility and jet fuel flexibility projects support margin realization. It expects adjusted EPS for 2026 through 2028 to come in above FactSet consensus, by 14% in 2026, 10% in 2027, and 5% in 2028.
The bank said tighter global refining fundamentals and capital discipline across the industry support upward revisions to earnings expectations.
Natural gas upstream and midstream
TC Energy has a $71 target and 25% total return potential. Goldman said the stock looks attractive after a recent pullback. The company is expected to announce more U.S. natural gas pipeline projects over the next several quarters, while its Canadian gas business has additional growth projects. The Ontario nuclear expansion project adds long-term growth visibility.
Goldman expects TC Energy to post EBITDA CAGR of about 6% from 2025 to 2032, roughly 1 percentage point above FactSet consensus. It also estimates the company has C$6 billion to C$11 billion of remaining capital spending capacity for 2026 to 2030 that could be formally approved in the coming months.
Antero Resources has a $46 target and 29% total return potential. Goldman said the company aims to reduce cash costs to $2.00/Mcf by 2028 from $2.70/Mcf in 2025. The HG Energy transaction is expected to bring cost synergies, and the company plans to unwind expensive firm transport agreements, driving $300 million in margin improvement.
Goldman expects average free cash flow yield of 14% for Antero in 2027 to 2028, above the 9% average for Appalachian peers. It added that these improvements could rise to $600 million to $700 million after 2028 as more agreements are rolled off.
Goldman points to a busy Q4 catalyst calendar
Across the 10 names, Goldman’s average total return estimate is 27%, spanning oil and gas, power, refining, and natural gas upstream and midstream. The fourth-quarter catalysts highlighted in the report include progress at ConocoPhillips’ Willow project, a possible guidance increase from Duke Energy, and a contract announcement for Golar LNG’s fourth vessel.
The MarsBit piece said the article was a summary and interpretation by Chaoxiang Research of a third-party brokerage report from Goldman Sachs dated Oct. 8, 2026, combined with public market information. It added that the ratings, target prices, earnings forecasts, and related judgments cited in the article are the views of Goldman analysts and represent only the position of that institution, not Chaoxiang Research, and do not constitute investment advice.
The article also said market decisions should be made independently and that the report should not be used as the basis for buying or selling any security.