
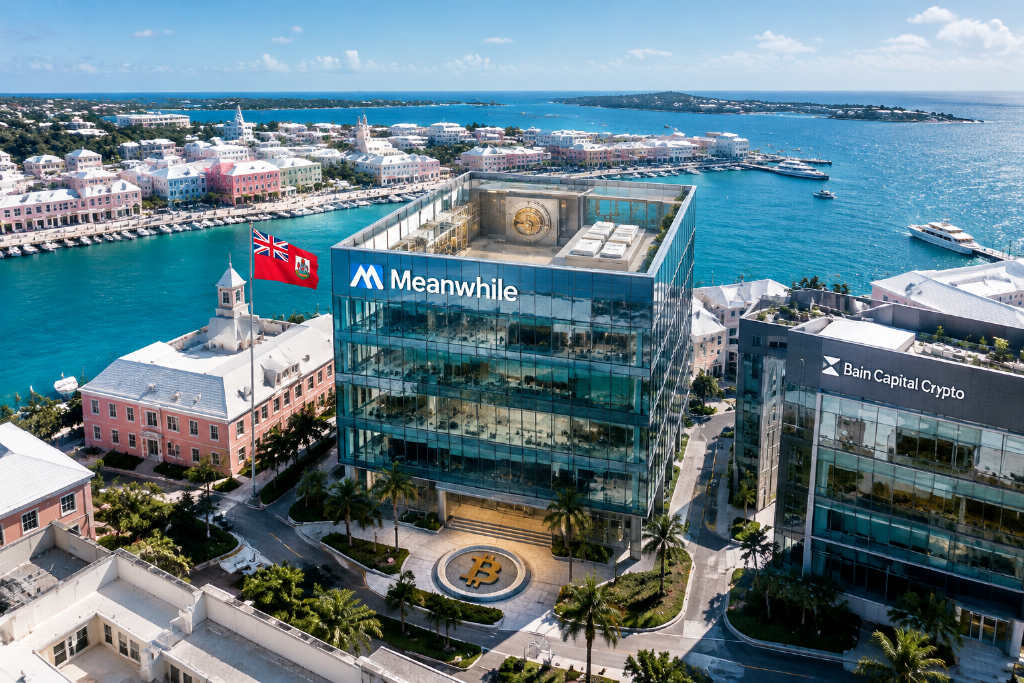
Bitcoin life insurance company Meanwhile said on Oct. 8 that it has raised $37.5 million in a new funding round led by Bain Capital Crypto, with existing investors Haun Ventures, Framework Ventures, Pantera Capital, Apollo, Northwestern Mutual Future Ventures and Morgan Creek Digital also participating. The company said its total funding has now surpassed $180 million. It had previously announced financings of $40 million in April 2025 and $82 million in October 2025, and early backers include OpenAI CEO Sam Altman.

Unlike most crypto financial companies that center their businesses on trading, payments and lending, Meanwhile has chosen life insurance. Founded in 2022, the company is trying to address a specific question: as more families hold Bitcoin as a long-term asset, can insurance be used for wealth accumulation, risk protection and intergenerational transfer?
A life insurer built around Bitcoin as the unit of account
Meanwhile’s core product is a life insurance structure denominated entirely in Bitcoin. Policyholders pay premiums in BTC, policy cash value builds in BTC, death benefits are paid in BTC, and policy value can also be used to borrow BTC.
The company was co-founded by Zac Townsend and Max Gasner. Its insurance carrier, Meanwhile Insurance Bitcoin (Bermuda) Limited, is registered in Bermuda. Meanwhile launched its Bitcoin life insurance product in 2023 and, in July 2024, received the first Class IILT innovative life insurance license issued by the Bermuda Monetary Authority after about two years of regulatory sandbox testing.
Compared with conventional dollar-based life insurance, the main difference is that Meanwhile uses BTC at the same time as the premium denomination, the insurance liability denomination and the reserve asset denomination.
Customers pay premiums in BTC, while policy cash value, policy loans and death benefits are all denominated in BTC. By using Bitcoin as both the policy unit of account and the reserve asset, Meanwhile is trying to offer insurance and wealth management services outside the fiat-based system for long-term Bitcoin holders.
Two products, with 1-Pay at the center of international expansion
Meanwhile currently offers two main products. BTC Life 10-Pay is designed for U.S. taxpayers and uses a 10-year premium payment structure, with policyholders paying BTC premiums over time in exchange for whole life coverage. BTC Life 1-Pay, launched in early 2026, is aimed mainly at high-net-worth clients outside the United States. Under that product, customers make a one-time BTC premium payment and receive lifetime coverage denominated in BTC.
Among the two, 1-Pay is the company’s current priority for international expansion.
In one illustrative case disclosed in product materials, a 45-year-old non-smoking man who pays a single premium of 10 BTC would receive a guaranteed death benefit of 15.8 BTC. Coverage takes effect immediately after the policy is issued, no further premium payments are required, and beneficiaries can receive payout in BTC if the contractual conditions are met.
The policy also accumulates cash value over time. In the same example, the initial surrender value is about 8.5 BTC, rising to about 10.2 BTC in year five and reaching about 12.3 BTC by the time the insured turns 70. Meanwhile noted that policy cash value is not the same as the death benefit. The former is the value the holder can access while alive through surrender or financing, while the latter is the contractual payout upon death. The company also said those figures are examples under specific underwriting conditions and do not mean every customer will receive the same outcome.

Policy loans and ownership structure
Another key feature of 1-Pay is policy lending. After a policy has been in force for one year, the holder can apply for a BTC loan of up to 90% of the policy’s surrender value. The disclosed annual interest rate is 3%.
These loans do not have a fixed repayment schedule, and there is no margin call triggered by swings in the market price of BTC. If the holder does not repay the loan, accumulated principal and interest are deducted from the final death benefit.
That allows a holder to access part of the policy’s BTC liquidity without surrendering the contract, while keeping the remaining insurance protection in place. Unlike standard crypto-collateralized lending, the collateral base here is the policy value created by the insurance contract rather than external crypto collateral that can change rapidly with market prices.
Meanwhile also said 1-Pay policies can be owned by individuals, trusts or companies, allowing them to be combined with family trusts, estate planning and corporate wealth management structures.
How the model makes money and where the risks sit
According to the company’s 2025 audited financial statements, Meanwhile had total assets of 1,183.11 BTC at the end of that year, up about 437% year over year. That included 548.29 BTC in digital asset investments and 403.19 BTC in collateralized loan assets. The company posted net profit of 20.89 BTC for the year, marking its second straight profitable year.
The Bitcoin-based insurance structure also carries its own risks. For policyholders, what is protected is the amount of BTC, not its dollar value. A policy that takes in a 10 BTC premium and promises a 15.8 BTC death benefit would still lose 80% of its dollar value if Bitcoin were to fall 80%, even if the insurer paid in full.
For the insurer, having both assets and liabilities denominated in BTC reduces currency mismatch risk. But because part of the reserves generate yield through institutional lending, the company still faces borrower default risk, insufficient collateral risk and liquidity risk.
That leaves Meanwhile with a long-term challenge that goes beyond customer acquisition. It also has to maintain stable investment returns and insurance solvency through different market cycles.
Founders with fintech and insurance backgrounds
Meanwhile’s founding team combines experience in fintech, banking infrastructure and traditional insurance.
Co-founder and CEO Zac Townsend previously founded banking-as-a-service company Standard Treasury, which was backed by Y Combinator and acquired by Silicon Valley Bank in 2015. He later served as California’s first chief data officer and also worked in McKinsey’s financial services practice, giving him experience across financial infrastructure, fintech and regulation.

Co-founder Max Gasner serves as CTO and leads the company’s technology direction. The two began discussing the creation of a financial institution for the Bitcoin economy in late 2021 and launched Meanwhile in 2022. Townsend has said the team initially considered crypto financial businesses such as banking, payments and exchanges, but concluded that insurance, a traditional financial category, still lacked a mature Bitcoin-native product.
The management team also includes Chief Insurance Officer Jim Cristallo, Chief Financial Officer Tia Beckmann, Chief Risk Officer Carsten Ragborg and Michael Grob, who oversees international distribution. Together they cover insurance operations, finance, risk control and sales channels.
By its team structure, Meanwhile is not a typical crypto protocol startup. It is a licensed financial institution run jointly by fintech founders and insurance professionals. Its competitive position depends not only on Bitcoin-related product design, but also on long-duration liability management, regulatory compliance and institutional distribution.
More than $180 million raised and a push into global wealth channels
Meanwhile has completed several rounds of financing since it was founded.
In 2023, the company raised about $19 million in early funding from investors including Sam Altman, Lachy Groom and Google-backed venture firm Gradient Ventures. In April 2025, it closed a $40 million Series A. In October of the same year, it raised another $82 million in Series B financing, led or co-led by Bain Capital Crypto, Haun Ventures and others, with participation from firms with traditional finance backgrounds such as Apollo and Northwestern Mutual Future Ventures.
Beyond crypto-native funds, Meanwhile has also drawn support from alternative asset manager Apollo and the investment arm of U.S. mutual insurer Northwestern Mutual. On the business side, the company is extending its target market from individual Bitcoin holders to high-net-worth families globally.
Meanwhile said that since launching operations, it has built relationships with 15 insurance brokerage firms serving wealthy families. Its distribution footprint covers wealth management markets including Singapore, Hong Kong, the UAE and Switzerland. Partners include Lioner, an insurance and family office services firm with offices in Hong Kong, Singapore and Zurich, and Apeiron Group, an insurance platform focused on high-net-worth clients. The company also said long-term insurance net underwriting revenue in 2026 is expected to reach more than double the 2025 level.
The rise of this type of company points to a shift in crypto financial demand. As Bitcoin becomes part of long-term portfolios for high-net-worth families, new room is opening for services tied to inheritance, insurance protection, long-term financing and family wealth planning.
Still, using Bitcoin as the unit of account may reduce currency mismatch between insurance assets and liabilities, but it does not remove credit risk, liquidity risk or long-term solvency risk. Meanwhile currently operates under a Bermuda regulatory license, its products are available only to eligible clients, and they are not offered in every jurisdiction. Whether this Bitcoin-native life insurance model can scale will depend on its ability to build stable actuarial, investment and solvency systems across broader markets.
