


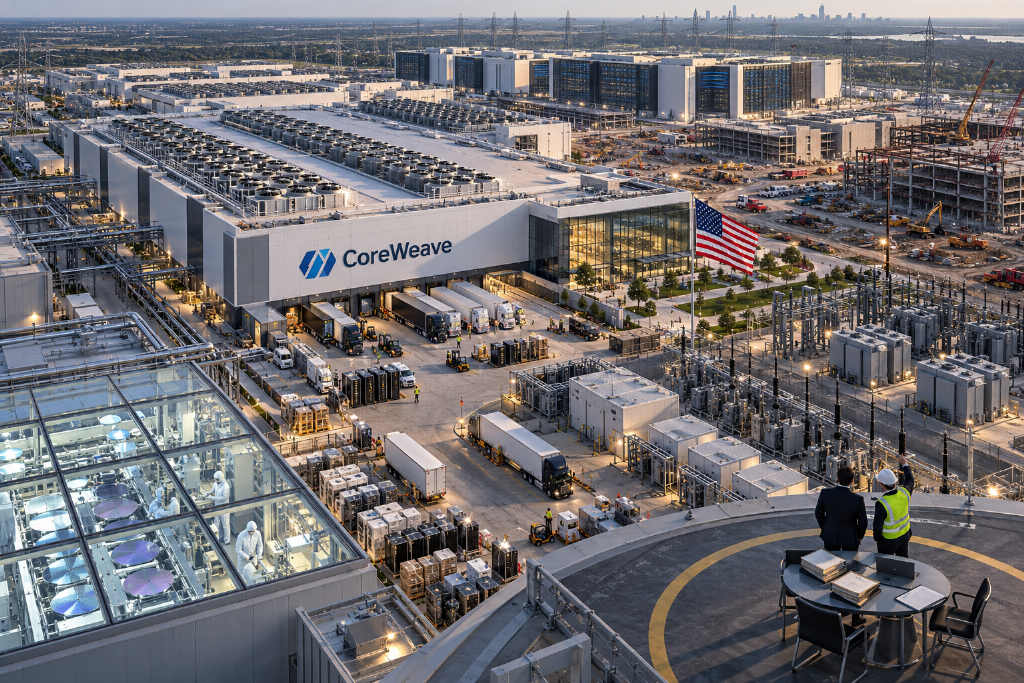
Moody’s Ratings said on Oct. 27, Taipei time, that heavy borrowing to fund artificial intelligence infrastructure is pushing private credit beyond traditional corporate lending. At the same time, a wave of maturities in the coming years could make refinancing more difficult for weaker borrowers.
AI financing now reaches across the supply chain
Moody’s said demand for AI financing is no longer limited to building data centers. It now covers land, power, semiconductors, and computing hardware including graphics processing units, or GPUs, and tensor processing units, or TPUs. In practice, that means the full supply chain could become a target for private credit.
The agency expects combined capital expenditures by the five largest U.S. hyperscalers and AI cloud company CoreWeave to approach $1 trillion by 2027. Funding sources include not only operating cash flow, but also debt, joint ventures, and special purpose vehicles, or SPVs.
Moody’s said these structures often ring-fence assets tied to a single project, making it easier for private credit to move into technology infrastructure. The market has already seen signs of stress among highly leveraged AI borrowers. The report cited recent volatility in debt tied to CoreWeave, highlighting investor concern over borrowers carrying elevated leverage.
Maturity wall from 2027 to 2029 could test weaker borrowers
Moody’s warned that loan maturities due from 2027 through 2029 will test the refinancing capacity of weaker borrowers in a higher-rate environment. Reuters had earlier reported that the peak maturity period for U.S. business development company, or BDC, loans falls in 2028 and 2029, a timeline that largely overlaps with Moody’s view.
Among the 607 borrowers tracked by Moody’s, about 17% use payment-in-kind, or PIK, interest. That structure allows borrowers to avoid paying cash interest for the time being by adding the interest to principal instead. It can ease pressure in the short term, but it also increases debt over time.
Moody’s also referred to its Oct. 14 U.S. private credit risk assessment report, which said that for the same credit estimate sample, a broader stress indicator rises above simple default statistics when PIK amendments, maturity extensions, and similar stress events are included.
Circular financing also drew a warning
Beyond maturities and PIK structures, Moody’s flagged the risk of “circular financing.” It said technology companies, chipmakers, and AI developers may invest in, lend to, and purchase from one another. If the economy weakens, those exposures could deteriorate at the same time.
What it could mean for crypto markets
At a macro level, if private credit turns more cautious because refinancing becomes harder, highly volatile crypto assets are often among the first positions to be cut. If more AI-themed capital remains tied up in data center and chip debt, the marginal flow into higher-risk tokens could also thin out.
Mechanically, PIK structures defer interest by adding it to principal, which resembles the way some crypto lending arrangements rely on extensions or delayed liquidation. Short-term pressure is reduced, but balance-sheet debt keeps growing. Stablecoin and decentralized finance, or DeFi, markets often discuss on-chain private credit or real-world asset, or RWA, credit. If traditional markets become more demanding on maturities and cash interest payments, similar on-chain products could face tighter expectations on pricing and transparency.
Moody’s did not frame this as a prediction of a linked market sell-off. The point was narrower: once rating agencies place AI infrastructure and private credit on the same stress map, the market is likely to focus on which borrowers can withstand the next refinancing test.