
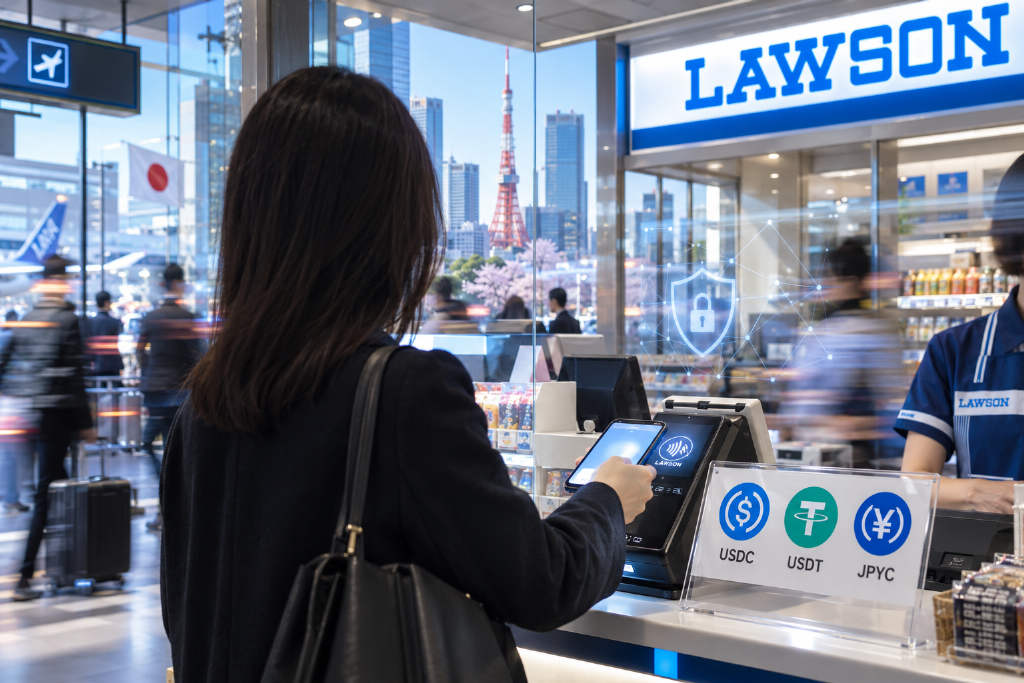
Netstars’ stablecoin payment buildout in Japan moved from a single-token, single-chain pilot to a multi-token, multi-chain setup in seven months, according to a report by Jason Kuo of the Digital Asset Development Research Center (DADRC), published by ABMedia. The report says the most important takeaway is not the technical integration itself, but the compliance burden that grows each time an operator adds another chain or wallet.
DADRC said it visited Netstars’ headquarters in Japan in April with a delegation of Taiwan banking industry representatives. Around that visit, Netstars introduced StarPay-X as it prepared to expand its Haneda Airport USDC pilot into a broader multi-chain model. By the time DADRC looked back six months later, stablecoin acceptance had already moved from two airport stores to a convenience store checkout.
Japan’s framework separated roles before the rollout began
The report says Netstars was able to expand three times in seven months because Japan’s Financial Services Agency had already drawn a clear line around who could handle stablecoins. Under the revised Payment Services Act, which took effect in June 2023, stablecoins pegged to fiat and redeemable at face value are classified as “electronic payment instruments.” Issuers are limited to banks, fund transfer service providers, and trust companies. Sales, exchange, and custody must be handled by registered electronic payment instrument service providers, which are subject to customer verification, reporting duties under Japan’s anti-crime proceeds law, and Travel Rule requirements.
The article distinguishes between two token paths. USDC is a foreign-issued stablecoin and only started circulating in Japan after SBI VC Trade obtained registration in March 2025. Operators handling foreign stablecoins are also subject to a JPY 1 million cap per transfer. JPYC, by contrast, is a yen stablecoin issued in October 2025 by JPYC Co., Ltd. as a fund transfer service provider, and both subscriptions and redemptions require identity verification through JPYC EX.
On May 19, 2026, Japan’s Financial Services Agency published its acceptance standards for foreign stablecoins, with the rules taking effect on June 1. Under those standards, issuers must hold a foreign license comparable to Japan’s, reserve assets must be safeguarded and audited, and the home regulator must be able to exchange information with the FSA. Qualifying instruments are not treated as securities. DADRC notes that this was a binding Cabinet Office Ordinance revision rather than a nonbinding guideline, and says it effectively cleared the legal path for Netstars’ multi-token launch in July.
Netstars describes its role as a gateway. During the Haneda pilot, the lawyer involved in the structure said publicly that the setup had already been arranged in line with the Payment Services Act. Merchants saw yen prices and received yen settlement throughout the process, with no stablecoins entering merchant accounts.
Three phases: single token, more chains, then more tokens
DADRC breaks Netstars’ rollout into three stages.
The first stage was single-token, single-chain. From Jan. 26 to Feb. 28, 2026, Netstars and WEA JAPAN ran a USDC payment trial at two stores in Haneda Airport Terminal 3. The pilot used only Solana and only MetaMask. Merchants scanned a traveler’s payment QR code and still received yen settlement. The report says the test proved that in-store payment flow could work, but also exposed a usability problem. Netstars CEO Li Gang later said the limited chain and wallet choices were the biggest obstacle. If a traveler held USDC on another chain or used a different wallet, payment was not possible.
The second stage was single-token, multi-chain. On April 2, the next proof-of-concept moved to a trading card specialty store in Himeji. On April 8, Netstars introduced the StarPay-X concept to address the “one chain, one wallet” limitation. USDC remained the only token, but chain support expanded from Solana to Aptos and Canton, and Netstars began working with Circle’s Gateway for cross-chain USDC handling. Between May and June, the company signed memorandums of understanding with Aptos, Bitget Wallet, and Startale.
The third stage was multi-token, multi-chain. On July 13, Stablecoin Pay officially began accepting USDC, USDT, and JPYC. Supported chains were Solana and Polygon, the merchant fee rate was 0.98%, and the system still used existing POS terminals. DADRC says the timing matched the June 1 implementation of Japan’s foreign stablecoin standards. In August, Lawson completed a proof-of-concept, and in September Netstars signed MOUs with imToken and Kaia.
The hard part is not integration. It is wallet AML and KYA.
The report argues that adding another chain is not especially difficult from a technical standpoint. The challenge is that each new chain and each new wallet brings another group of payers that the acquirer needs to understand. In cross-border card acquiring or Alipay-style payments, the payer typically sits behind an issuing bank or payment company that has already performed KYC. With self-custodied wallets, that layer disappears. For the acquiring side, a MetaMask user may be nothing more than an address string.
Under Japan’s rules, most of the legal obligations sit with issuers and registered electronic payment instrument service providers. Issuers know the customers who subscribe and redeem directly with them, but once stablecoins move into self-custodied wallets, the issuer no longer knows who ultimately holds them. The article also cites a FATF targeted report from March 2026, which said peer-to-peer transfers involving stablecoins and unhosted wallets are currently the most common combination used for illicit funds. The report is not binding, but DADRC says regulators in different jurisdictions use it as a benchmark.
That leaves the merchant acquirer with the task of knowing the address, or KYA. In practice, that means running on-chain analysis before and after payment, checking sanction lists, reviewing contact with mixers or scam addresses, and determining whether funds came from a regulated exchange or from a fully anonymous source.

DADRC compiled a stage-by-stage matrix, based on public information, to describe the AML issues that can emerge as a stablecoin payment network expands:
| Expansion stage | New AML issue | Suggested approach from DADRC |
|---|---|---|
| Single token, single chain | One address format and one wallet, with risk concentrated in the payment address itself | Screen the payment address against sanctions data and exposure to scams or mixers |
| Single token, multi-chain | The same USDC may have just crossed a bridge, weakening source visibility; analytics coverage differs by chain | Use cross-chain tracing and apply the same risk-score threshold across chains |
| Multi-token, multi-chain | Issuers differ in freezing powers and redemption KYC; foreign stablecoins also face a JPY 1 million cap per transfer | Set limits by token and establish freeze-request channels with each issuer |
| Multiple wallet integrations | Custodial and self-custodial wallets mix together, and KYC depth ranges from full verification to none | Tier limits by payment source and agree with wallet providers on data-sharing arrangements |
The report says Netstars pushes part of the risk control burden to partner wallets. Bitget Wallet, for example, provides social login and scam interception to reduce operational mistakes by newer users. Public materials do not disclose the details of address screening, limits, or suspicious transaction reporting.
Five lessons DADRC draws for Taiwan banks and e-payment providers
DADRC says Taiwan’s banking sector has been allowed to operate e-payment businesses since 2015 and already has experience with cross-border payment collection and disbursement platforms. What is missing, in the report’s view, is a stablecoin payment and redemption channel plus an AML design that can handle self-custodied wallets. It lays out five recommendations.
Decide first who is allowed to touch the token
The article says Taiwan’s Virtual Asset Service Act passed its third reading on June 30, 2026, and the market expects implementation in 2027. Foreign stablecoins will require approval from the Financial Supervisory Commission to circulate in Taiwan. Before the dedicated law takes effect, DADRC says the safer structure is to keep the token offshore. Stablecoins would be received and redeemed by issuers outside Taiwan, while domestic banks would only receive U.S. dollars or Japanese yen, keeping virtual assets off bank balance sheets.
Reuse existing cross-border payment rails
The report points to bank-run e-payment businesses that already cooperate across borders with Alipay or WeChat Pay. Merchant due diligence, daily reconciliation and FX settlement, clearing checks, and dispute handling are already built into existing business rules. If the partner shifts from a payment company to issuers such as Circle or JPYC, DADRC says five of the six mechanisms can be reused. It also cites Circle’s April 2026 launch of CPN Managed Payments, a product that lets banks accept stablecoin payments while handling only fiat themselves.
Design for multiple wallets from the start
Netstars’ first-stage pilot exposed the cost of limited wallet support. DADRC says Taiwan could avoid one-by-one integrations if merchants display a standardized payment QR code that major wallets can all scan. The tradeoff is that the payment address is visible only after funds arrive, so screening would need to happen after receipt but before the receipt slip is issued.
Set limits based on payment source and transaction size
The article notes that existing cross-border cooperation with Alipay and WeChat Pay relies on Article 14 of Taiwan’s rules on identity verification and transaction limits for e-payment users, under which offshore institutions can perform user verification on behalf of the local side. That framework does not map cleanly onto an issuer-led stablecoin model, and tourists are unlikely to visit a bank just to complete KYC for a retail purchase.
DADRC proposes a different control structure. Payments coming from regulated exchanges, where payer information can be obtained through the Travel Rule, could qualify for higher limits. For large purchases, tax refund procedures already require merchants to check passports and issue tax refund documents for foreign visitors, and those records could support large-transaction review. For small payments, the report says the bank should not chase full personal identity. Instead, it should manage merchants through a risk-based approach, assigning risk grades by sector and transaction type, setting per-transaction and daily aggregate caps, and cutting limits or suspending payouts when unusual activity appears. The article adds that a pay-only structure, refunds sent back to the original source, and issuer freeze capability would help block cash-out paths.
Talk to regulators before filing
DADRC says four questions should be discussed with the Financial Supervisory Commission and the central bank before any proposal is submitted: how Article 14 would apply under an issuer model, whether the plan needs to go through a fintech regulatory sandbox, whether existing declaration codes for FX settlement can still be used, and what position the central bank takes on point-of-sale stablecoin payments.
Netstars showed that daily retail use is possible, but wallet risk controls come first
The article closes by saying Netstars proved in seven months that stablecoins can enter everyday retail spending without replacing POS systems and without exposing merchants to the tokens themselves. It also showed that broader chain and wallet support means a larger address universe for the acquirer to monitor. For Taiwan banks and e-payment providers, DADRC says the first-stage wallet coverage mistake can be avoided, but wallet-side AML design has to be addressed before any launch moves ahead.
The report adds that once the dedicated law takes effect, stablecoins are likely to enter ordinary consumer settings first. That may involve overseas visitors paying in Taiwan, or travelers from Taiwan using USDC or JPYC in Japan, with the underlying payment and settlement structure changing alongside those use cases.