
Spain’s latest housing intervention has prompted a fresh argument over whether real estate can still serve as a dependable long-term store of family wealth. In an opinion piece published by Bitcoin Magazine, Kristyna Mazankova writes that the country’s recent emergency housing decrees show how quickly the legal framework around property can be altered, and she presents Bitcoin as a contrasting asset whose core rules cannot be rewritten by decree.
Mazankova says she directs the Masters in Bitcoin at the Universidad de las Hespérides and focuses on how people build wealth over decades rather than weeks. In her telling, land and housing had long been one of the main answers for Spanish families seeking long-term wealth preservation. Her argument is not that real estate has no value, but that Spain has now placed one of the few wealth-building tools available to ordinary households under direct political risk.
Two emergency decrees, split into separate votes
The article says the Spanish government approved two emergency housing decrees on September 29. They took effect within days, with a planned hearing in Congress on Friday, October 2. Mazankova notes that the measures were not introduced as ordinary legislation. Instead, the government used the real decreto-ley mechanism, which the Spanish Constitution reserves for cases of “extraordinary and urgent need.” Under that process, a decree takes effect immediately and Congress then has 30 days to validate or repeal it.
According to the article, the government split the housing reforms into two separate decrees so each one could be voted on individually rather than risking the whole package on one divisive measure.
The first decree capped rent increases through the end of 2027. If an existing rent was already above the maximum level set by the official reference-price index, it could not rise at all. In all other cases, the parties could agree on an update, but absent a new agreement the increase could not exceed 2%. Mazankova points to Spain’s September inflation rate of 4.9%, citing the national statistics institute, and argues that landlords’ real income would therefore shrink each year under the rule.
The second decree went further. At the end of the minimum term, if neither side had given notice, the lease would renew compulsorily in successive five-year periods, or seven years if the landlord was a legal entity. A landlord ending a contract without a reason specifically listed in law would have to compensate the tenant. The article says that payment would, where possible, be calculated using the state rent-reference system and could never be less than one month of rent for every year the tenant had lived in the property.
In Mazankova’s view, those provisions strip owners of much of their freedom to recover their own property or re-let it at current prices. She also says the rules would apply to contracts that had already been signed, beginning at their next renewal date, citing a Provivienda summary.
Constitutional objections and the vote in Congress
The article says this is why many critics consider the decrees unconstitutional. Their argument, as summarized by Mazankova, is that the measures retroactively rewrite private agreements signed under different rules, which Article 9.3 of the Constitution bars when individual rights are being restricted.
Congress did not settle that constitutional question. On October 2, the first decree was rejected by 178 votes to 172, and the second was rejected by 184 to 166, according to the article. Sánchez then called general elections for November 29.
Mazankova writes that on the following Tuesday, the Council of Ministers approved both decrees again with only technical changes and sent them to the Diputación Permanente of Congress, the reduced body that replaces the full chamber once Congress is dissolved. She adds that Junts’ vote would not be needed in that setting.
The article says Sánchez stated that the second decree, the one dealing with automatic renewals, would only take effect if that body validated it rather than upon publication in the BOE. Mazankova also notes that jurists consulted by one newspaper described the maneuver as bordering on an abuse of law.
Early market response and listing withdrawals
One of the central claims in the piece is that investors can handle strict rules, but they cannot price an asset properly when the rules change after capital has already been committed. Mazankova presents that as the lesson not just for Spain, but for property owners across Europe.
The market response, she says, came quickly. The article cites a Spanish television program, EDATV, as reporting that about 2,900 rental listings were pulled from property portals in roughly four hours. It also cites LaBandera as saying that listings in Madrid fell by about 20% in under 24 hours, dropping from 11,815 to 9,398.
Mazankova acknowledges that these were early counts and had not been audited. Even so, she argues that the direction of the move was clear.
Examples from Berlin, San Francisco, Catalonia, and Spain
The article argues that Spain is replaying an experiment that has already been tested elsewhere.
- Berlin, 2020: The city froze rents for five years. Mazankova says studies at the time found that the supply of regulated apartments was roughly cut in half while unregulated rents moved higher. Germany’s constitutional court later struck the law down in 2021.
- San Francisco, 1994: Citing Stanford researchers Diamond, McQuade, and Qian, the article says expanded rent control helped incumbent tenants remain in place, but landlords reduced regulated supply by about 15%, while citywide rents rose by about 5%.
- Catalonia, 2024: The piece says rent caps in stressed zones slowed rent growth, but rental listings fell 22.2% in Barcelona while rising 3.9% in Madrid. That data is attributed to Fedea via idealista.
- Spain, 1946 to 1985: Mazankova says forced, near-permanent lease extensions kept old rents frozen for decades, leading owners to stop maintaining buildings and contributing to urban decay in city centers until the 1985 Boyer decree ended the system.
She argues that the new automatic-renewal decree follows the same underlying logic as that earlier Spanish model.
The article’s diagnosis: a housing shortage, not a landlord problem
Mazankova writes that Spain does not fundamentally have a landlord problem; it has a housing shortage. She says that in 2025 about 240,000 new households were formed while only around 92,000 homes were completed. The Bank of Spain, she adds, estimates an accumulated deficit of roughly 750,000 homes for the 2021-2025 period, citing Cantabria Económica.
The same report, according to the article, identifies scarce buildable land, slow urban development, and rigid planning as key constraints. Mazankova also cites Daniel Fernández Méndez, identified as a colleague, as arguing that restrictive land rules and increasingly strict building standards have made construction unprofitable even at current prices. That reference is attributed to Hespérides.
Her conclusion is that the state is squeezing supply from both sides: limiting what can be built, then capping what can be earned from what already exists. In that framework, established owners retain options. They can sell, wait, or leave an apartment empty rather than accept the risk of a tenant who may never leave. Renters, she says, bear the heavier cost.
The article argues that with fewer apartments available, rents on the remaining stock will rise, and more people may be pushed into informal arrangements without contracts and without protection, near the edge of the grey economy. Buying, Mazankova says, is no escape because Spaniards cannot afford to buy for the same basic reason they cannot afford to rent: there are too few homes, and these decrees do not change that.
Some landlords may be pushed to sell, but she says that would have little effect on prices because sales adjust far more slowly than rentals. Owners whose mortgage exceeds the market value they could obtain would not be able to sell at all. Others, in her telling, would simply wait for a possible change of government and keep properties empty. The result, she writes, is that more people will be unable to rent or buy, tenants lose, small investors lose, and the housing shortage remains.
Why the article contrasts property with Bitcoin
The largest risk in real estate, Mazankova argues, is not the market itself but the fact that governments can change the rules surrounding the asset at any time while the asset remains trapped in a single jurisdiction. A building does not move.
Bitcoin, in her comparison, differs on each of those points.
- Fixed rules: Supply is capped at 21 million, and the article says that rule has not changed in 17 years. Mazankova writes that Bitcoin’s infrastructure is built precisely to stop such rule changes from happening. No minister can cap its yield, freeze it, or extend somebody else’s claim over it.
- Direct ownership: When held in a personal wallet, the asset has no tenant who can stop paying, no squatter who can move in, and no court that must approve its sale.
- Portability: It does not sit inside one national jurisdiction. If local rules turn hostile, savings do not have to remain there.
- Access for small savers: Buying property requires a deposit, a mortgage, a notary, and years of commitment. Bitcoin, she writes, can be bought a few euros at a time on a regular schedule.
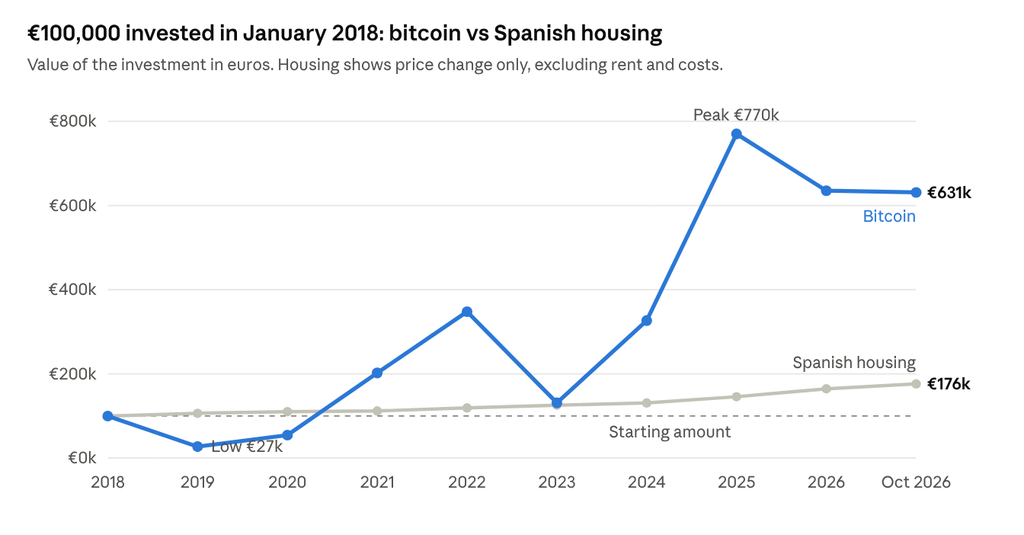
The article also stresses that most Spanish families hold the bulk of their wealth in property, and that this week’s events exposed how much of that wealth depends on politics. At the same time, Mazankova explicitly says Bitcoin is highly volatile. She notes that someone who bought just after the 2017 peak would have seen a bitcoin position lose almost three-quarters of its value within a year before later outperforming Spanish housing several times over. She adds that past performance does not predict future returns, that Bitcoin can fall sharply, that the housing comparison reflects price change only and excludes rental income, taxes, maintenance, and purchase costs, and that the piece is not investment advice.
Property as investment versus Bitcoin as long-term holding
The article closes by separating housing as shelter from housing as investment. Families will still need somewhere to live and will continue to buy or rent homes, Mazankova writes. What has changed is the case for the second flat, property purchased as an investment.
For a small investor, she argues, the risk now outweighs the return. In that setting, Bitcoin could fill part of the gap if it is treated the way property once was: as a long-term holding rather than a lottery ticket. Her practical framing is to think in years, buy regularly rather than trying to time the market, and never commit money that will be needed next year.
Mazankova ends with a direct contrast. Property gives an owner an asset whose governing rules can be rewritten. Bitcoin gives an owner price volatility, but rules that stay in place. Whatever Congress ultimately decides, she says, Spain’s property owners have now learned that contracts can be changed after they are signed.
The article first appeared on Bitcoin Magazine and was written by Kristyna Mazankova.