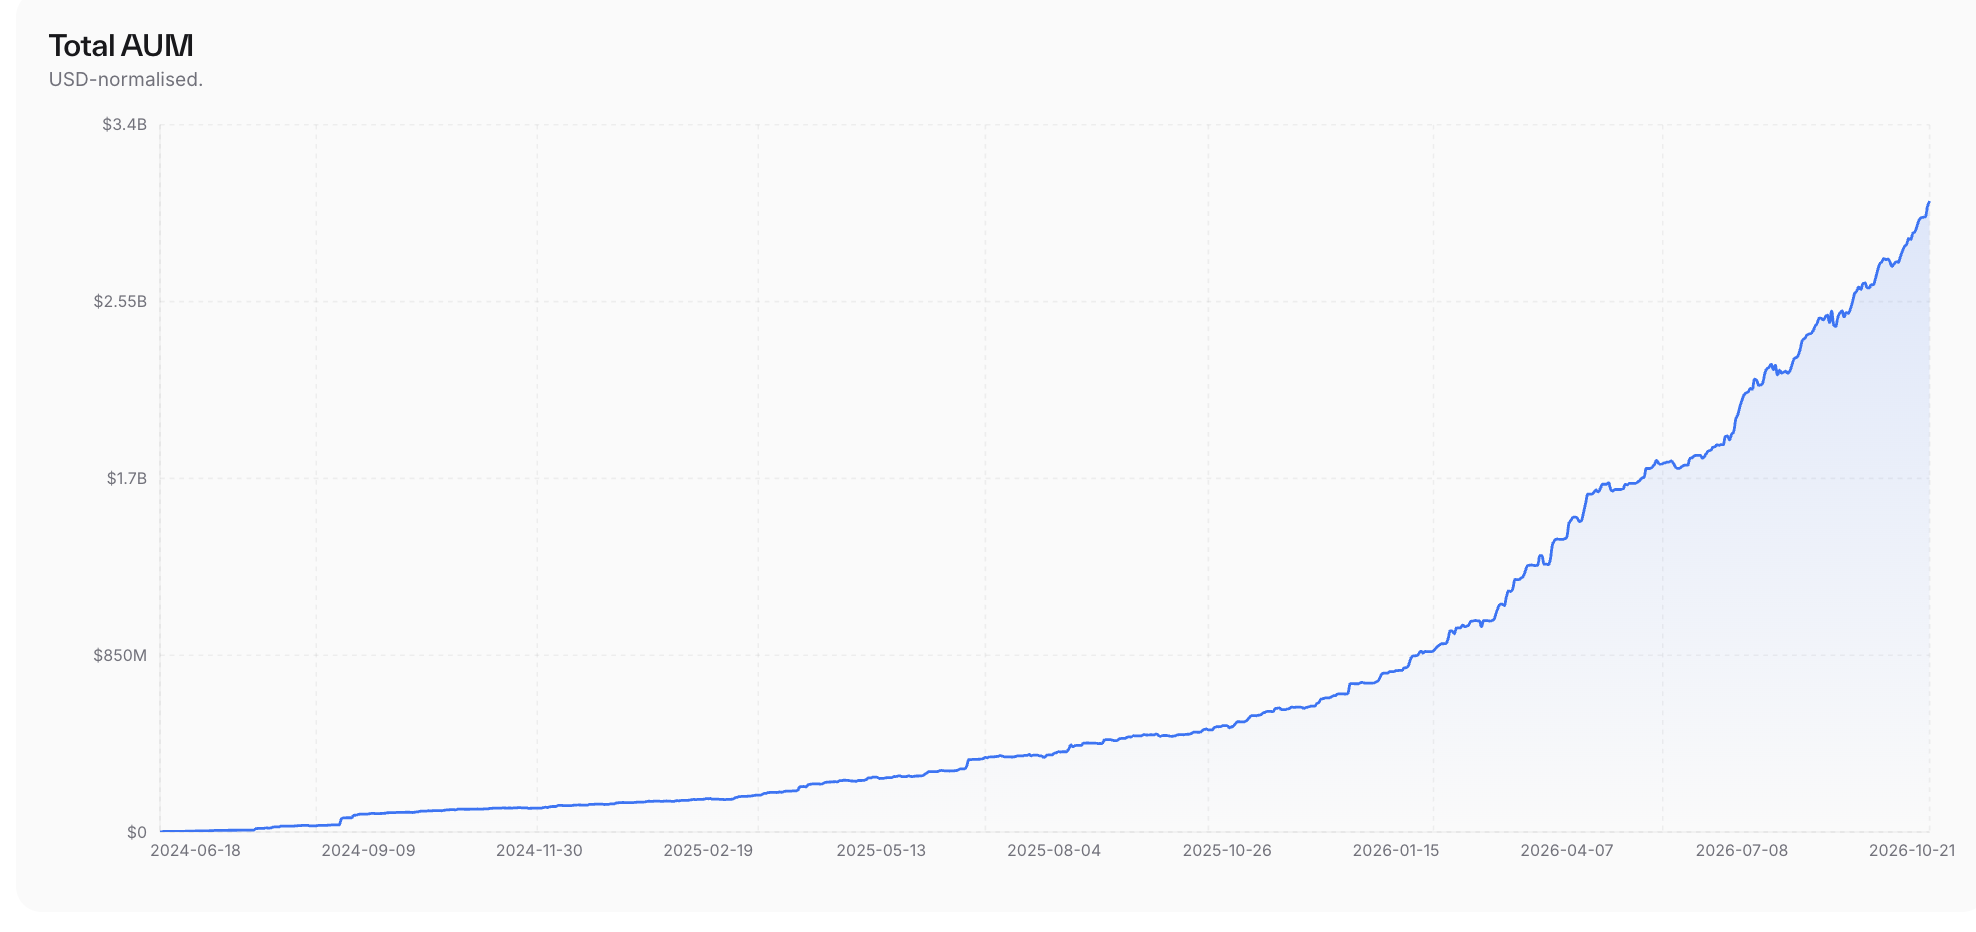
Spiko, a Paris-based startup focused on tokenized cash management, has grown its assets under management past $3 billion a little more than two years after launch.
According to the company dashboard checked on Oct. 21, total assets were up 323% from the start of the year and cumulative interest generated had reached about $45.03 million.
The company’s pitch is straightforward: help businesses and individuals manage idle cash more efficiently and earn yield on funds that would otherwise sit unused. Spiko uses a porcupine as its mascot. By the company’s own explanation, the animal stands for independence and protecting what belongs to you.
Founded in 2023 by a team with policy and technology backgrounds
Spiko was founded in June 2023 in Paris by Paul-Adrien Hyppolite and Antoine Michon.
Co-founder and CEO Paul-Adrien Hyppolite previously served as deputy head of the financial markets department at the French Treasury and also had private equity experience. Co-founder and COO Antoine Michon worked as a deployment strategist at Palantir and later served as an adviser on digital transformation for the French government.
That mix fits the company’s business. Spiko needs to understand how traditional financial products work and how they are regulated, while also turning those products into digital services that are easier to use and more automated.
Starting point: European corporate cash management
Spiko initially targeted the European corporate cash management market.
For companies, cash on the balance sheet is not simply money with no use. Businesses need liquidity for payroll, supplier payments, rent, taxes and emergency reserves. If that cash stays in current accounts for too long, returns may be low. If it is moved entirely into longer-duration or less liquid assets, day-to-day operations can be affected.
Large companies often have finance teams that can balance liquidity, safety and yield with more precision. Startups, small and medium-sized businesses, and some individuals may not have the scale, cost structure or product access needed to get the same level of cash management service.
Spiko’s approach is to take money market funds, a familiar product in traditional finance, and distribute them through digital products and technical infrastructure to customers that previously had limited access to more refined cash management tools. In June 2024, the company launched its first euro and U.S. dollar government bond money market funds across the European Union.
At the time, Spiko said it was raising €4 million, led by French venture capital firm Frst.
Total funding reaches $120 million
In July 2025, Spiko closed a $22 million Series A led by Index Ventures, with participation from White Star Capital, Frst, Rerail, Blockwall and Bpifrance’s digital venture fund.
Other backers included Revolut co-founder Nikolay Storonsky, Bridge co-founder Zach Abrams, Wise chief technology officer Harsh Sinha and Blackstone co-chief investment officer Lionel Assant.
In October 2026, Spiko announced a $90 million Series B led by NEA, or New Enterprise Associates. Other investors included Index Ventures, Bpifrance, Speedinvest, Flourish Ventures, Shapers, White Star Capital, Blockwall, Frst, EQNX, Mirana Ventures and Wintermute Ventures. In that Series B announcement, the company said total funding had reached $120 million.
Funding alone does not prove the business model has fully worked. The more important question for Spiko is whether it can keep attracting assets while maintaining clear risk boundaries, stable client relationships and a durable source of revenue.
Regulatory footing comes from traditional finance
On compliance, Spiko’s core money market funds operate under the European Union’s UCITS framework and have been approved by France’s Autorité des marchés financiers, or AMF. The company also holds the relevant French financial business licenses, and fund assets are held by professional custodians.
That gives the core business a relatively clear regulatory base in traditional finance. Still, regulatory requirements and risk differ by product. The article notes in particular that Cash & Carry, which involves crypto spot-futures arbitrage, should not be treated as if it had the same regulatory conclusions as a money market fund. Regulatory approval does not mean principal protection, and it does not mean investors in every country can buy the products.
Three product lines, three different uses of cash
To understand Spiko, one distinction matters at the outset: the company is not simply turning cash into onchain tokens. It is offering different fund strategies for different cash needs.
Its main products fall into three groups: T-Bills, Smart Cash and Cash & Carry. Each serves a different use case, with different sources of return, liquidity terms and risk profiles.
T-Bills: short-dated sovereign debt exposure
The earliest T-Bills products are the easiest to grasp. The funds invest in short-term government bonds, allowing holders to earn short-term interest rates in the relevant currency. Spiko currently focuses on euro, U.S. dollar and British pound products.
Because the bonds are short-dated, the funds are less sensitive to interest-rate changes than longer-duration products, though they still carry sovereign credit and liquidity risk.
According to key information documents disclosed in September 2026 for the euro and dollar products, ongoing charges were estimated at 0.25% per year based on actual costs over the previous year. There is no performance fee and no redemption fee. Standard redemptions are usually settled the same day.
Smart Cash: securities portfolio plus total return swap
Smart Cash, launched in March 2026, uses a structure built around a securities portfolio and a total return swap. The fund holds a basket of securities, such as equities included in the MSCI World Index and the S&P 500, then enters into a total return swap with a bank. The investment return on that portfolio is passed to the bank in exchange for the relevant currency’s overnight reference rate plus an agreed spread.
Using an equity basket as an example, if the stocks rise, that return goes to the bank. If the stocks fall, the bank absorbs the loss. Investor returns therefore depend mainly on the swap terms and the counterparty’s ability to perform.
BNP Paribas is the first banking counterparty for Smart Cash. The structure settles every business day to reduce counterparty risk, though losses are still possible if the bank defaults.
On its website, Spiko highlights euro, U.S. dollar, British pound and Swiss franc share classes for Smart Cash, with minimum investment starting from one unit of the relevant currency. The euro share class charges a 0.25% annual management fee, plus operating and other service fees of up to 0.10% per year. Standard redemptions are usually settled on the next business day.
For Smart Cash, Amundi acts as delegated investment manager. CACEIS, the custody and asset servicing arm of Crédit Agricole, handles custody and fund administration. Spiko is responsible for the register, tokenization platform and brokerage functions. Investment management, safekeeping of assets and maintenance of the register are split across different institutions.
Cash & Carry: targeting the spread between spot and futures
While T-Bills and Smart Cash are built around returns from traditional financial markets, Cash & Carry looks to crypto markets and seeks opportunities in the spread between spot and futures prices.
A simplified example in the article sets spot at $100 and a one-month futures contract at $101. The strategy buys spot and sells the corresponding amount of futures. If the position is held to expiry, prices converge and settlement goes smoothly, the theoretical spread capture is $1 per unit before trading, funding and other costs.
The strategy is not always deployed. Under rules updated in July 2026, it covers BTC, ETH, SOL and XRP, and allocates in batches based on return thresholds, entry windows and position limits. When opportunities are insufficient, the fund can hold cash or money market allocations instead. As contracts approach expiry, positions are rolled into the next contract according to the rules or allowed to expire.
The fund gets exposure to the strategy through notes issued by Marex. That means investors face not only basis risk between spot and futures, but also default risk from the note issuer.
Cash & Carry is aimed at qualified professional investors. The minimum first subscription is €100,000 or the U.S. dollar equivalent. The annual management fee is 0.10%. It also charges a performance fee: 25% of returns above SOFR for the dollar share class and 25% of returns above €STR for the euro share class. Standard redemptions are usually settled in two business days.
API distribution has around 20 partners
Spiko also relies on API distribution as a major channel.
In July 2026, the company said it had around 20 partners on that side of the business, carrying close to €500 million in assets. Digital financial services provider Ramify has embedded Smart Cash into its app. Memo Bank, which serves small and medium-sized businesses and mid-market companies, and savings app Bitstack have also integrated the service.
The commercial logic is clear. Partners handle customer reach, so Spiko’s expansion depends not only on direct acquisition through its own platform but also on how many users and how much capital partner applications can bring in.
After $3 billion in assets, revenue is still a separate question
As of Oct. 21, Spiko’s official dashboard showed total assets under management above $3 billion, up 323% from the start of the year, with about $45.03 million in cumulative interest generated. The combined user count across products stood at 15,721, though that figure cannot be treated as a direct count of unique clients. Changes in assets also reflect accumulated returns and foreign-exchange translation, not only net new inflows.
The product mix is also revealing. Smart Cash’s euro share class had about €1.78 billion in assets under management, while euro T-Bills had about €467 million. Smart Cash euro had become the platform’s largest single product.
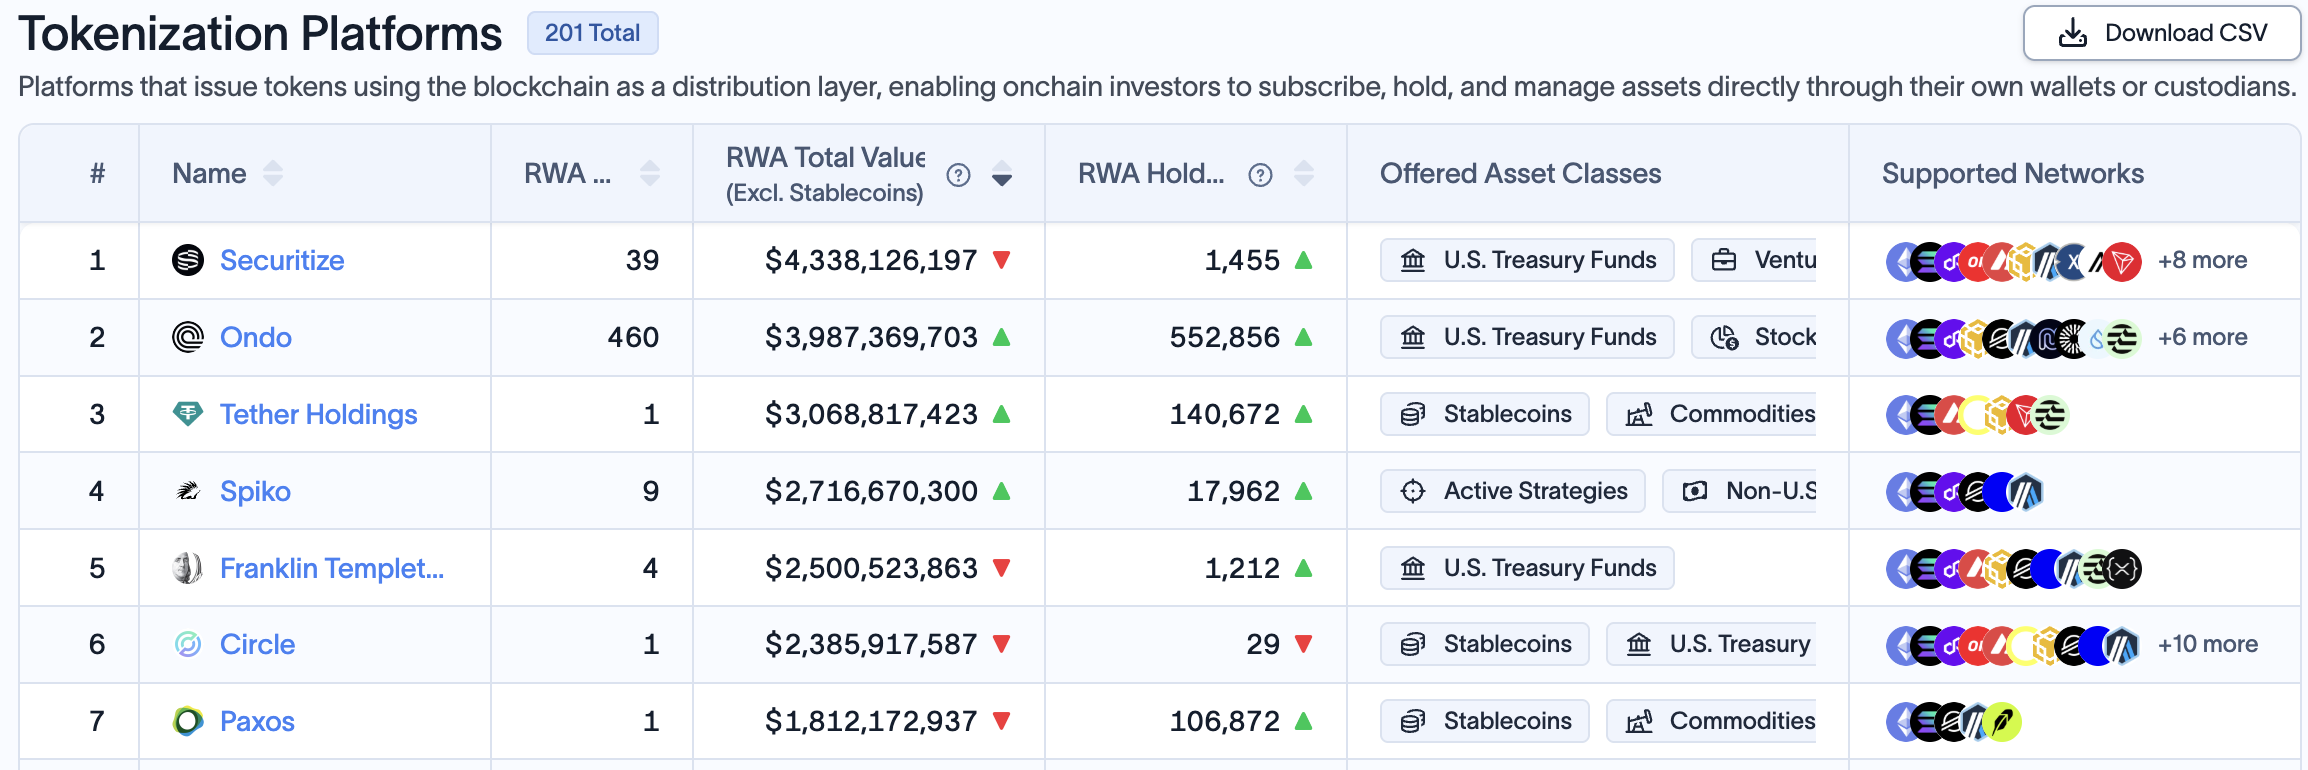
Against other RWA platforms, Spiko has reached a scale that is hard to ignore. As of Oct. 21, 2026, RWA.xyz showed Spiko at about $2.72 billion in distributed asset value, compared with about $4.34 billion for Securitize and about $3.99 billion for Ondo.
Their business focus is different. Securitize provides tokenization infrastructure for multiple asset managers. Ondo offers products tied to Treasuries and securities including equities. Spiko is more concentrated on cash management and active strategies, linking businesses, individuals and financial platforms through apps and APIs.
That means Spiko’s competitive position cannot be judged by asset size alone. Another test is whether its cash management products can become part of clients’ routine treasury and financial operations.
Client returns and company revenue also need to be separated. DefiLlama showed Spiko’s revenue at about $556,000 over the past 30 days at the time of the query. The article notes that this figure is mainly inferred from tracked assets and preset fee rates, and does not fully include performance fees, so it should be read only as a third-party estimate of management-fee income.
More than putting fund shares onchain
What sets Spiko apart is its attempt to combine the logic of traditional cash management with tokenization and blockchain infrastructure. It started with short-term sovereign debt and money market funds, then expanded into bank swap strategies and crypto spot-futures arbitrage, while also supporting subscriptions and redemptions through stablecoins.
Based on the figures disclosed so far, Spiko has shown that there is real demand for this kind of business. Still, growth in assets and successful fundraising are only interim results. Whether it can keep attracting capital will depend on the competitiveness of returns, fee levels, and its ability to manage liquidity, risk and compliance as it scales.
For Spiko, the larger opportunity is not simply to move fund shares onto blockchain rails. It is to make cash management products easier to buy, hold and use, while improving the efficiency of yield generation without trading away capital safety.