
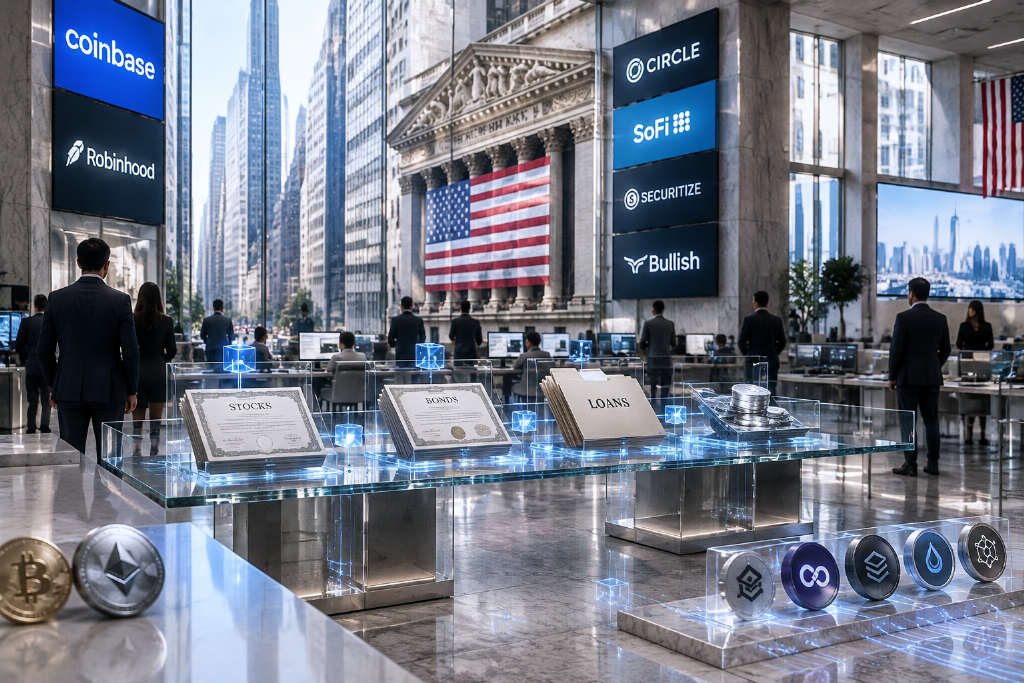
Citrini Research says Wall Street’s move to put financial assets on blockchains could open a major new market for crypto, but investors looking to play tokenization may find stronger opportunities in fee-generating businesses and protocols than in bitcoin or ether themselves.
In a 79-page report titled Breaking the Wall, published Thursday, the research firm said bringing stocks, bonds and other financial assets onchain could create new lines of business across trading, lending and payments. Its central argument is that the clearest upside may sit with the companies and crypto projects that collect fees as that activity grows.
“We can't assume that majors, primarily BTC and ETH, will make new ATHs on this,” the report said. “Even if they do, there are better expressions.”
How Citrini frames the tokenization opportunity
The report describes tokenization as the process of turning traditional assets into digital tokens that can move across financial platforms and potentially trade around the clock. A tokenized stock, for example, could be used as collateral for a loan directly from an investor’s digital wallet rather than through a traditional brokerage account.
Citrini argues that this flexibility could open new markets for trading venues, lenders, stablecoin issuers and firms that maintain records of securities ownership. In that setup, the biggest winners may be the entities taking a cut of the flow.
The firm is widely followed for its work on technology and markets, including artificial intelligence, and runs a Substack newsletter with more than 263,000 followers. CoinDesk noted that Citrini’s AI research went viral earlier this year and briefly triggered a broader market sell-off.
Stock basket: public companies tied to onchain finance rails
To identify opportunities, Citrini built two investment baskets: one focused on publicly traded stocks and another on crypto tokens. In the stock basket, the report leans toward businesses that could earn fees as more of Wall Street shifts onchain.
Securitize (SECZ) is one of the names highlighted. Citrini said the firm maintains the legal link between blockchain-based tokens and the securities those tokens represent.
Coinbase (COIN) and Robinhood (HOOD) were included for their trading platforms and blockchain infrastructure. Circle (CRCL), the issuer of USDC, was also named as a potential beneficiary if tokenized transactions increase demand for stablecoin settlement.
The report also cited Figure Technology Solutions (FIGR) for tokenized lending, SoFi (SOFI) for stablecoin payments and Bullish (BLSH), an institution-focused digital asset exchange operator. CoinDesk identified Bullish as its parent company and said Bullish is acquiring share registrar Equiniti.
Crypto basket: broader exposure than listed equities
Citrini said it was “actually more excited” about its separate crypto-token basket, arguing that listed companies offer a narrower opportunity set than digital assets.
“If we’re right that stocks, commodities and other financial assets are moving onchain, then eventually all of the financial products built around those assets should follow them,” the report said.
Among the names in that basket, Aerodrome (AERO) was highlighted as a trading platform that could collect fees from tokenized stock transactions. Maple (SYRUP) was included for its blockchain-based lending products aimed at institutional investors.
Pendle (PENDLE) made the list because it lets investors trade future income from yield-bearing assets. Ondo Finance (ONDO) was cited for tokenized U.S. Treasury products, tokenized stock products and, more recently, perpetual futures.
Citrini also included Aave (AAVE) for lending infrastructure, Uniswap (UNI) for decentralized trading and Ethena (ENA) for stablecoin issuance and its recent expansion into digital finance products that combine high-yield savings, cards and payments.
The basket extends to ether.fi (ETHFI), Chainlink (LINK) and LayerZero (ZRO). The report said all three could benefit as tokenized assets spread across financial platforms and blockchain networks, with exposure to crypto-based financial services, market data and cross-chain connectivity.
Derive (DRV), a decentralized options protocol, was also highlighted. Citrini said it could benefit if tokenized stocks and other financial assets bring more derivatives trading onto blockchains.
Perpetual futures venues also drew attention
The report gave a nod to Lighter (LIT) and Variational (VAR), two newer perpetual futures venues. Perpetual futures, or perps, let traders bet on whether an asset’s price will rise or fall without owning the asset, and unlike traditional futures contracts, they do not expire.
Citrini said Hyperliquid (HYPE) has emerged as the dominant blockchain-based platform for perps trading. Even so, it added that Lighter and Variational may gain traction alongside Hyperliquid as the broader perps market expands. The report also included exposure to Hyperliquid in its stock basket through the Bitwise Hyperliquid ETF (BHYP).
Why the report stops short of a blanket bullish call on tokens
Citrini also warned that rising trading volumes and stronger network activity do not always translate into higher token prices. Investors, the report said, need to examine how protocols make money, who captures the fees and whether token holders participate in that economics.
It also flagged several risks that could slow adoption: liquidity split across competing blockchains, security concerns and legal hurdles tied to synthetic tokenized stocks. Those products may offer exposure to share-price moves, but they do not give investors the voting rights or direct ownership associated with traditional shares.