BCG

AI
2026-09-15 01:13:08

The Bigger Question in AI Spending Isn’t When the Bubble Bursts

Debate around a possible AI capital expenditure bubble has moved from tech circles into boardrooms, where executives are asking whether current spending levels are sustainable and what a reversal could mean for the broader economy. This article argues that trying to predict the timing of a bubble’s collapse is the wrong frame. A more useful line of inquiry is how the AI buildout affects economic activity, which transmission channels carry the greatest risk, and under what conditions a spending boom becomes a systemic crisis rather than a painful but contained correction. Using a narrower macro lens, the piece estimates AI-related capital spending at about $630 billion in 2026, just under 2% of U.S. GDP. After adjusting for imports, especially semiconductors, the direct boost to U.S. domestic activity falls to roughly $315 billion, or about 1% of GDP. Bloomberg consensus expectations cited in the article suggest that adjusted figure could rise to 1.5% of GDP by 2028. The article then examines three main risk channels: a halt in economic activity, negative wealth effects from equity declines, and tighter credit conditions if debt tied to the AI boom turns sour. Its central conclusion is that AI spending may still represent a manageable macro risk as long as losses do not severely damage the banking system. The article also argues that bubbles can leave durable economic benefits by financing infrastructure that outlives the speculative cycle, and it offers five practical takeaways for corporate managers operating through the current AI investment surge.
690
The Bigger Question in AI Spending Isn’t When the Bubble Bursts
a16z
2026-08-18 12:43:00

a16z Breaks Down the AI Compute Trade: Revenue Is Surging, but Capex and Profitability Still Cloud the Picture

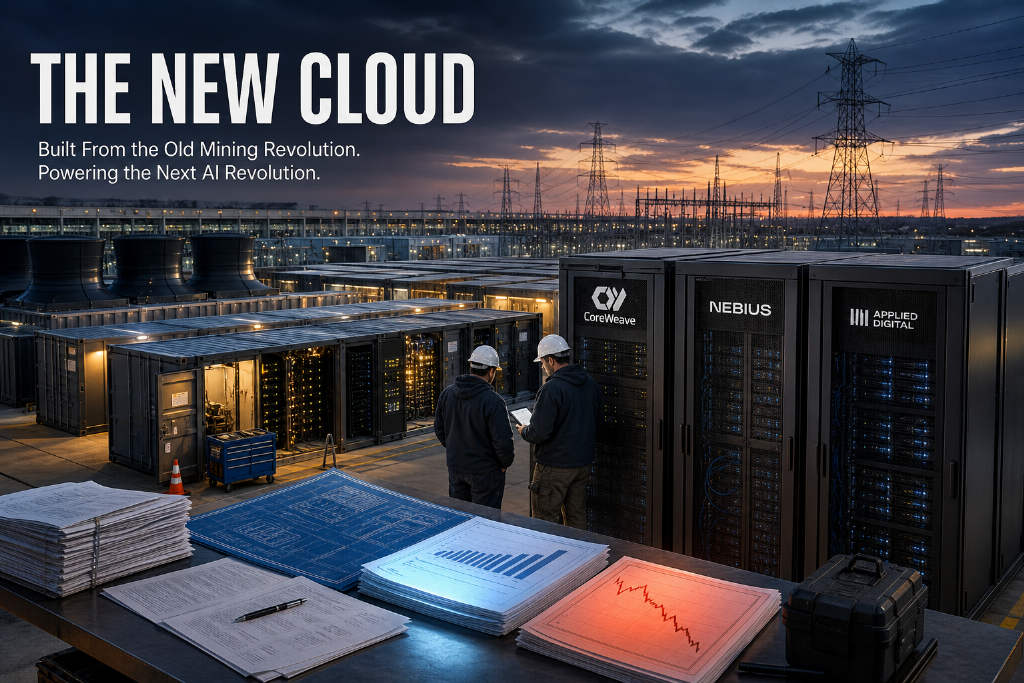
Andreessen Horowitz’s New Media team used its latest Charts of the Week to examine the AI infrastructure trade through a wider lens than headline demand growth. Moses Sternstein focused on neocloud companies such as CoreWeave, Nebius, and Applied Digital, arguing that the market’s question is no longer whether AI needs more compute, but whether providers can turn that demand into durable cash flow. The piece says many neocloud players entered the AI cycle with an advantage built during the crypto mining era: power access, data center capacity, cooling systems, and experience running dense compute loads. That legacy helped them scale revenue quickly, with CoreWeave reaching $2.6 billion in revenue in about 25 quarters versus 40 quarters for AWS after launch. Still, investors have not rewarded growth evenly. Over the past year, CoreWeave shares were down about 16%, while Nebius stayed closer to prior highs, highlighting concerns over capital intensity, depreciation, and rising interest expense. Sternstein also argues that AI is reshaping software unevenly rather than destroying SaaS across the board. Atlassian’s cloud revenue rose 31% year over year, and customers using its AI assistant Rovo were spending at nearly twice the growth rate of non-Rovo users. Databricks, meanwhile, said its Smart Router can cut average task costs by more than 30% by matching tasks with different model tiers. The article closes with data on widening enterprise AI spend gaps and diverging hiring patterns at OpenAI and Anthropic.

1240
a16z Breaks Down the AI Compute Trade: Revenue Is Surging, but Capex and Profitability Still Cloud the Picture
RWA
2026-08-13 03:10:08

Securitize’s first post-IPO earnings show a hard truth for RWA: tokenized assets grew, revenue did not

Securitize’s first earnings report since going public has sharpened a question hanging over the real-world asset sector: can tokenization platforms turn rising on-chain asset volume into meaningful revenue? The company reported a record $4.3 billion in tokenized assets under management and $5.3 billion in on-chain transaction volume, up 16% and 147% year over year, respectively. Yet quarterly revenue fell 5% to $14.4 million, well below Wall Street’s $20.6 million expectation, while net loss widened to $21.7 million. Adjusted EBITDA also swung from a $1.8 million profit a year earlier to a $5.5 million loss. The report points to a basic tension in the RWA business model. Securitize powers issuance, transfer agency, compliance KYC, and broker-dealer functions for products such as BlackRock’s BUIDL, but it does not collect the larger pool of economics that goes to asset managers, investors, and custodians. Based on the figures cited in the article, its implied annualized fee rate works out to roughly 1.34 basis points on $4.3 billion of AUM. That has pushed investors to look past top-line tokenization growth and ask a tougher question: how much can infrastructure providers actually earn from every dollar that comes on-chain?

1460
Securitize’s first post-IPO earnings show a hard truth for RWA: tokenized assets grew, revenue did not
Securitize
2026-07-23 09:10:18

BlackRock-Backed Securitize Drops About 40% After SPAC Listing

Securitize fell sharply after completing its SPAC merger, sliding about 40% since last week despite rising interest in tokenized assets. Analysts pointed to post-SPAC shareholder turnover and weak sentiment toward recent crypto listings.

1790
BlackRock-Backed Securitize Drops About 40% After SPAC Listing