Serenity
Aug 31, 2026

Serenity says Celestial could have been valued at $6 billion to $10 billion as a standalone U.S.-listed company

Serenity said on Aug. 31 that Celestial, which has already been acquired by Marvell, might have commanded a valuation of $6 billion to $10 billion if it had remained independent and listed in the U.S. market. The argument rests on Celestial’s earlier revenue outlook, which projected $500 million in 2028 on a fourth-quarter annualized basis and $1 billion in 2029, as well as its role as a core participant in co-packaged optics, or CPO, projects for hyperscale cloud customers. Serenity contrasted that with Celestial’s reported financial profile in the second quarter of 2026, when revenue was close to zero and quarterly losses were about $12.5 million. Marvell had also said the company’s post-acquisition contribution to revenue and profit was not material. Serenity argued that judging Celestial only by quarterly price-to-sales metrics and near-term losses could lead the market to treat it like a “worthless meme stock,” while a valuation framework centered on qualification cycles and large-scale commercialization opportunities in 2028 would point to a much higher figure.
1580
Serenity says Celestial could have been valued at $6 billion to $10 billion as a standalone U.S.-listed company
Morgan Stanley
Aug 26, 2026

Morgan Stanley says off-balance-sheet commitments are becoming central to AI compute finance

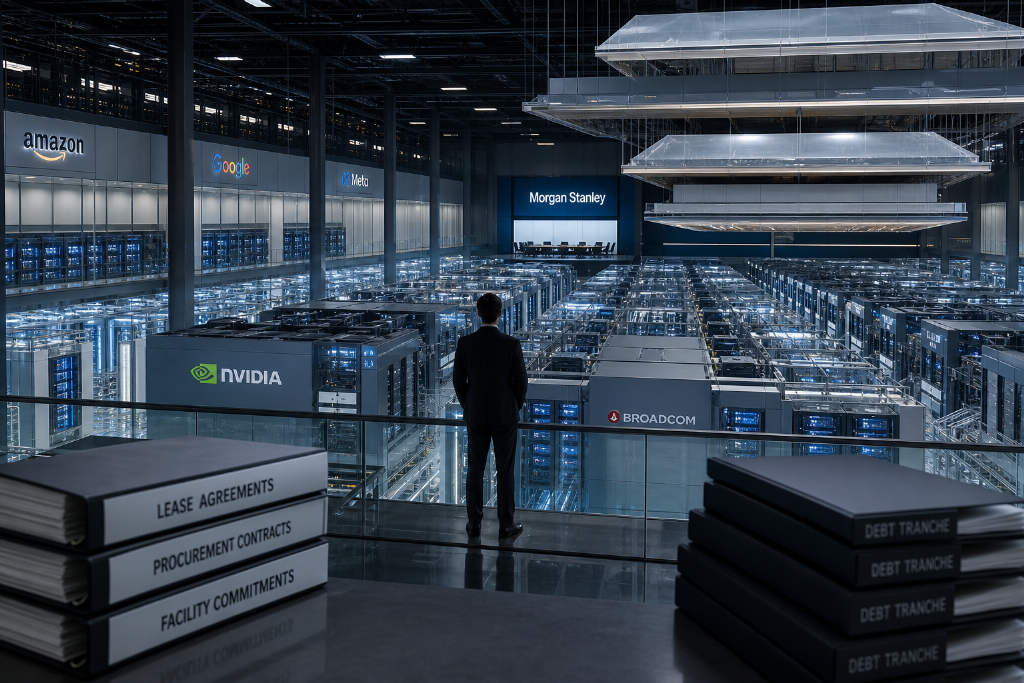
A Morgan Stanley research note, cited by Chaoxiang Research and reported by ChainCatcher, says disclosed off-balance-sheet commitments from hyperscalers, Nvidia and Broadcom have climbed past $3.1 trillion. The total includes $1.1 trillion in lease commitments and $1.7 trillion in purchase commitments, while on-balance-sheet debt and lease liabilities at hyperscalers stand at a combined $770 billion. The note also points to mounting pressure on cash generation. Amazon and Google had negative free cash flow in the second quarter of 2026, and Meta is expected to follow in the next quarter. Morgan Stanley argues that financing tools are reshaping the capital structure behind AI compute through six channels, including off-balance-sheet leasing and purchase commitments, a rise in debt issuance share from 2% in 2025 to 19% in 2026, and Google freeing up $110 billion by cutting buybacks and issuing equity. The report also highlights Oracle’s $4.6 billion in customer prepayments in the second quarter and chip-leasing SPVs launched by Broadcom and Nvidia to support unrated AI labs. Morgan Stanley’s conclusion is that changes in financing structures and accounting judgments now matter almost as much as chip shipment volumes in tracking the AI supply chain.

2300
Morgan Stanley says off-balance-sheet commitments are becoming central to AI compute finance
Nvidia
Aug 19, 2026

Ben Thompson says Nvidia’s financing tactics cut into profits as easing power constraints weaken its moat

Ben Thompson, founder of Stratechery, argued in a recent interview that Nvidia’s exceptional profitability may be less durable than it appears as the AI spending cycle enters a more contested phase. His view centers on two pressure points. First, he said Nvidia has supported newer cloud providers, or “Neoclouds,” through equity stakes and roughly 25% backstops tied to commitments to keep buying Nvidia compute through 2030. That may help sustain GPU shipments, but Thompson said the risk does not disappear; it shifts back onto Nvidia if compute demand weakens or those buyers cannot keep purchasing. In his framing, that amounts to a hidden reduction in profit and functions like an indirect price cut. Second, Thompson said Nvidia’s energy-efficiency edge matters most when power is scarce. He argued that unexpectedly resilient U.S. electricity supply over the past two years — including natural gas generation in West Texas, restarted nuclear plants, and grid-related deployments by Elon Musk — gives hyperscalers such as Amazon and Google more time to improve in-house chips like Trainium and TPU. That, in turn, could erode Nvidia’s technical moat. Even if the current AI boom ends in oversupply and a market correction, Thompson said the resulting buildout of power infrastructure may still become the most durable legacy of the cycle.

1560
Ben Thompson says Nvidia’s financing tactics cut into profits as easing power constraints weaken its moat
Nvidia
Aug 13, 2026

VC partner says Nvidia is becoming a “synthetic hyperscaler” in the AI compute stack

Altimeter Capital partner Clark Tang argues that Nvidia is no longer just a chip supplier to the AI industry. In his view, the company has been building the two pillars that historically defined hyperscalers: an operating layer that abstracts and manages infrastructure, and a financing layer that funds capacity ahead of demand. Tang says this combination is turning Nvidia into a “synthetic hyperscaler,” one that is starting to displace Amazon, Microsoft, and Google in parts of the AI compute supply chain. His thesis begins with a shift in infrastructure economics. Traditional hyperscalers built strong margins by converting enterprise capex into opex and using software to maximize utilization of shared hardware. Tang says AI workloads break that model. Large-scale training depends on tightly synchronized GPU clusters, while inference is highly sensitive to tokens per watt and time to first token. In that setup, virtualization and networking layers that worked well in the cloud era can become a drag on GPU performance. He also points to the rise of neocloud providers, which offer lower-margin, AI-focused infrastructure but often lack the balance sheet strength to finance aggressive buildouts. Tang says Nvidia has moved to close that gap with software such as DSX OS, Mission Control, Omniverse, and Dynamo, while also standardizing hardware and bringing in third-party capital from firms including Apollo, BlackRock, Blackstone, Goldman Sachs, and KKR.

1960
VC partner says Nvidia is becoming a “synthetic hyperscaler” in the AI compute stack
NVIDIA
Aug 12, 2026

NVIDIA shifts toward a broader customer base as hyperscaler concentration risk comes into focus

NVIDIA is moving to reduce its dependence on hyperscalers as large cloud companies push to diversify away from a single AI chip supplier, according to recent analysis from investor and researcher Evergreen Capital. The firm argues that CEO Jensen Huang has been signaling that shift for months, highlighted by his repeated use of the word “diverse” during the company’s earnings call after May results. Evergreen reads that language as a deliberate repositioning: away from being seen mainly as a chip vendor tied to hyperscaler orders, and toward becoming an AI systems platform serving a wider range of customers. In a follow-up note about three months later, Evergreen said NVIDIA’s actions are starting to match that narrative. It pointed to SPCX transactions and a GPU financing program designed to expand access to compute for smaller enterprises and emerging AI companies, while lowering revenue concentration tied to hyperscalers. The analysis also says non-hyperscaler enterprise AI compute already accounts for about half of NVIDIA’s revenue, with analysts expecting that share to exceed 70% in the next few years. If that mix shift holds, Evergreen believes the market could reassess NVIDIA with a different valuation framework.

2140
NVIDIA shifts toward a broader customer base as hyperscaler concentration risk comes into focus
UBS
Aug 2, 2026

UBS says storage could take 73% of hyperscaler capex by 2027, reaching $761.3 billion

UBS said spending on storage is rising quickly as demand from AI GPU vendors and hyperscale cloud providers accelerates and average selling prices for storage products move higher. The bank estimates that the world’s top 11 hyperscale cloud service providers will spend a combined $1.0403 trillion in capital expenditures in 2027, with $761.3 billion of that going to storage, lifting storage’s share to 73%. UBS also outlined a steep climb in overall capex and storage spending over the next two years. Total capex is projected to rise from $504 billion in 2025 to $873.9 billion in 2026 and then to $1.0403 trillion in 2027. Over the same period, storage spending is expected to jump from $72.8 billion to $335.7 billion and then to $761.3 billion, with year-over-year growth of 361% in 2026 and 127% in 2027. By product, UBS expects HBM, DDR and NAND spending all to increase sharply, while average prices per Gb or GB also move up. The bank added that storage makers will need to expand capacity to meet demand, though fab space, equipment delivery times and labor constraints remain major bottlenecks.

2760
UBS says storage could take 73% of hyperscaler capex by 2027, reaching $761.3 billion
Goldman Sachs
Jul 25, 2026

Goldman Sachs flags three reflexive loops weighing on global markets

Goldman Sachs says global markets are being pressured by three self-reinforcing loops that are starting to feed on one another: the interaction between oil prices and politics, rising capital spending by hyperscale cloud companies, and growing stress in AI infrastructure debt. In a client note this week, Rich Privorotsky, head of 1-Delta trading at Goldman Sachs, argued that the combination has left markets sitting on what he described as a fragile and dangerous equilibrium. The report points to Brent crude briefly moving above $100 a barrel, a level that challenged assumptions about how quickly U.S. policy might respond if higher gasoline prices began to hurt political support. At the same time, investors are becoming less willing to treat giant AI-related spending plans as costless growth signals. Google raised its 2026 capital expenditure guidance to $195 billion-$205 billion, reported negative free cash flow of $5.9 billion for the quarter, and saw its shares fall 6.9%. Privorotsky also highlighted pressure in financing markets tied to AI buildouts, citing Meta’s $27.3 billion "Hyperion" financing through Beignet SPV. The bonds were issued at par, later traded above 109, and have since fallen back to around 95. He said the next key tests for this broader thesis will be Microsoft’s earnings call and ChangXin Memory Technologies’ listing on Shanghai’s STAR Market.

1630
Goldman Sachs flags three reflexive loops weighing on global markets
Total 19 items
Go topage