
Alea Research said in a new report that the onchain dollar yield market changed materially in the third quarter of 2026. The tracked onchain dollar pool universe reached $39.2 billion, far above the $8.6 billion held across 27 listed tokenized U.S. Treasury funds used as the benchmark. On a 30-day rolling yield basis, 82.9% of onchain dollar pools were outperforming Treasury funds by the end of the quarter, up from 65.4% on June 30.
The report said the widening spread was not just about token incentives. Roughly half of the rise in base yield came from Treasury funds lagging moves in 3-month Treasury yields, while the rest came from higher onchain lending rates, protocol rate resets and the launch of new higher-yield pools. Reward tokens accounted for 60% of the portion of onchain dollar returns that exceeded Treasury funds.
Borrowers paid more while Treasury funds adjusted more slowly
The report framed onchain dollar pools and tokenized Treasury funds as two ways to sell dollar yield that remains onchain. Treasury funds pass through Treasury income after management fees. Onchain pools pay lenders from borrower interest after protocol take rates, including borrowers in Aave’s $9 billion lending market, institutional borrowers in Maple’s $3.9 billion credit pools, and returns from selected basis strategies and reward-token programs.
In practical terms, the report said tokenized Treasuries offer capped but safer yield, while onchain pools can pay more because their returns are not capped in the same way. The trade-off is exposure to the credit risk of whoever is paying that yield.
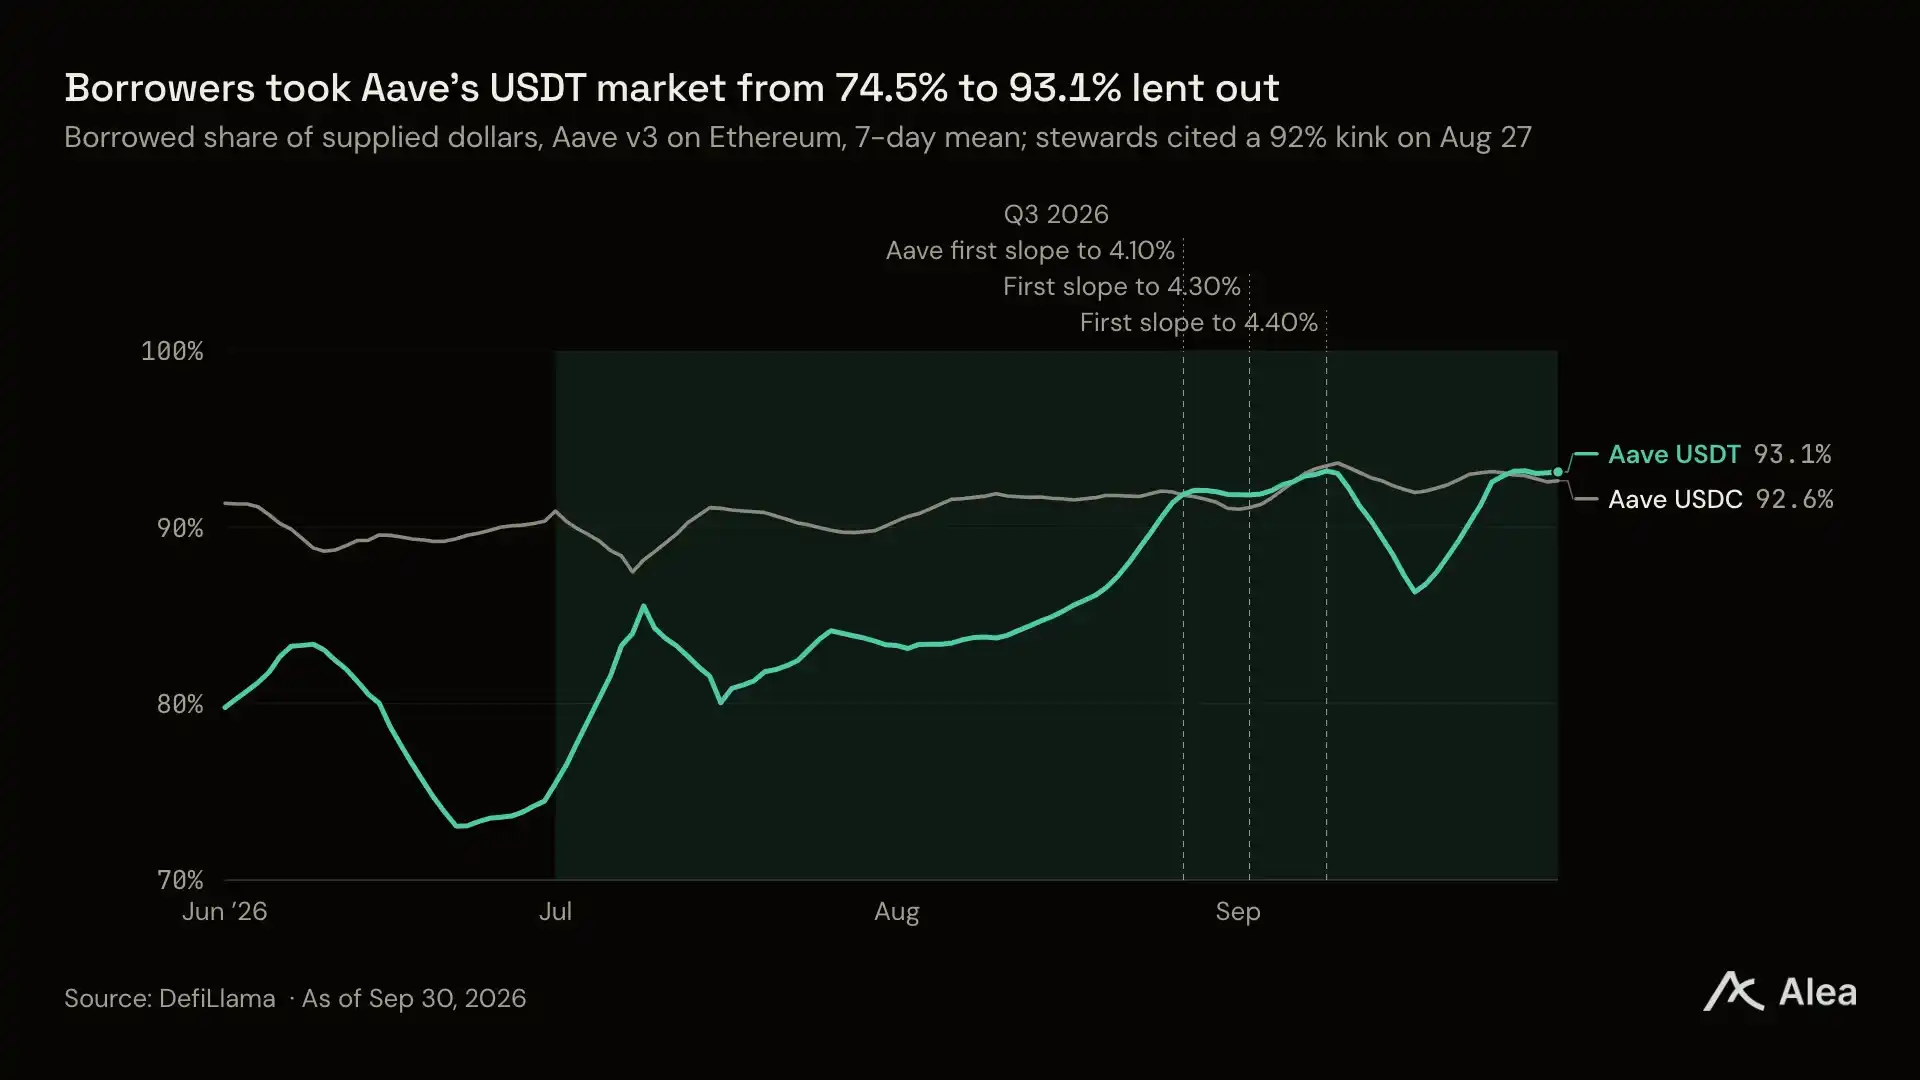
Borrowing costs rose through the quarter. By late August, utilization in Aave’s Ethereum USDT market had moved above 92%, the inflection level cited by Aave’s management team on Aug. 27, while USDC utilization was also elevated. The team raised the first-slope rate curve for both markets on Aug. 27, then again on Sept. 2 and Sept. 9, pushing rates from 4.00% to 4.40% in 13 days.
USDT borrowing had already been rising for two months before the first increase. The three step-ups followed that move. Higher rates improved depositor returns and drew new capital in. Aave’s Ethereum USDC and USDT markets added a net $470 million during the quarter. Between Aug. 28 and Sept. 13, deposits rose by $355 million and borrowing increased by $185 million. On Sept. 15, TokenLogic paused further first-slope increases and proposed cutting USDT’s target share from 94% to 93%, calling it a temporary measure linked to USDe debt migration.
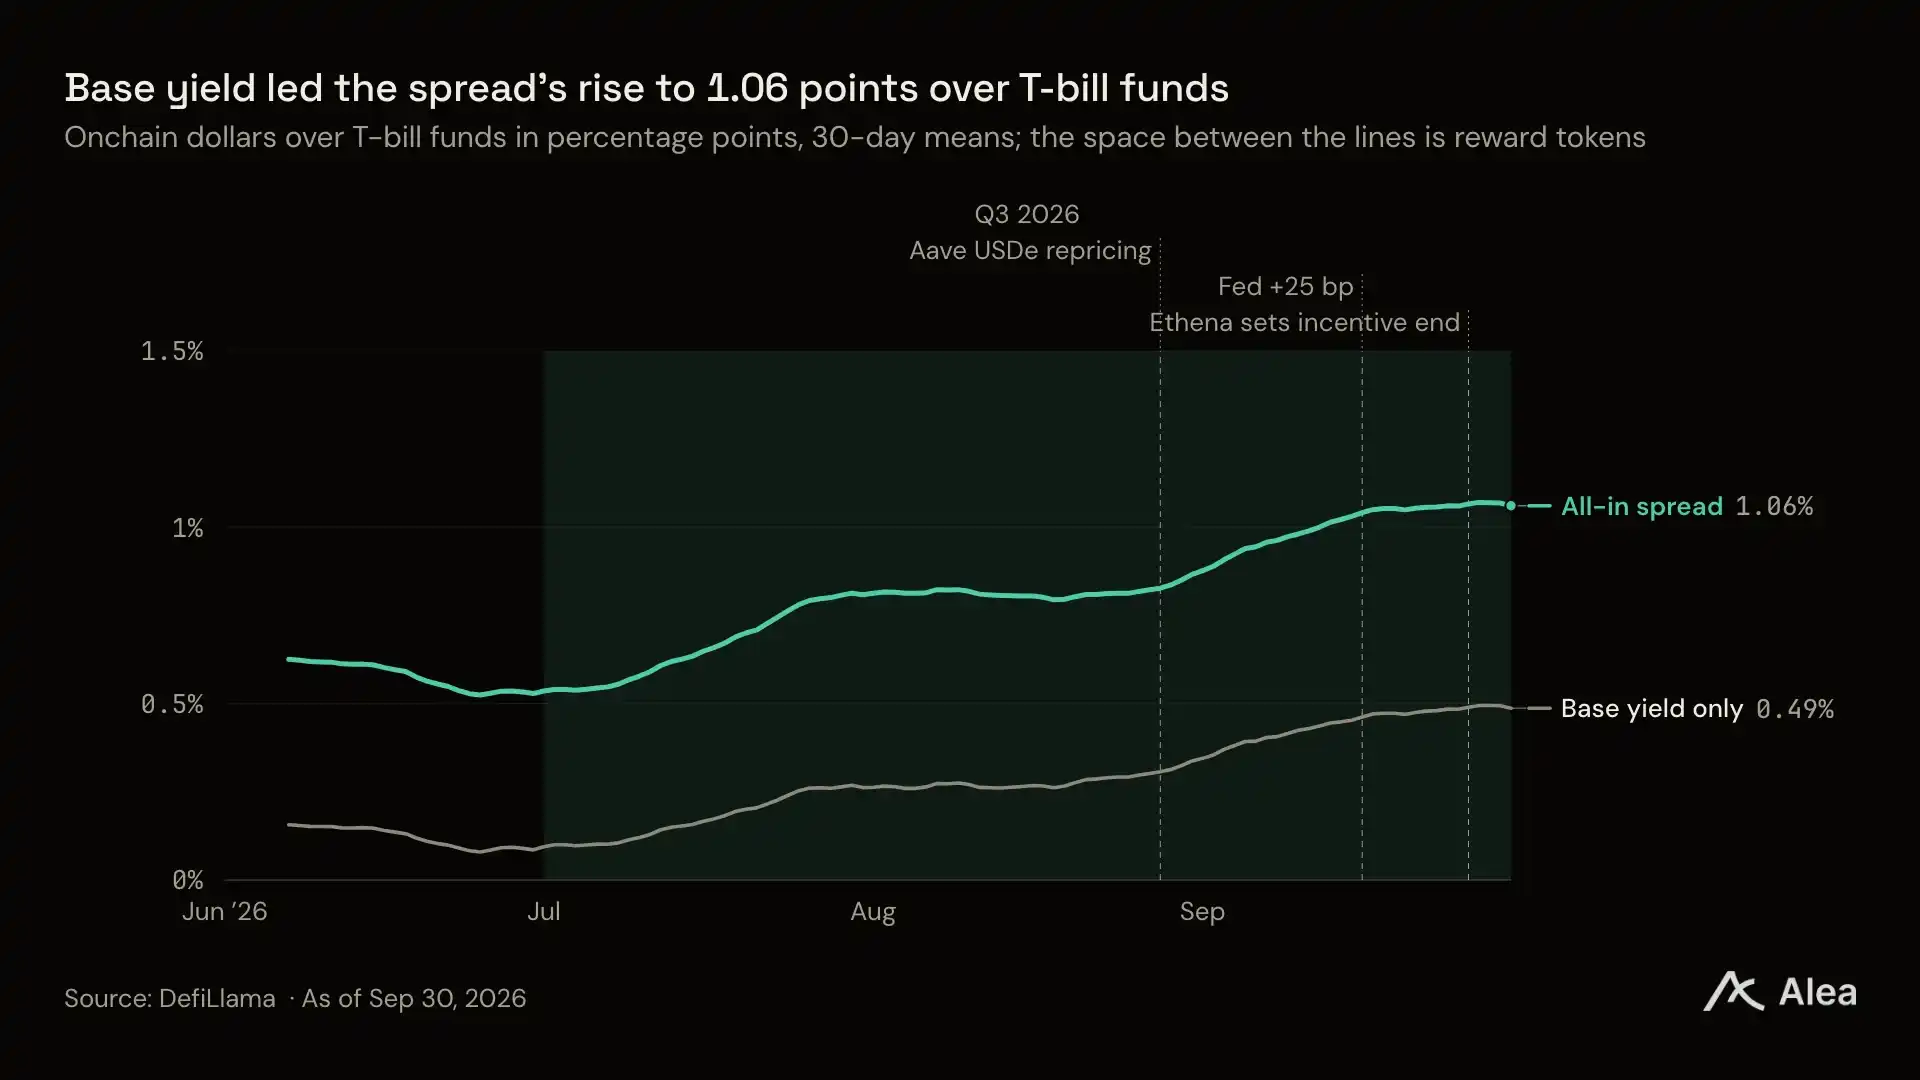
Aave’s rates were still below Treasury funds in early July, which left Aave v3 trailing Treasury funds by $9.3 million on base yield for the full quarter.
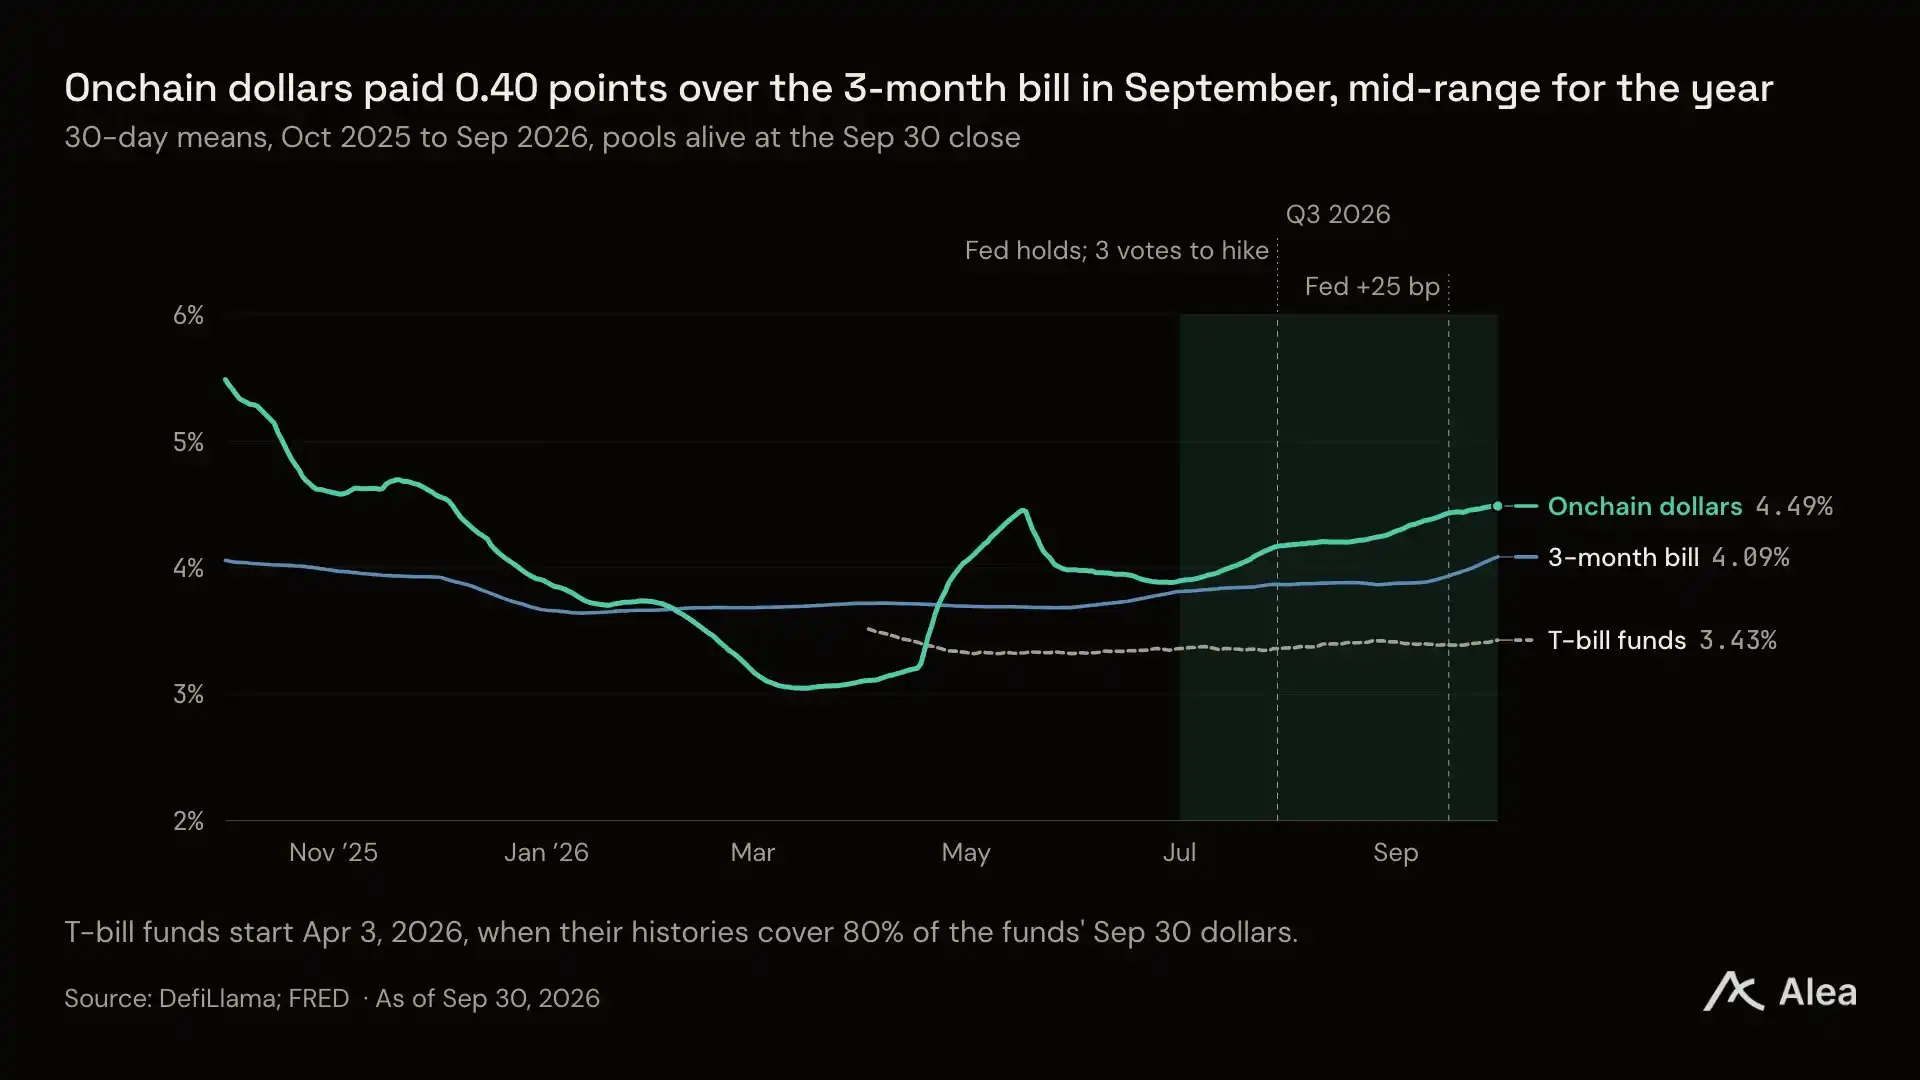
A major part of the wider spread came from a dull benchmark. The 30-day average yield on 3-month U.S. Treasuries rose by 0.28 percentage point during the quarter, while tokenized Treasury funds rose only 0.07 percentage point. That 0.21 percentage point lag in transmission was described as the main driver of spread expansion. After a July meeting that held rates unchanged despite three votes for a hike, the Treasury market had already moved higher before the Federal Reserve raised rates by 25 basis points on Sept. 16.
At the same time, total assets in tokenized Treasury funds fell from $9.9 billion to $8.6 billion, mainly because of redemptions from Circle USYC on BNB Chain, BlackRock’s BUIDL on Ethereum and one Centrifuge fund. BlackRock still launched two new stablecoin reserve funds on Aug. 3.
Among pools that were still active at quarter-end, the spread of onchain dollars versus Treasuries had swung from 1.43 percentage points above Treasuries in early October 2025 to 0.65 percentage point below Treasuries in March 2026. September’s 0.40 percentage point reading sat in the middle of that range. Looking only at base yield, onchain dollars paid 3.92% in September, 0.17 percentage point below Treasuries. The entire lead over Treasuries came from reward tokens.
Across pools that existed in both periods, the spread versus Treasury funds widened from 0.52 percentage point to 0.90 percentage point. New pools supplied the rest of the increase. Since April, the market had reached a similar level only once, in mid-May, when the spread peaked at 1.13 percentage points.

High-yield pools lost assets while lower-yield pools attracted inflows
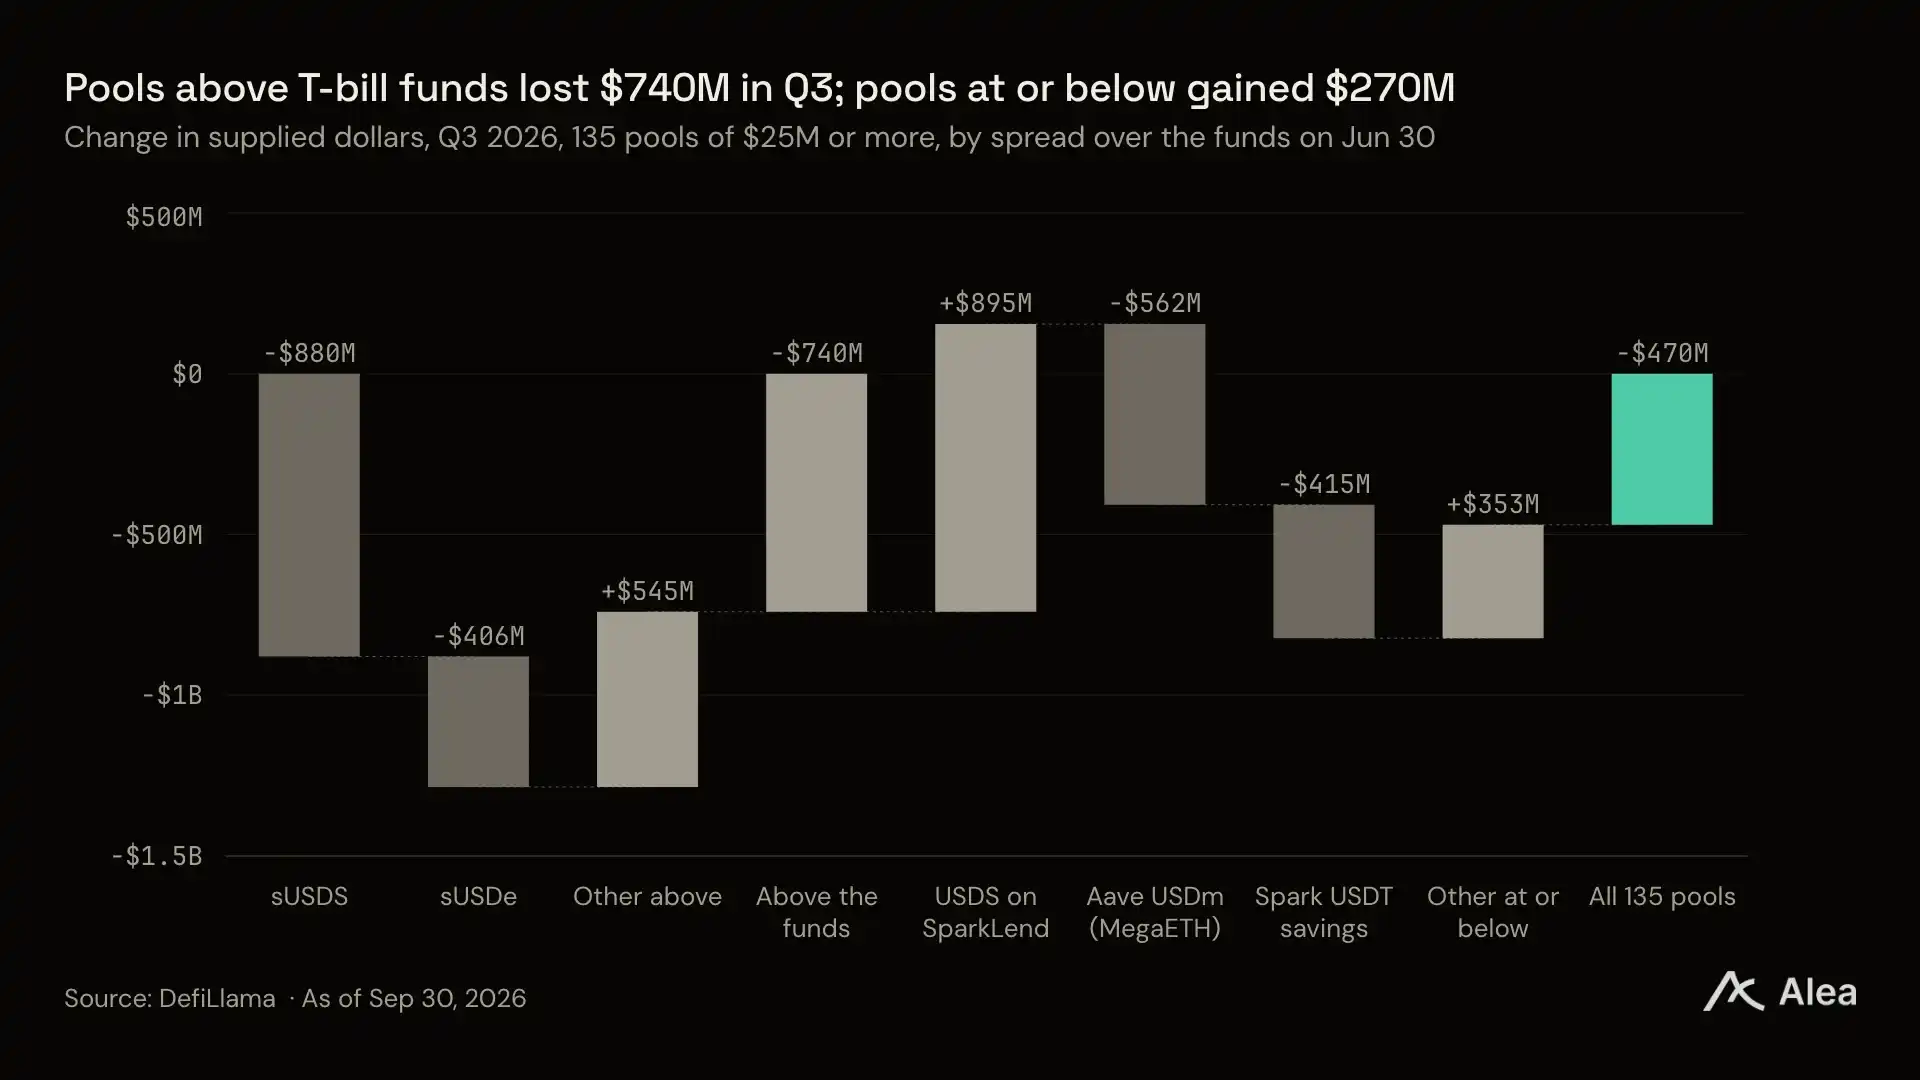
At the pool level, capital was not highly sensitive to spread ranking. Across 135 pools that were open in both periods and had at least $25 million in assets, the rank correlation was only 0.19. In dollar terms, though, two large redemptions changed the pattern. Pools yielding more than Treasury funds as of June 30 saw $740 million of outflows, while pools yielding at or below Treasury funds posted $270 million of net inflows.
Two high-yield pools, sUSDS and sUSDe, accounted for much of that move, shrinking by a combined $1.29 billion. Other pools in the same group still added a net $545 million, led by the Steakhouse Sirloin USDC vault on Base, Aave’s USDe market on Plasma and USD.AI’s sUSDai on Arbitrum. Reward tokens paid for about half of Sirloin’s yield and most of the Plasma market’s yield. By asset type, USDT deposits fell by $1.18 billion on the same basis, while USDC deposits increased by $630 million.
SparkLend’s USDS market drew the most money even though it paid roughly 1.2 percentage points less than Treasury funds. On the other side, Aave’s USDm market on MegaETH, which was driven mainly by looping leverage, and Spark’s USDT savings vault lost a combined $977 million.
For the full quarter, sUSDS shrank by $880 million, with most of the decline coming in July when Sky kept its rate fixed at 3.60%. One day alone, July 13, saw $523 million leave the pool. The rate was cut to 3.52% on July 23, then raised back to 3.60% on Sept. 3. Galaxy deposited $100 million into sUSDS on Sept. 23 and accepted it as loan collateral. Spark’s savings vaults lost $651 million, mostly from the USDT vault, while SparkLend’s USDT market fell by $244 million. Spark lifted the USDT vault rate from 3.25% to 3.5% on Sept. 10, just above Treasury funds. SparkLend’s USDS market, also within the Sky ecosystem, grew by $895 million.
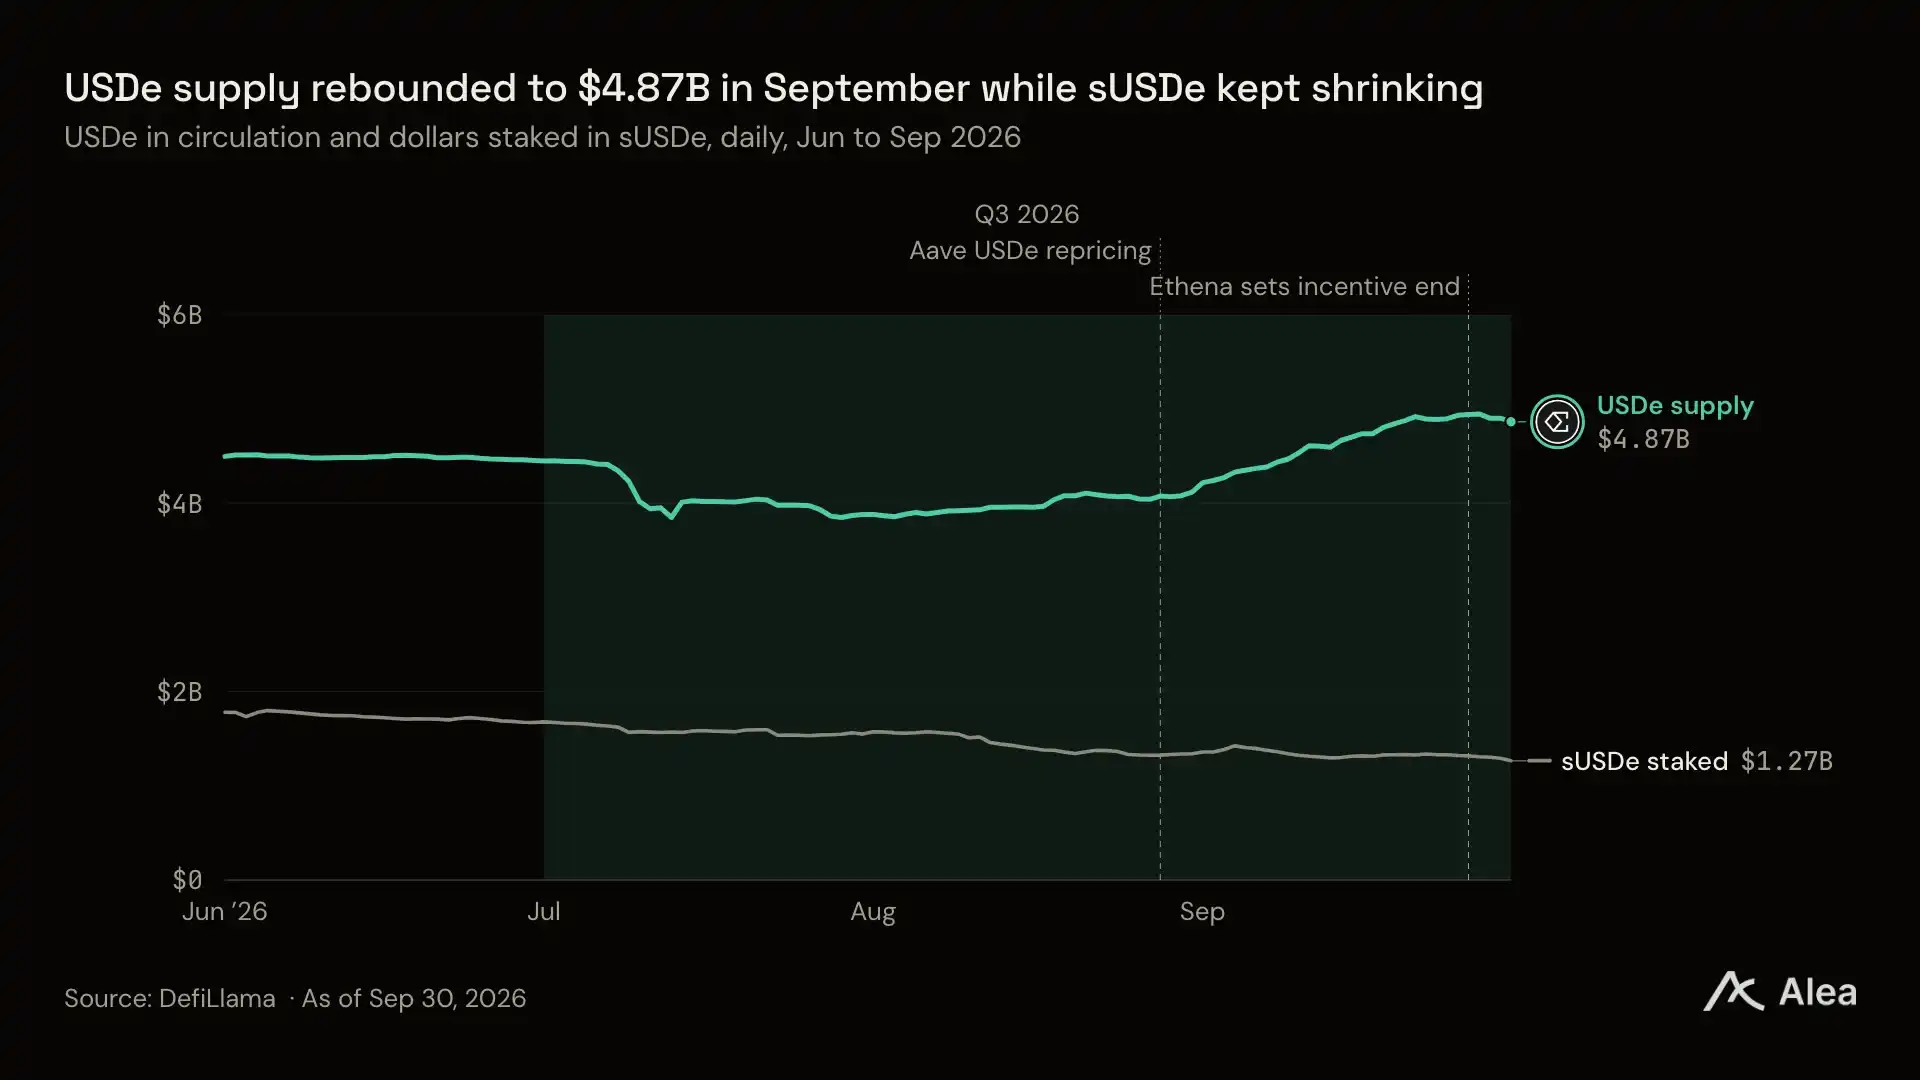
USDe supply recovered its July losses by mid-September, but dollars staked in sUSDe hit a quarter-end low of $1.27 billion. Ethena’s sUSDe pool kept shrinking even as its own 30-day yield rose from 3.86% to 4.23% by late August. Aave’s base borrowing rate for USDe reached 6.3% on Sept. 15. USDe supply dropped from $4.45 billion to $3.85 billion in July, then rebounded to $4.87 billion by Sept. 30, yet sUSDe continued to contract. Aave’s USDe markets on Plasma and Ethereum expanded by $378 million over the quarter.
ENA holders unanimously passed the fee switch proposal on Sept. 2. Under that plan, when USDe supply reaches $7.5 billion, the fee switch would turn on and direct 5% of net revenue to ENA buybacks. The buyback share would rise in steps as supply grows, reaching 25% once supply hits $25 billion. The report also noted that Ethena ended token incentives for USDe on Sept. 30, four weeks after ENA holders approved the fee switch.
Spread widened for large positions while the edge for smaller capital narrowed
Position size mattered. On June 30, a $1 million position yielded 2.09 percentage points more than a whale-sized position. By quarter-end, that gap had narrowed to 1.49 percentage points. The report defined core pools as pools with at least $100 million in assets, more than six months of history, and base yield accounting for at least 80% of total yield.
The sharpest change came at the $1 billion whale level. Its spread over Treasury funds rose from 0.69 percentage point in June to 0.97 percentage point by quarter-end. Alea said the move reflected repricing in core allocations used by very large capital. Maple’s USDC pool, sUSDe and Aave markets all paid more in September than they had in June.
By quarter-end, a $1 billion portfolio still held a 0.97 percentage point spread. According to the report, pool yields would need to fall by about 22% across the board to erase that premium. At that spread, $1 billion of capital would generate an extra $9.7 million in annual net income.
Maple led native base yield while Aave relied on incentives to close the gap
Among the six largest protocols by supplied capital, Maple delivered the highest pure base yield above Treasury funds without using reward tokens. Including incentives, Morpho vaults paid $15.8 million more than Treasury funds, but only $3.4 million of that came from native base yield. Aave v3 trailed Treasury funds on native base yield and then moved ahead overall once reward tokens were included. SparkLend remained behind Treasury funds even after incentives.
In the report’s chart, the x-axis showed base yield paid by borrowers to depositors above Treasury funds, and the y-axis showed yield paid through reward tokens. Maple stood by itself on the far right, leading with zero reward tokens and $14.4 million of excess base interest.
Four of the six major protocols outperformed Treasury funds on every day of the quarter. Aave v3 beat Treasury funds on 63% of trading days, including an uninterrupted stretch from Aug. 19 to Sept. 16. SparkLend managed that on only 4% of days. SparkLend’s main USDS market kept 31% of reserves idle, and reward tokens made up 34% of the yield it actually paid out.
New chains pulled in liquidity as looping leverage broke down on MegaETH
The report also tracked liquidity migration across chains. Robinhood Chain started from zero with its July 1 mainnet launch, while total value locked on Monad more than doubled. Aave deployed on Monad one day after launch and secured a one-year $15 million incentive commitment from the Monad Foundation. Most of Monad’s incremental capital came from those new markets. On Sept. 11, Aave’s management team raised the first slope on Monad to 5.00%.
MegaETH moved the other way. Aave’s looping USDm market on the chain collapsed from $568 million in supplied assets to $6 million. Net deposits after borrowing fell from $101 million to $22 million. Most of the money left on July 9 and 10, when a large forced unwind hit leveraged stablecoin arbitrage tied to Ethena. Circle’s Arc chain launched its mainnet on Sept. 16 with Aave V4 and Morpho integrated on day one. Because its pools opened only in the final two weeks of the quarter, their full returns were not yet captured in quarterly statistics.
Monad pools peaked at $995 million on Aug. 18 and ended the quarter at $871 million. Robinhood Chain climbed steadily through September, while MegaETH was drained in July.
Robinhood Chain’s $566 million of sticky capital sat mainly in the Earn vault, which focused on bridge financing for Ethena and Maple positions. Its lending market for USDe held $342 million in late September, with borrowing rates near 4%. A 5% incentive provided by Ethena on USDe collateral was enough to cover financing costs, but that token program formally ended on Sept. 30.
Reward tokens accounted for 45% of total pool yield on Robinhood Chain, 22% on Monad and 11% on Ethereum mainnet, according to the report.
Managed vaults took in net inflows as regulatory and governance risks surfaced
Across all chains, selected managed vaults recorded $781 million of net inflows on a like-for-like basis. Coinbase Lend crossed $500 million in early September through Steakhouse vaults on Morpho. Uniswap launched Earn, a vault yield product run by Gauntlet, in late July. Two early Steakhouse USDC vaults on Base lost $312 million, with $213 million of that on July 29 when Steakhouse moved assets into a second version. The new Sirloin vault that received the migration brought in $341 million net.
Regulatory and governance risks also moved closer to the market. SEC Commissioner Hester Peirce said on July 22 that automated vaults could fall under securities law depending on their structure and operating model. On Aug. 23, a malicious governance proposal took control of Term Finance’s Meta vault and caused roughly $8.5 million in losses. During the incident, about $6.8 million was urgently withdrawn from Morpho’s Parity Core ETH vault after Term’s ETH Meta vault had placed part of its assets there.
Maple held close to 4.8% through redemptions
Maple outperformed Aave’s USDC market throughout the quarter, with the spread standing 1.38 percentage points higher by quarter-end. Morpho vaults only managed a brief overtake in August through reward tokens.
Maple focuses on what the report described as fixed-rate, overcollateralized commercial loans to institutional borrowers. Its three dollar pools beat Treasury funds on every one of the quarter’s 92 days without any reward token support. Deposits still saw two notable rotations. The syrupUSDC pool lost $872 million from its July 15 peak to July 24, yet its base rate stayed near 4.8%. It ended the quarter at $2.87 billion, down $141 million from June 30.
Over the full quarter, syrupUSDT shrank by $434 million, mostly in September, while syrupUSDG, which qualifies as collateral in Earn vaults, expanded to $441 million. The three major pools together declined by a net $213 million. A Sept. 17 memorandum added three new strategies: direct lending backed by rated securities, asset-backed securitization and cash-and-carry basis trading. Until enough live history is built, each strategy is capped at 5% of total deposits.
Withdrawals are normally instant, and the terms set a maximum withdrawal period of no more than 30 days. syrupUSDT faced $313 million of redemptions between Sept. 5 and Sept. 18, concentrated on Sept. 9, Sept. 11 and Sept. 17.
Base yield was the durable driver of Q3 spread expansion
The report’s closing point was that onchain dollar spreads doubled in the third quarter, and the most durable part of that move came from base yields moving closer to Treasury benchmarks. Through lending-rate resets and the arrival of higher-paying new pools, base rates improved by 0.19 percentage point relative to benchmark Treasuries themselves. At the same time, the 0.21 percentage point lag in Treasury fund transmission should gradually fade as those funds rotate into newly issued higher-yield securities.
Even so, reward tokens still made up 60% of onchain dollars’ excess spread. Alea added that this part of the return remains uncertain because protocols can stop incentives unilaterally, as Ethena did on Sept. 30. Even after stripping out all token rewards, onchain dollars still held a 0.49 percentage point native base-yield premium over tokenized Treasury funds, according to the report.
The report was written by Alea Research and translated by TechFlow.