
Micron Technology (MU) is scheduled to report fiscal 2026 fourth-quarter results after the U.S. market closes on Sept. 30, which falls in the early hours of Oct. 1 in Beijing. The company previously guided for $50 billion in revenue, plus or minus $1 billion, and non-GAAP earnings per share of $31, plus or minus $1. Wall Street consensus stands at about $51.07 billion in revenue and adjusted EPS of roughly $31.52, representing year-over-year growth of about 351% and 938%, respectively.
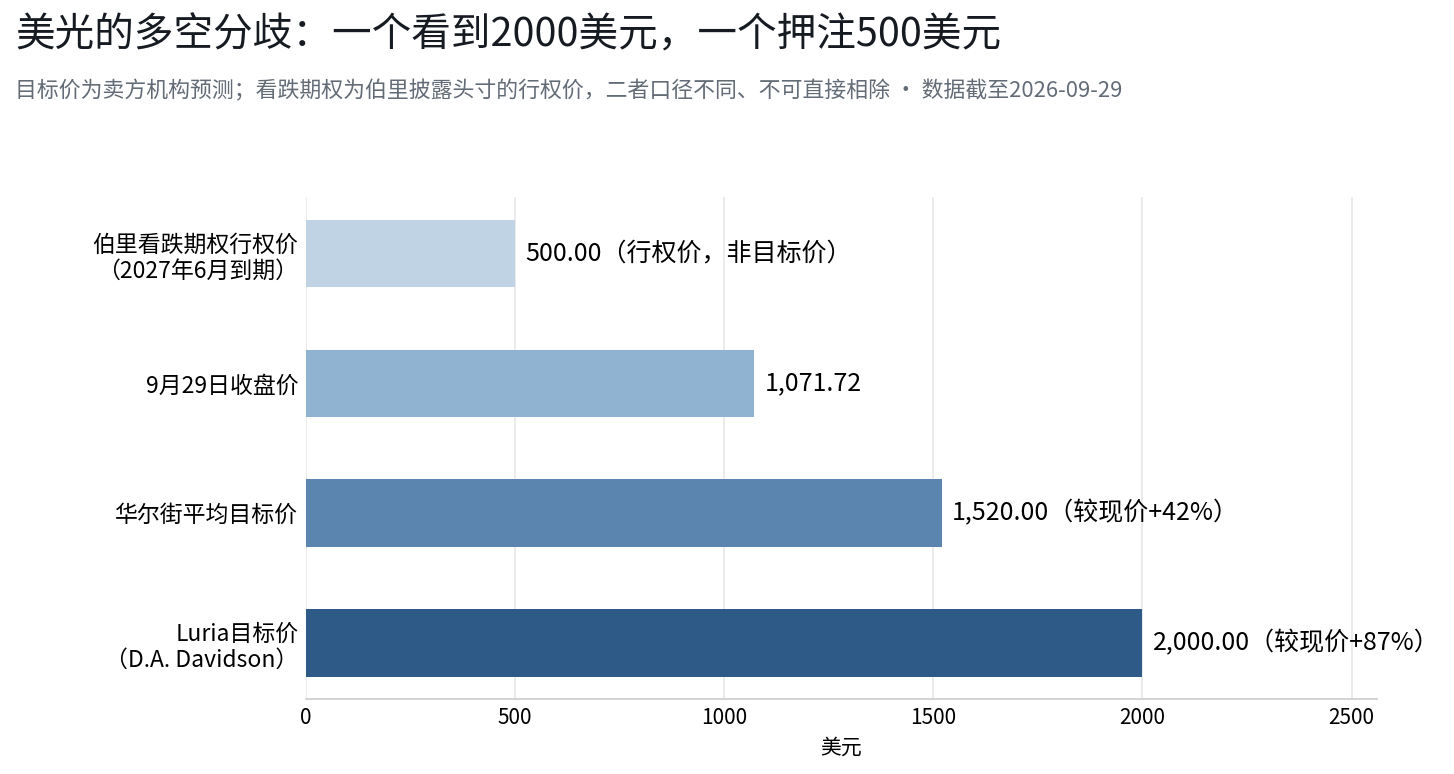
The market is not focused only on the quarter’s headline numbers. The bigger argument is whether the improvement is already reflected in the stock and how long the current memory cycle can last. On one side, D.A. Davidson analyst Gil Luria reiterated a $2,000 price target ahead of the report, implying about 87% upside from Micron’s Sept. 29 close of $1,071.72. On the other, Michael Burry replaced his Micron short position with put options expiring in June next year with a strike in the $500 range.
Quarterly expectations remain strong
Micron’s own guidance calls for $50 billion in revenue and non-GAAP EPS of $31, but several institutions are looking for more.
- Citi expects $51 billion in revenue and EPS of $31.45.
- Goldman Sachs expects $51.9 billion in revenue and EPS of $32.54.
- UBS is the most aggressive, with $52.4 billion in revenue and EPS of $32.50.
- JPMorgan analyst Harlan Sur expects $51.4 billion in revenue, gross margin of 86.2%, and EPS of $31.73.
JPMorgan’s estimates for revenue, gross margin, and EPS all sit above broader market consensus.
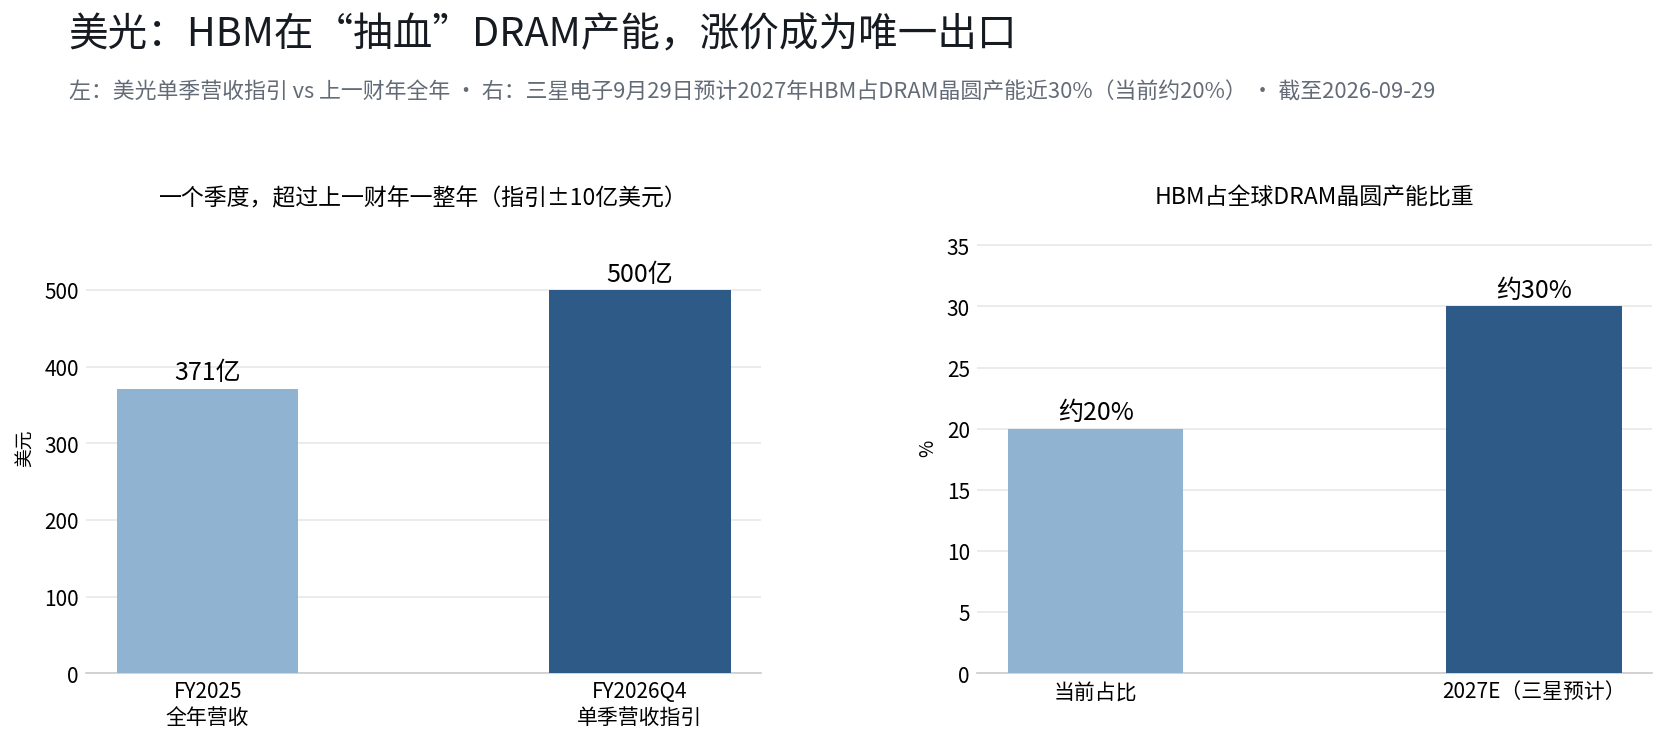
The scale of the quarter is part of the story. Micron’s full-year revenue for fiscal 2025 was about $37.1 billion, according to the figures cited in the article. That means expected revenue for a single quarter now exceeds the company’s total revenue for the prior fiscal year.
Three questions sit at the center of the report: whether Micron can beat already elevated expectations again, when HBM4 volume production will begin to make a visible contribution to revenue, and what conventional DRAM pricing and capital spending plans will say about the industry outlook.
Morgan Stanley is more conservative than most. It expects revenue of $50.024 billion, up 342.1% year over year, gross margin of 86.4%, and EPS of $31.2, below the market expectation of $31.49. Even so, the bank still expects Micron to raise guidance, though by less than in prior quarters.
HBM expansion is pulling capacity away from conventional DRAM
One of the main structural issues in the memory market is that HBM capacity expansion may squeeze supply for traditional DRAM, even as demand for conventional DRAM remains in place.
Samsung Electronics executive vice president Kim Taewoo said on Sept. 29 that HBM is expected to account for nearly 30% of global DRAM wafer capacity by 2027, up from about 20% now. Soochow Securities laid out a more detailed path, estimating that HBM’s share of total DRAM capacity will rise from 12.3% in 2024 to 17.1% in 2025, 20.8% in 2026, and 22.5% in 2027.
HBM4 is especially capacity-intensive. The article says HBM4 requires about three times the wafer capacity of general-purpose DRAM. A full-scale HBM4 ramp would therefore reduce the amount of capacity available for conventional DRAM. Adata chairman Chen Libai said the three original manufacturers have already sold out their 2027 capacity, with HBM and AI server applications consuming about 70% of DRAM output.
Micron stands out because it is the only one of the three major memory manufacturers with meaningful exposure to both HBM and conventional DRAM. Samsung and SK hynix derive a larger share of revenue from HBM, while Micron still has a larger traditional DRAM and NAND business. That leaves its earnings more exposed to changes in conventional DRAM pricing.
BMO channel checks suggest server DDR5 price increases may offer more upside surprise than HBM. The same checks indicate HBM3E and HBM4 prices are likely to rise sequentially, while consumer memory demand remains weak.
Micron’s own HBM4 ramp is moving faster
Micron’s internal progress is also accelerating. Its 12-high HBM4 designed for Nvidia’s Vera Rubin platform entered volume production and shipment in the first quarter of 2026. The company said energy efficiency improved by more than 20% compared with HBM3E, and cumulative shipment revenue has already exceeded $1 billion.
Chief executive Sanjay Mehrotra said on the June earnings call that the production ramp for 12-high HBM4 is running at about twice the speed of the 12-high HBM3E ramp. The article also cited industry information saying Micron’s monthly HBM capacity could double to 100,000 wafers before year-end, while HBM4’s share of Micron’s HBM output may rise from about 20% to 30% at the start of the year to as much as 50% by year-end.
Why Gil Luria is holding a $2,000 target
Luria’s $2,000 target is near the top end of Wall Street. He raised his target from $1,500 to $2,000 in June, arguing that Micron had entered what he called the period of best visibility in the semiconductor industry and that tight memory supply and demand would last at least through 2027.
His case has three main parts.
First, he argues that HBM pricing is still heavily shaped by supply constraints, while demand remains strong and new supply will take time to arrive.
Second, he says Micron’s earnings visibility is extending. HBM orders are usually locked in more than a year in advance, which means a meaningful share of 2027 revenue can already be forecast with some confidence.
Third, he believes the market is changing how it values Micron. In his report, he wrote: 「This memory cycle is a complete cycle across GPU, CPU, and memory. AMD and Intel trade at 40x to 60x earnings, while Micron trades at only 7x.」
Luria also pointed to a recent change tied to Meta’s Muse. He said: 「Just a few weeks ago, we were worried that memory demand tied to Meta could weaken. Now that outcome looks far less likely.」
The gap between the average Wall Street target of $1,520 and Luria’s $2,000 target, nearly $500, shows how little agreement there is on whether Micron should be treated mainly as a cyclical stock or as a growth stock.
JPMorgan kept an Overweight rating and a $1,540 target, saying revenue, gross margin, and EPS for the quarter should all beat consensus and that slower price increases reflect sales timing rather than weaker demand. UBS maintained a $1,625 target, said DRAM should remain undersupplied at least through the second quarter of 2028, and expects Micron to begin share repurchases in the second quarter of fiscal 2027 at an initial pace of about $20 billion per quarter.
Burry’s case is built on a return to the cycle
Michael Burry is taking the other side.
According to China Securities Overseas Information, Burry said in his latest weekly note to investors that he had replaced a large portion of his outright short positions in major AI stocks with put options. In Micron’s case, the short exposure was replaced with put options expiring in June next year with strikes in the $500 range. His explanation was direct: 「Because the timeline has shortened, I want more leverage in my short positions.」
Burry’s view is that the structural shortage in memory chips created by the AI buildout is temporary and that the industry will eventually return to its traditional pattern of alternating booms and busts. He said: 「Within the next two years, as production catches up with demand, this shortage will disappear, and memory chips will enter a downcycle again.」
Citi analysts also warned ahead of earnings that DRAM and NAND pricing will slow over the next few quarters. Bernstein expects the memory cycle could begin to “normalize” in 2028. The article notes that some memory stocks have historically seen sharp volatility or pullbacks even during periods of strong earnings, though past performance does not determine future results.
Three risks the market is watching
HBM4 yield ramp
HBM4 is still in the early stage of mass production. Yield is below the prior-generation HBM3E, and the manufacturing process consumes more DRAM capacity. If yield improvement comes in slower than expected, Micron’s HBM shipment pace could be affected. Investors are also watching whether capacity ramps as planned, how customer qualification progresses, and when revenue contribution becomes visible. Because large-scale shipments on downstream platforms may be concentrated in 2027, the article says HBM4’s more meaningful revenue contribution may fall mainly in the next fiscal year.
Conventional DRAM pricing and capital spending
Bank of America analysts said the key data point is Micron’s outlook for fiscal 2027 gross margin and capital expenditure. If gross margin can hold around 85%, forecasts for fiscal 2027 EPS of $150 to $200 would gain support. Capital spending is expected to land in the mid-to-high $40 billion range, with a significant portion allocated to cleanroom construction rather than immediate output additions.
The article also notes that Micron shares could still swing even if actual results beat expectations, if the market’s view of the memory cycle changes.
Macro rates pressure
Micron fell 2.61% on Sept. 28, while the Philadelphia Semiconductor Index dropped 1.61% the same day. The article links that move to a surge in U.S. Treasury yields that weighed on high-valuation technology stocks. If the Federal Reserve raises rates again in October, high-beta memory names could face additional valuation pressure in a tighter liquidity environment.
Beyond the quarter, the market wants Micron’s 2027 view
Expectations for the report are already high. HBM pricing, conventional DRAM supply and demand, and AI capital spending are all central to the debate, but the market may care even more about management’s view of 2027 and how investors choose to frame Micron’s future business mix: cyclical, structural growth, or some combination of both.
Luria’s $2,000 target and Burry’s put options capture that divide in the clearest possible way. The earnings release and management outlook should give the market more information to price that disagreement.