


Sentora co-founder Jesus Rodriguez argues that the RWA conversation often starts with a simple idea: take a Treasury bill, a fund share, a stock, an invoice, a megawatt-hour, or an hour of GPU compute, then mint a token that represents it onchain. Useful, yes. Transformational, not yet.

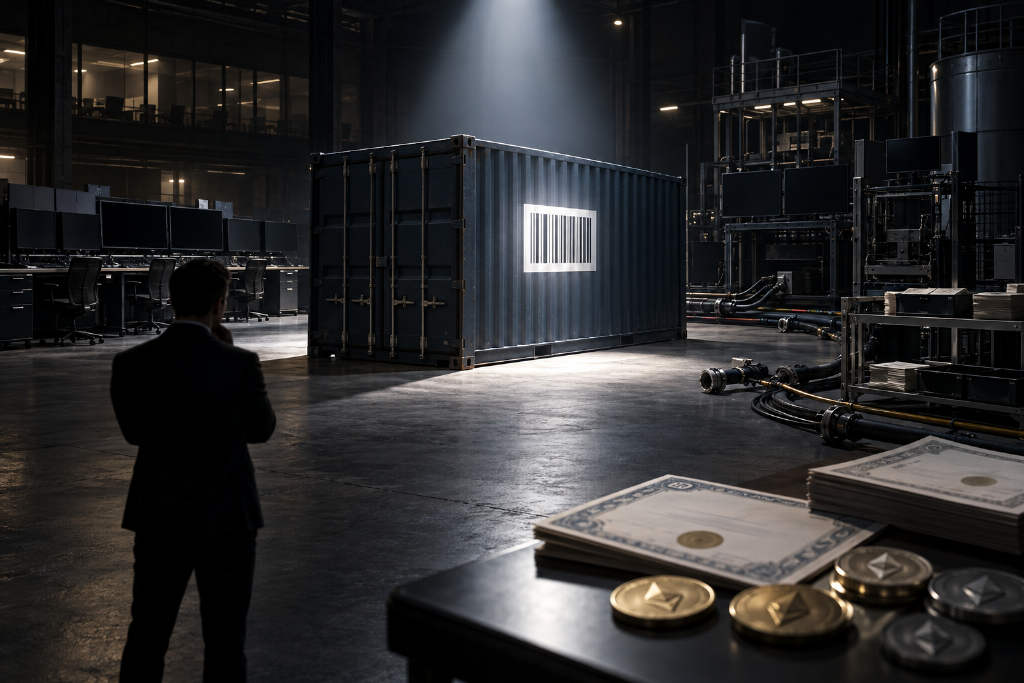
His comparison is blunt. Tokenization on its own is like putting a barcode on a shipping container and then claiming global trade has been solved. A barcode makes the container identifiable and machine-readable, but it does not create ports, cranes, customs, insurance, financing, shipping routes, or buyers on the other side. In the same way, a token is only an addressable claim on rights. DeFi is the market operating system.
Tokenization represents rights, while DeFi creates utility
Rodriguez says the real question is not how many assets can be put onchain. The question is how many of them can be valued, financed, hedged, traded out of, and resolved through losses under stress, without forcing participants to coordinate every transaction offline.
He points to the history of mortgage markets. Scale did not come from turning paper records into electronic ones. It came from the machinery built around the asset class: underwriting, servicing, securitization, credit ratings, warehouse financing, repo, hedging, clearing and settlement, and rules for loss allocation. RWA, he says, needs the same kind of evolution.
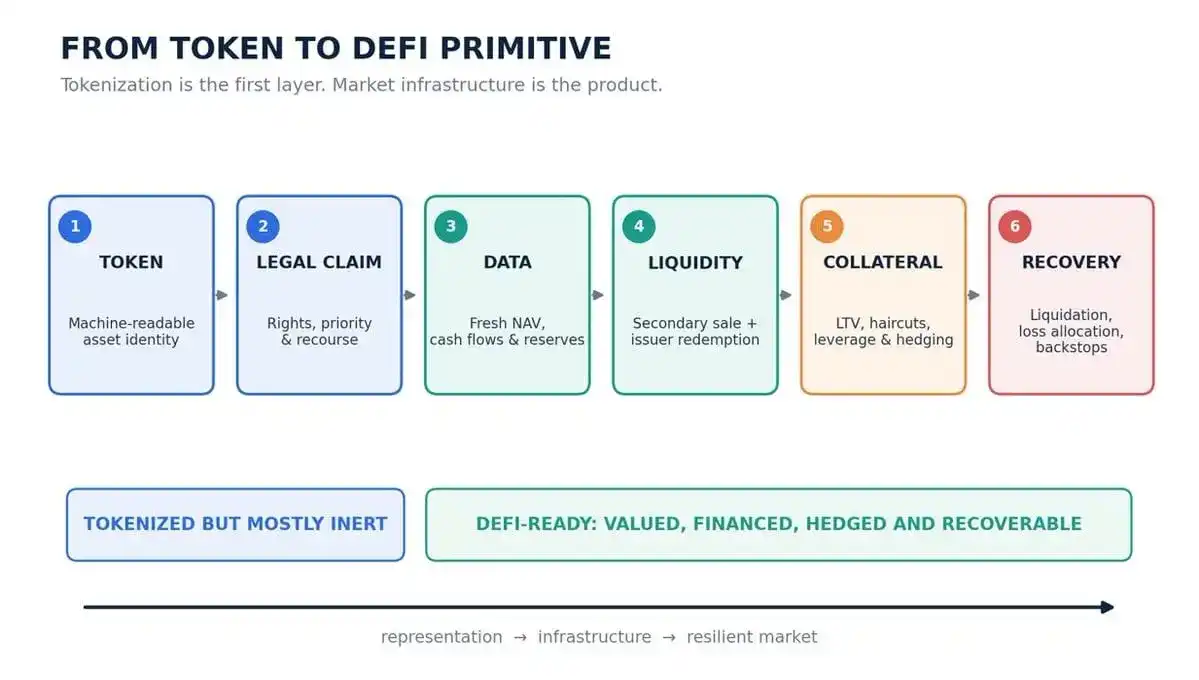
In his framework, an asset that can actually fit DeFi needs six layers:

- legally enforceable rights,
- reliable data sources,
- clear transfer and redemption rules,
- executable secondary-market liquidity,
- collateral parameters that match real-world behavior, and
- a credible liquidation and loss-resolution path.
Most tokenization projects, he argues, stop short of the last step. He offers a simple maturity test built around three questions: What is the asset worth right now? Can the protocol exit and realize value right now? If both judgments are wrong, who takes the loss? Only when a smart contract can answer those questions deterministically does an RWA become a real financial building block. Before that, it is mostly digital packaging.
RWA runs on several clocks at once
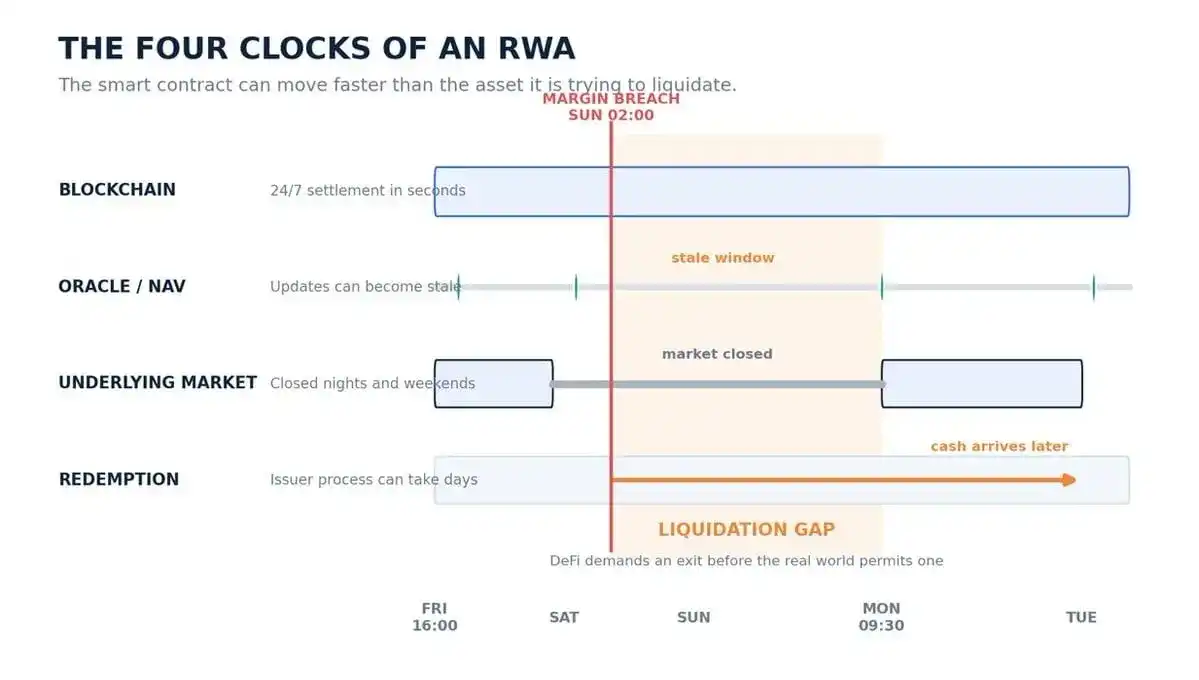
The deepest technical tension, in his view, is that RWA operates across multiple time systems. A blockchain settles in seconds and runs 24/7. An oracle may update prices hourly or daily. The underlying traditional exchange closes at night and on weekends. Custodians follow banking hours. Redemption may take 1 day, 5 days, or even 30 days.
Use that kind of slow-moving asset to support fast-maturing DeFi liabilities such as stablecoin borrowing, and the result is maturity transformation. Rodriguez notes that this model has been useful for centuries. Banks run on it. But the risk has to be priced correctly.
He sketches a weekend scenario: at 2 a.m. on Sunday, the asset hits a liquidation threshold. The smart contract can seize the token immediately, but the real-world market does not open until Monday, and the issuer may not process redemption until Tuesday. Onchain liquidation is done. Offchain disposal has barely started. That gap is the liquidation shortfall.
From there he reaches a counterintuitive conclusion. Even a low-volatility tokenized Treasury can be riskier as collateral than a more volatile crypto-native asset. ETH moves sharply, but it trades around the clock. An RWA may look stable only because there has been no fresh price mark for many hours. A smooth price can signal safety, or it can be stale data in disguise.

Liquidity is an exit channel, not a TVL figure
Rodriguez also pushes back on how liquidity is commonly described. Liquidity is not TVL. It is not the mere existence of a trading pair. It is not an issuer promise to redeem at NAV at some point in the future. Liquidity is the ability to convert a position into the settlement asset you need, within the time window your liabilities allow, and at an acceptable discount.
He compares it to a crowded theater. The size of the hall does not tell you whether people can get out safely in a fire. What matters is the width of the exits.
He says an RWA should have at least three exit routes: selling to other market participants, redeeming with the issuer, or borrowing against the asset to delay a sale. Each route comes with its own delay, capacity, access limits, and failure mode. A market maker willing to warehouse RWA inventory over a weekend is effectively bridging two financial clocks, and that balance-sheet service should be identified clearly and paid for accordingly.
That is why strategy models should estimate exit value under stress rather than rely on official book NAV. The relevant price is the one left after spreads widen, market makers cut inventory, redemption queues form, and stablecoin funding costs jump. The key question is not what the asset was worth yesterday. It is how much cash the position can actually be turned into before the protocol runs out of tolerance.
Leverage creates utility and fragility at the same time
Rodriguez writes that tokenization gets the headlines, but leverage is what creates economic utility. Homes become high-value collateral through mortgages. Treasuries become foundational market tools through repo. Stocks unlock more value once they support margin trading, borrowing, shorting, and hedging.

Once an RWA can be pledged to borrow stablecoins, it stops being just a tokenized object and starts functioning as balance-sheet infrastructure. That is also where hidden assumptions turn into realized losses.
Haircuts, he says, cannot be based only on historical volatility. They also need to reflect legal enforceability, oracle freshness, redemption delay, holder concentration, market-maker capacity, custodian risk, governance permissions, and correlation with the financed asset.
That leads to another result that may look odd at first glance: in some market conditions, a tokenized Treasury may deserve a lower collateral ratio than ETH. Not because the Treasury has higher economic risk in itself, but because its liquidation path is slower and less battle-tested. His formulation is simple: DeFi risk is not just asset risk. It is asset risk multiplied by market-structure risk.
RWA risk should be modeled as a graph of dependencies
On risk management, Rodriguez contrasts traditional finance with DeFi. Traditional systems often rely on periodic reports and manual escalation. DeFi needs something closer to an aircraft cockpit: continuous monitoring, explicit thresholds, and automatic response before the engine is visibly on fire.
For that reason, he says RWA risk should not be compressed into a single score. It should be modeled as a relationship graph. The nodes include underlying cash flows, legal entities, issuers, custodians, oracles, secondary markets, redemption mechanisms, stablecoin pools, lending protocols, governance keys, and backstop capital. The links between them show dependency.
Failures rarely happen in isolation. One custodian may serve several tokens. One oracle may feed multiple pools. One stablecoin may support a large set of leveraged positions. A small operational problem can travel through that graph and end as a liquidity crisis.
His proposed approach is to combine asset research, strategy construction, continuous monitoring, exposure control, and risk protection into a single operating loop. The system should keep watching redemption queues, market depth, position concentration, lending utilization, oracle deviation, reserve changes, cash-flow deterioration, and market-maker behavior. In his view, the first warning signs often appear offchain before they show up in token prices. Waiting for the price to fall is like checking the wiring only after smoke is already visible.
Treasuries are the entry point, not the destination
Rodriguez describes tokenized Treasuries as a natural starting point. They are standardized and easy to understand. Using a networking analogy, he calls them the ping packet of the RWA economy: a way to test whether custody, minting, redemption, compliance, pricing, and the full settlement chain can work end to end.
But a financial internet limited to short-dated Treasuries would still be narrow. He argues that more interesting frontiers lie in compute and energy assets.
Compute-based RWA can represent GPU hardware, lease receivables, prepaid compute, utilization-linked income, or revenue rights tied to data-center operators. Those assets carry a very different risk set, layered with equipment finance leases, commodity-style pricing, depreciation from technical iteration, and actual operating performance. A new chip generation can change the earnings curve of a GPU overnight. Its economic aging can move much faster than that of a physical building.
Energy assets come with their own identity problem. A token may represent infrastructure, a power purchase agreement, megawatt-hours of electricity, grid capacity, project income, or a green credit instrument. Each version needs its own oracle design and liquidation plan. DeFi can give slow, locally bounded traditional assets programmable income distribution, transparent collateral pools, global distribution, and dynamic financing tools, he writes, but the token has to map precisely to the underlying economics. “Backed by energy assets” is not, by itself, a risk model.
Tokenized stocks and perpetuals will be the biggest live test
Rodriguez says tokenized equities will become the largest real-world stress test because they connect two large systems at once: global stock ownership and crypto-native leverage.
The first issue is not which stock has been put onchain. It is what the holder actually owns. Direct equity ownership, economic rights, structured notes, and synthetic tracking products may move in similar ways, but they produce very different outcomes for voting rights, dividends, corporate actions, redemption rights, and bankruptcy treatment.
That leads directly to perpetual futures. In his view, tokenized spot equities and equity perpetuals should complement each other in the same way spot and futures markets do in commodities. Spot anchors ownership, dividends, settlement, and collateral. Perpetuals provide leverage, short exposure, hedging, and continuous price discovery. Together they allow forms of market expression that a single product cannot provide.
They also create tightly linked risks. He gives one example: tokenized stock is posted as collateral to borrow stablecoins, and the borrowed funds are then used to open a leveraged long in that same stock’s perpetual market. The underlying U.S. equity market is closed. Over the weekend, the token price falls, collateral value shrinks, perpetual liquidations begin, market makers pull back, and already thin spot liquidity pushes prices lower still.

The answer, he argues, has to come from system design: isolated margin domains, concentration caps, dynamic weekend haircuts, liquidity-aware oracles, circuit breakers, cross-market monitoring, and clearly defined backstop capital. Efficiency does not mean removing constraints. It means putting constraints where the system is most likely to fail.
Without DeFi, RWA still matters, but only up to a point
Rodriguez’s answer to the headline question is yes, but with limits. Tokenization can improve distribution, settlement, transparency, and investor access. The larger opportunity begins when assets enter an open, programmable capital market: they can become collateral, obtain financing, support hedging, and serve as building blocks for structured strategies.
In that framework, an RWA is not truly DeFi-ready when the token is minted. It is DeFi-ready when the market built around it can survive a stressed weekend. The next phase, he writes, is not about stacking more RWA logos. It is about building the operating layer that turns legally valid claims into resilient financial strategies.
His long-term vision is not “everything can be tokenized.” It is a system in which productive real-world assets can be addressed by software, capital can move continuously across asset classes, and risk can be managed at market speed. The token is only the barcode. The market is the machine that does the work.