


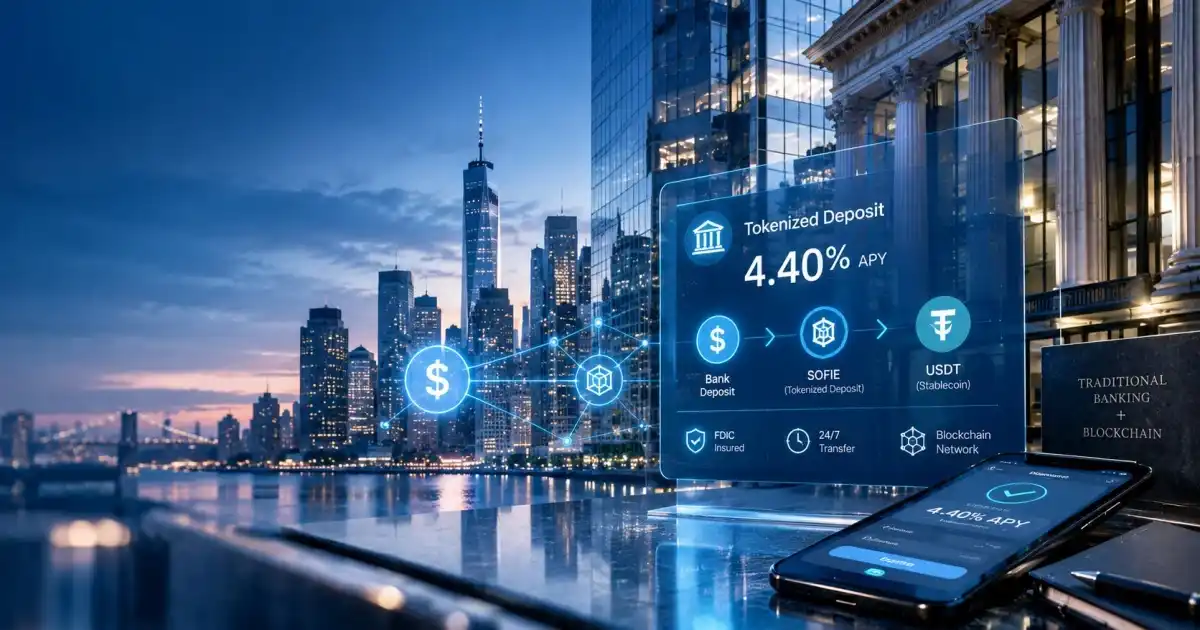
SoFi has started a phased rollout of SoFi Earn to eligible SoFi Crypto users. Under the company’s announcement, each unit of SOFIE represents $1 on deposit in a SoFi Bank account. Eligible users can receive a 4.40% annual percentage yield, then convert SOFIE on a 1:1 basis into the dollar stablecoin SoFiUSD to buy crypto through the SoFi app or move funds to supported external wallets.
The product is aimed at a familiar pool of money in crypto markets: dollars that are not actively being traded. Investors may be waiting for a better entry point, or they may be holding cash after closing positions and before the next bout of volatility. The money is idle from a trading standpoint, but it still carries liquidity and yield needs.
Traditional bank deposits can pay interest, but moving funds from a bank account to a trading platform, converting them into digital assets, and then sending them to an onchain wallet usually means dealing with several accounts and services. Stablecoins improve the portability of digital dollars on blockchain rails, yet that does not mean holders automatically receive deposit interest or bank deposit insurance. SoFi Earn is built around that gap.
The 4.40% figure is not a fixed promise. SoFi said the rate is based on the level published on Oct. 20, 2026, and may change over time. Fees may also affect actual returns. That leaves SOFIE to be judged on more than a headline APY. The real test is whether it can balance yield, access to funds, and ease of conversion.
SOFIE is not the same thing as a stablecoin
The most notable part of SOFIE is not simply that it uses a token format. It is the attempt to connect the legal character of a bank deposit with the transferability associated with blockchain-based assets.
According to SoFi’s product materials, SOFIE is a tokenized bank deposit backed by deposit liabilities at SoFi Bank. SoFiUSD, by contrast, is a U.S. dollar stablecoin intended for payments and transfers. The first can generate interest and, if eligibility requirements are met, may qualify for Federal Deposit Insurance Corporation, or FDIC, deposit insurance. The second is designed to maintain a 1:1 value relationship with the dollar and move across supported blockchain networks and wallets, but it is not a bank deposit and does not carry FDIC deposit insurance. The two can sit inside the same product flow, but they do not give holders the same rights.
That distinction helps explain why banks may choose tokenized deposits instead of relying only on stablecoins to expand digital asset services. For banks, deposits are not just a place where customers park money. They are also part of liability management and customer relationships. If a bank can add a tokenized form to an existing deposit business, it may be able to push funds into new digital use cases without fully stepping outside the traditional deposit system.
Tokenization does not erase risk. FDIC deposit insurance is generally calculated up to $250,000 per depositor, per insured bank, per ownership category. SOFIE balances must be aggregated with a user’s other insured deposits of the same ownership category at SoFi Bank, rather than receiving a separate $250,000 cap. Deposit insurance also mainly applies in covered situations such as an insured bank failure. It does not cover every market move, trading loss, or blockchain operational risk.
For users, the key question is not a broad one like whether a token is safe. It is what kind of asset they actually hold, who is responsible for repayment, and whether deposit protections still apply after a conversion takes place.
Competition is shifting from issuance to retention
The launch also reflects a change in how the digital dollar market is being contested. In the earlier phase of the stablecoin sector, attention centered on issuance scale, trading liquidity, exchange coverage, and onchain use. As stablecoins moved deeper into payments and settlement, another question came into view: why should users keep holding digital dollars over time, and what do they get while those funds are not being used?
SoFi Chief Executive Officer Anthony Noto previously discussed idle cash demand in crypto markets with Reuters. Citing Federal Reserve research, SoFi said about $64 billion in the stablecoin market sits in wallets with little trading activity, long periods of non-use, or idle balances, equal to about 21.2% of the overall market. That figure points to potential treasury-management demand, but it does not mean all of that money is ready to move into yield products, and it does not mean those assets can earn interest without taking on added risk.
Yield matters, but it is not the only factor. Holders also care about whether funds can move at any time, whether the conversion process is smooth, and whether fees are reasonable. If money has to pass through several platforms and wallets before it can be used, a higher nominal return may not be enough to make the product compelling.
SOFIE is meant to reduce that friction by linking bank deposits and stablecoins inside one flow. Users can hold SOFIE while waiting for a trading opportunity, then convert into SoFiUSD when they want to move onchain. In practical terms, SoFi is not only trying to attract deposits into the bank. It is also trying to keep those funds inside its own product stack when customers move into digital asset trading and blockchain transfers.
For traditional banks, that suggests customer competition may extend beyond checking accounts, savings accounts, and credit cards into the full digital asset lifecycle. For stablecoin issuers, the challenge is how to build stronger retention power on top of transfer efficiency, application coverage, and user experience.
Why tokenized deposits matter after the GENIUS Act
Changes in the U.S. stablecoin regulatory framework offer another way to read the SOFIE launch.
The GENIUS Act, passed in 2025, created a federal regulatory framework for payment stablecoins and set rules for issuers, reserves, and business activities. Under that framework, payment stablecoin issuers face restrictions on directly paying interest to holders. That makes the legal and economic differences between payment stablecoins and bank deposits more important.
That does not mean stablecoins cannot generate economic value through any structure, and it does not support a blanket conclusion that all tokenized deposits will receive looser treatment. The legal character, yield design, and regulatory obligations of any product still depend on its actual structure. SOFIE stands apart because it is designed as a tokenized representation of a bank deposit, not as a payment stablecoin repackaged as a savings product.
In April 2026, the FDIC released a proposed rule that specifically addressed the regulatory treatment of tokenized deposits. The proposal said that if a liability meets the statutory definition of a deposit, its regulatory treatment should not change solely because of the recordkeeping method or the technology used. That shows regulators trying to handle the connection between traditional finance and blockchain technology based on the legal substance of assets and liabilities. The document was a proposal at the time, not a final conclusion that automatically applies to every tokenized product.
From an industry perspective, that direction could open new room for banks. They can explore tokenized deposits within the existing prudential framework, then use separate stablecoin products to connect with onchain payments and trading. Stablecoin issuers, for their part, still need to balance compliance, redemption design, liquidity, and application networks. The two models do not necessarily replace each other. They may end up serving different functions inside the same financial system.
The business model test is only beginning
SoFi has been expanding its crypto business in recent years, and SOFIE is another step in that buildout by combining deposit yield with stablecoin transferability. For consumers, the design could reduce the complexity of moving money among bank accounts, trading venues, and external wallets. For banks, it offers a way to extend deposit relationships into onchain trading and payment activity.
Still, several practical questions remain before the model can scale. First, the 4.40% APY is a floating rate. If rates move lower, user willingness to keep funds in the product will show whether demand is driven by short-term yield or by the broader service experience. Second, conversion and transfers are not costless. Supported networks, transaction confirmation speed, account eligibility, and fee arrangements will all shape the actual user experience. Third, once funds move from SOFIE into SoFiUSD or other digital assets, the nature of the asset and its risks change as well. Deposit insurance that may apply before conversion should not be read as continuing protection after conversion.
More broadly, tokenizing deposits does not mean every point of friction between the banking system and blockchain has disappeared. Users still face identity checks, account restrictions, custody questions, network compatibility issues, and the risk of mistaken transfers. Whether the product becomes truly competitive will depend on how clear, reliable, and usable those parts of the process turn out to be.
What SOFIE shows is that banks are starting to give deposits a form that fits more naturally into digital asset environments while keeping their legal basis as bank liabilities. For the stablecoin market, that means competition is no longer only about who can issue more digital dollars. It is also about who can hold onto idle customer cash, meet demand for yield, and offer a smooth conversion path when users want to trade or make payments.
That is why the significance of SOFIE goes beyond placing a 4.40% yield inside a blockchain setting. It raises a deeper market question: when digital dollars need liquidity, yield, and clear legal protections at the same time, where will the line between banks and stablecoins be drawn? The next points to watch are not only user growth and fund size for this product, but also whether other banks introduce similar structures and how regulators refine the rules for tokenized deposits.