
Stripe is no longer easy to describe as just a payments company. That is the central argument in a feature by Will Awang of Duke Fintech, published by ChainCatcher, which follows how Stripe has been repositioning itself around AI, global software businesses and agent-driven commerce.
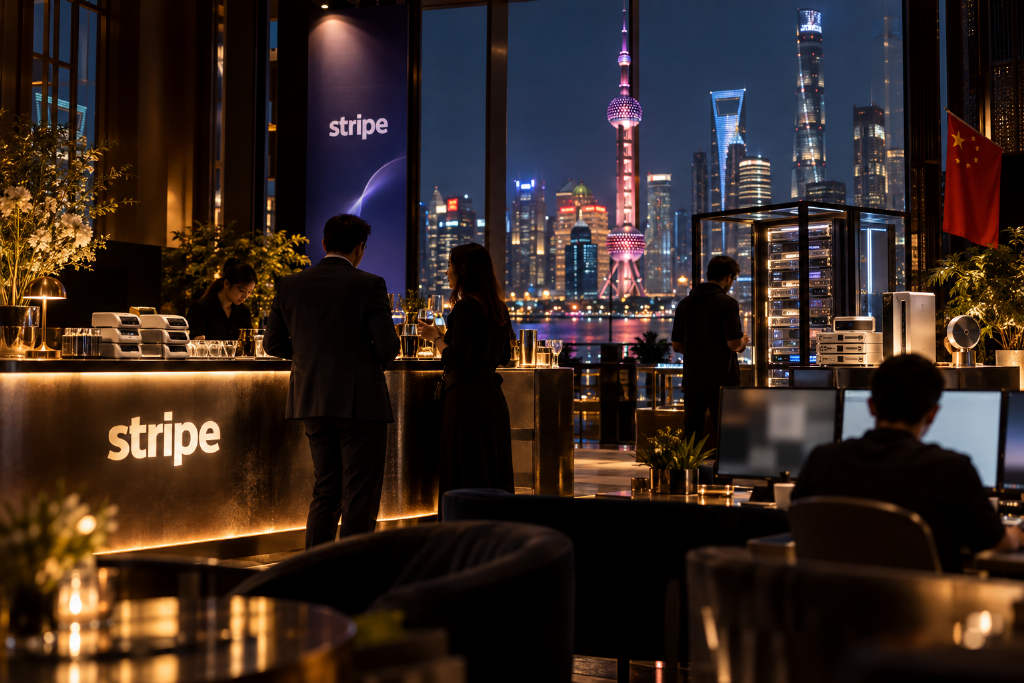
The report opens with two scenes built around the same informal setup: a temporary bar inside a Stripe office and another one recreated at Stripe Tour Shanghai in September 2026, the company’s first tour stop in China. At the Shanghai event, the author interviewed Kevin Miller, Stripe’s head of payments, risk, customer support and global services, who also oversees Agentic Commerce. Much like the first episode of Stripe’s in-house podcast Cheeky Pint, the conversation focused far more on AI than on payments.
From financial infrastructure to infrastructure for the AI economy
The article recalls a June 2025 episode of Cheeky Pint, recorded by John Collison in a makeshift bar at Stripe’s office. His guest was Greg Brockman, Stripe’s first engineer, later its CTO, and then a co-founder of OpenAI after leaving in 2015. Payments barely came up during that conversation. AI dominated the discussion.
Brockman remembered a question from a board member in 2018: if artificial general intelligence was really getting close, AI should already have been creating major economic value, so where was that value? Brockman said it was a fair criticism at the time, but not anymore.
The report says Stripe echoed that shift in an August investor letter, where it described Jan. 1 as the start of a singularity-like turning point because the pace of new company formation had begun to surge in its own data. Stripe has long said its mission is to increase the GDP of the internet. Under current conditions, the article argues, that GDP no longer comes only from websites built for people and click-to-buy checkouts.
At Stripe Tour Shanghai, the company grouped its products into five columns: payments, Radar risk tools, revenue automation, money management and embedded finance. Payments were only one column. The article says Stripe’s own positioning has also shifted over time, from a "financial infrastructure platform" and a "programmable financial services company" to the phrase used at Sessions in April 2026: "economic infrastructure for AI." That same language was still in use in Shanghai in September, with the emphasis moving from enterprise customers to AI itself.
When asked directly whether Stripe is still a payments company, Miller answered that Stripe is fundamentally financial infrastructure. Speaking about the company’s mission to increase internet GDP, he added that this means the part of the economy connected to the internet.
The article notes that Miller spent 17 years at Amazon Web Services, managed S3, and later oversaw AWS global data centers before joining Stripe the previous year. In his view, financial infrastructure and cloud infrastructure share the same foundation, but financial infrastructure requires more than engineering. It also requires understanding how customers grow, which markets they want to enter, and how quickly they need to move.
The author draws a sharper conclusion: payments are just the flow. What Stripe has been building over the past year sits above that flow.
Global from day one means more than accepting payments
One of the report’s recurring themes is that the new generation of AI companies no longer treats international expansion as a later phase. In Shanghai, Stripe described the change as a move from "going global" to being "global from day one."
The article gives MiniMax as an example. It said the company sent only two engineers, finished the integration in two weeks, and then commercialized its product in more than 100 countries.
Miller said this is the biggest shift he has seen among Chinese companies: they now build for global delivery from the start, and their first question is how to deliver capability worldwide.
Stripe’s own numbers in the article point in the same direction. From 2024 to 2025, total cross-border payments among users in Greater China rose about 48%, while the number of newly launched AI businesses increased 78%. Sarita Singh also said 14 of the top 100 AI companies on Stripe’s platform came from China. Many Chinese firms, the article said, reached multiple overseas markets in just six to 12 months.
But global from day one does not mean automatically global. Each new market adds another local payment method, another tax regime, another fraud pattern and another dispute framework. The old way was to go country by country: set up an entity, register for tax, find a local acquirer. For AI companies, the article says, that path is too slow.
Stripe’s answer is to take over that whole stretch of work. Atlas handles company formation. Managed Payments lets digital goods businesses enter 195 markets, with Link acting as merchant of record for payments, indirect tax, fraud prevention, disputes and customer support. After that come multi-currency settlement, foreign exchange, treasury services, issuing and lending.
The business logic for Stripe is plain in the article. If a company registers, sells, gets paid and converts currency through Stripe, Stripe sits in a larger share of its revenue stack and becomes harder to replace.
For Chinese AI companies, that changes the starting question. The old question was where to set up a company first. The new one is whether the product can be sold to the world immediately. Payments are only one part of that path.
Token accounting is becoming a core Stripe product area
The report then shifts to monetization. It describes three eras of software pricing. In the on-premise era, software was sold through perpetual licenses and seats. In the cloud era, usage and subscriptions were added. In the AI era, billing units multiply: agents, workflows, single actions, outcomes, credits, committed usage and tokens. A marker on the curve says, "we are here."
Abhi Tiwari said in the interview that the most common setup now is a hybrid one: a base subscription first, then usage-based charges once limits are exceeded. The newer direction is outcome-based pricing.
That model is also the hardest one to standardize. Melina Lee, general manager of enterprise customers for Greater China at Stripe, said Chinese AI companies are growing quickly across foundation models, content, consumer image and video products, and enterprise-facing services, but pricing remains one of their biggest headaches. What counts as an outcome, how much that outcome is worth, and how much cost sits behind it can differ from one customer to the next. That makes it difficult to standardize and hard to scale. Stripe, she said, wants to help companies see the cost behind every outcome.
Miller compared token spend to a new kind of cloud bill. He said the early stages of cloud computing looked a lot like large-scale token consumption today. At some point, companies inevitably ask where the money is actually going. He said he had seen this in cloud computing, where a set of companies emerged to map cloud spending back to each line of business so someone could truly control the budget. In his view, OpenRouter is already doing that kind of work, and tokens will soon translate directly into dollar or other currency outlays that enterprises must treat seriously.
The article says Stripe did not wait for someone else to build this business first.
The first step is metering. In the five-column product chart shown in Shanghai, Metronome sits in the first row of the revenue automation column. Stripe signed the acquisition in December 2025 and closed it in January 2026, with a reported price of about $1 billion. Metronome’s customers include OpenAI, Anthropic, Databricks and Nvidia, all companies that bill users by tokens or GPU seconds.
Then comes pricing. Stripe Billing now supports token-based charging. AI applications can add a markup on top of the underlying model cost. The system tracks current model pricing, records each customer’s token usage, and applies the markup to the bill.
The third step is routing, which is where OpenRouter enters. According to the article, Stripe wants control over both revenue and cost. Its large acquisitions in the past mostly helped businesses get paid or manage money. Acquiring OpenRouter moves Stripe to the other side of the ledger, into AI spending. Lee added that OpenRouter can route traffic between expensive and cheaper models so companies spend money where they should.
The author ties these three pieces together as metering, pricing and routing. Once they are combined, an AI company’s tokens sold and tokens spent can be reconciled inside one system. That matters because, for many AI businesses, tokens are both the largest cost and the main unit of revenue. Whoever keeps that record is close to the operating center of the company.
Why Stripe needs businesses beyond transaction fees
The article also lays out the financial case for expanding past payments. Payments are one of the easiest parts of the stack to compare on price, and rates usually face downward pressure. Stripe processed $1.9 trillion in 2025, according to the report. If it relied only on payments, it would be difficult for revenue to outgrow payment volume over the long term.
Products outside the payment rail look different. Stripe’s annual disclosures, as cited in the article, say its revenue suite — including Billing, Tax, Invoicing and the newly added usage-billing platform Metronome — is expected to reach a $1 billion annualized revenue run rate in 2026, up from $500 million a year earlier. The article notes that once these products are embedded in a company’s workflows, they are much harder to replace.
The report adds that many internet and SaaS companies from the previous cycle grew up on Stripe. Now AI companies are doing the same. It says 88% of the Forbes AI 50 are Stripe customers. At Sessions in 2026, Stripe broadened its task from collecting money to supporting global growth for AI companies, helping enterprises adapt to AI, preventing token-related abuse and making agents part of the economy.
Using Patrick Collison’s phrasing, the article says AI is the biggest platform shift in the economy since the internet, and most of the companies and startups in this wave are being built on Stripe.
Agentic Commerce Suite aims to make merchants legible to agents
The report then turns to merchant distribution in an AI environment. People browse storefront pages. Agents do not. They need structured data: what the product is, how much it costs, whether it is in stock, and how payment works. Much of the effort merchants once put into home pages, product detail pages and checkout pages cannot be read directly by an agent.
In Shanghai, Stripe compressed the answer into three terms: product discovery, checkout, and risk and payments. That is the three-part chain behind Agentic Commerce Suite. Merchants upload product catalogs to Stripe, select which AI agents they want to sell through, and Stripe pushes those products into those AI platforms while supplying checkout, payment and risk infrastructure. Pricing, inventory, fulfillment and customer relationships remain with the merchant.
Stripe also quantified the integration burden. The article says that in the past, every new AI agent connection required a separate interface build, separate catalog formatting and separate API adaptation, which could take six months. Now it becomes a single integration.
Most of the merchants onboarded so far are established brands. The article lists Coach, Kate Spade and URBN, including Anthropologie and Urban Outfitters. Distribution partnerships matter even more. Shopping checkout inside Microsoft Copilot runs on Stripe. At Sessions in April, Stripe also announced a partnership with Meta for checkout directly in Facebook ads and another with Google to let merchants sell through AI Mode and Gemini.
Stripe is not betting on one AI platform, the article says. It is betting that every platform eventually needs checkout. There is also a defensive logic here. If more purchases happen inside AI platforms and checkout is controlled elsewhere, Stripe risks losing transaction volume. Rather than predict a single winner, it wants as many platforms as possible to share its checkout layer.
Still, that only solves one side of the problem. Agentic Commerce Suite handles how merchants are discovered by agents and how orders get placed. The harder question sits on the other side of the transaction: if a human is no longer the one pressing the purchase button, who gets to decide whether the money can be spent?
Agentic Payment turns the wallet into a permissions system
The article’s interview with Miller moves from merchant infrastructure to consumer authorization. When asked what the iPhone moment for agents might look like, Miller recalled a co-worker saying that his mother had recently started asking whether she should use Instinct or Muse. If even older generations are comparing agents, Miller said, that moment may already be here.
His expectation is that within three to four years, most internet transactions will involve agents in some way, either in product discovery or at checkout.
He also gave a personal example. On the day of the interview, he needed to send an anniversary gift, was away from home and did not even know which florist to choose, so he asked an agent to order flowers for him.
But if an agent is going to spend on someone’s behalf, the first issue is simple: who gets the card number? Give it to the agent and the agent could be compromised. Give it to the merchant and you create another point of leakage. Stripe’s answer is what the article calls a shared payment token, or SPT. With the customer’s authorization, the agent can initiate payment using the customer’s preferred payment method without exposing the underlying credential.
The flow described in the report works like this. A buyer first uses an existing payment method on an AI platform or adds a new one. After the buyer authorizes the purchase, a purpose-limited payment token travels with the order request to the seller. Stripe shares fraud signals with the seller at the same time, and the seller uses that token to charge the payment. The token is valid only for a specified merchant, comes with amount and time limits, and can be revoked. In effect, the merchant receives a bounded spending authorization while the underlying payment credential remains hidden.
The article says Miller had written about the idea in a Stripe blog post the previous year. In traditional e-commerce, whoever holds the card is often treated as the trusted party. But agents act on behalf of people, so trust cannot be guessed. It has to be explicitly granted, bounded and enforced in code. In Shanghai, Miller gave a simpler version: Stripe Link is the final gate for money leaving the account. Even if many agents shop or execute tasks for him in the future, he still decides through Link which money can actually be spent.
The broader debate around agent payments often treats protocol, wallet and tokenization as separate systems and focuses on which standard might win. The article argues that Stripe and its partners have already assembled those parts into live products.
Meta’s personal agent Muse, launched on Sept. 8, uses Link’s agent wallet for payment. Every purchase requires the user to confirm the total amount in the chat interface, and Muse does not see the payment information itself. Microsoft Copilot’s checkout flow uses Stripe payment tokens.
Even so, having a wallet does not mean every door is open. Less than two weeks after Muse went live, Amazon blocked it, according to the article, saying Muse had entered its website without permission and had not identified itself as an automated program while browsing. So an agent that can pay still needs merchants willing to let it in. That, the article says, is exactly why Agentic Commerce Suite matters.
On the merchant side, Stripe wants to become the interface through which agents enter commerce. On the buyer side, it wants to become the gate that grants agents the right to spend. There is a deeper shift here for Stripe as well. Historically, it mainly stood on the merchant side while banks and wallets controlled the buyer’s credentials. In the agent era, Link gives Stripe a direct role in how consumers delegate payment authority to machines.
The article compresses that shift into one line: the wallet no longer carries cards. It carries permissions.
Risk models are becoming a product of their own
The final part of the report focuses on risk. As agents begin participating in transactions, sellers increasingly face software rather than a person. Many of the old behavioral cues used in e-commerce to infer trust no longer work the same way. Sellers need stronger signals from accounts, payment activity and the broader network.
Stripe has already turned what it sees into models. The article says the company released its own payments foundation model in 2025, trained on tens of billions of transactions. It can detect subtle signals in each payment that hundreds of specialized models miss. After deployment, the model improved attack detection rates for large merchants by 64%.
That capability now extends beyond payments into token abuse. Sarita Singh, who leads Stripe in Greater China, Southeast Asia and Korea, said the company has seen a sharp rise in AI misuse over the past six months. Once software maps directly to real compute cost, free trials become a new attack surface.
The article also cites Stripe President Will Gaybrick from an a16z podcast. He said that at one point, one in every six free-trial signups at Cursor was malicious. ElevenLabs, using Stripe’s signals, blocks about 2,000 such signups a day.
That changes where risk controls need to sit. They move forward to registration, where the question is whether one person is opening multiple accounts, and they also extend into usage, where the question is whether a customer will burn through tokens and then fail to pay. In the article’s phrasing, e-commerce fears stolen cards; AI companies fear stolen compute.
Stripe has separated that judgment layer into a standalone business. Companies can buy Radar even if they do not use Stripe to process the payment itself. DoorDash began using it in 2024 to score non-Stripe transactions.
The article describes a self-reinforcing loop. The more transactions Stripe handles, the more account, payment and token-usage data it sees. More data improves the models and makes risk decisions better. Better decisions help Radar sell into transactions that do not run through Stripe, which then sends back new data.
That is a different business model from a payment company that charges only for access to the rail. Stripe, the author argues, is now turning the data left behind by the rail into a business of its own. For AI companies, the difference between payment providers is no longer only price and coverage. It is also which provider understands accounts, tokens and agents better, and which one can judge what is actually happening inside a transaction.
Stripe is now serving not only companies and people, but machines
The article adds one more change: not just what Stripe sells, but who uses Stripe. In 2025, traffic from agents to Stripe documentation increased by more than 10x and now accounts for nearly 40% of visits. In Stripe’s command-line tools, 70% of API resource requests come from agents. Stripe Projects, introduced in April 2026, goes further by letting agents provision databases, hosting and domains, receive keys and pay through Stripe.
If Muse represents agents buying for consumers, the article says, Projects represents agents buying infrastructure for software. Stripe is no longer dealing only with people and companies. It is increasingly dealing with machines themselves.
From cashier for software to infrastructure for the AI economy
The report closes by returning to Stripe’s product overview. Most of the capabilities discussed in the piece are not in the payments column at all. In Will Gaybrick’s words, as quoted by the author, Stripe has grown from one payments product into roughly 30 products.
For an AI company selling software, Stripe starts at company formation through Atlas and then stays in the flow as the business sells globally, bills by token, settles revenue and converts currency. With OpenRouter, it also begins to touch model cost on the expense side.
For a traditional brand that wants to plug into AI, Agentic Commerce Suite pushes products into agents and gives the merchant checkout and payment infrastructure behind the scenes.
For consumers, Link and payment tokens answer a third question: when an agent buys on a person’s behalf, who gets to authorize the spending? Beneath all of these lines sits Radar, making judgments about legitimacy and abuse.
The author ends with a simple distinction. Payments are the flow. Stripe used to focus on making sure the money moved from buyer to seller. Now it wants to manage where that money comes from and who is allowed to spend it: revenue, cost and permission. In the previous generation, Stripe was the checkout counter for software companies. In this one, the company wants to be the infrastructure layer for the AI economy.