
UBS said higher wafer prices are not just a byproduct of a cyclical recovery. In its Sept. 18, 2026 global wafer industry report, the bank argued they may be the condition required to unlock new capacity, as supply-demand balances for both 12-inch and 8-inch wafers tighten over the next two years.
The firm said manufacturers may need to see price increases of 40% to 50% or more before they seriously consider expanding capacity for 2028 and beyond. UBS kept Buy ratings on Shin-Etsu Chemical, GlobalWafers and Siltronic, and rated SUMCO Neutral.
Profitability remains below prior-cycle levels
According to UBS, wafer makers are still cautious on expansion after the downturn from 2023 to 2025. Industry operating margin now stands at 12.3%, while return on equity is 6.8%, both well below the 18.3% and 19.1% recorded during 2017 to 2022.
UBS said large customers will likely need to offer better pricing if they want suppliers to commit capital to new capacity. Otherwise, wafer shortages could end up constraining growth across the broader semiconductor industry.
Utilization is expected to keep rising through 2028
UBS raised its 12-inch wafer demand growth forecast for 2026 to 11% from 9%. It expects growth of 14% in 2027 and 13% in 2028. For 8-inch wafers, the bank forecasts demand growth of 11% in 2026, 9.9% in 2027 and 8.8% in 2028.
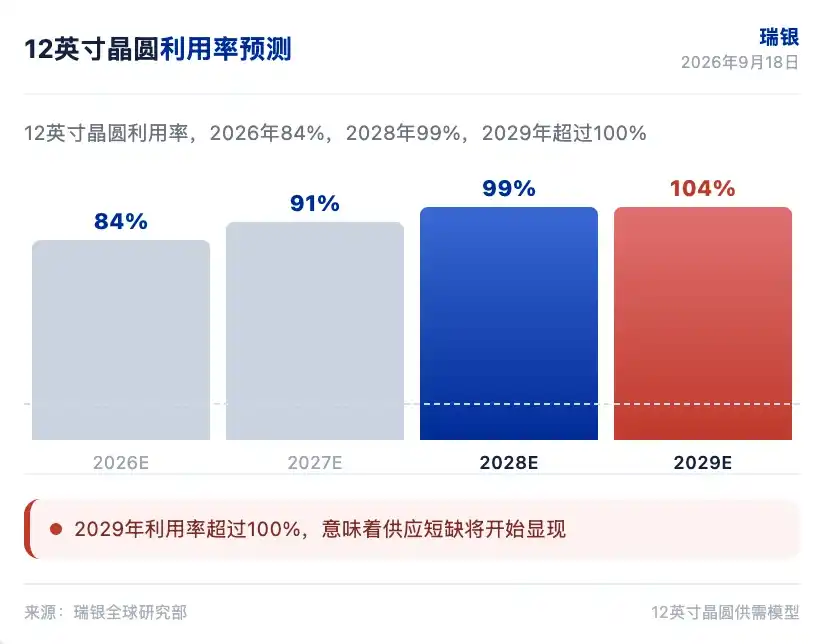
Its utilization assumptions were also revised higher. For 12-inch wafers, UBS now projects utilization of 84%, 91% and 99% from 2026 to 2028, versus prior estimates of 82%, 88% and 94%. For 8-inch wafers, utilization is projected at 80%, 90% and 97%.
UBS said the upward revision mainly reflects stronger customer restocking demand and faster DRAM capacity expansion. It added that supply-demand conditions in 2027 should be tighter than in 2026, with 2028 approaching full utilization for 12-inch wafers.
UBS sees shortages emerging in 2029 without expansion
The bank expects wafer prices could rise more than 20% a year in 2027 and 2028, similar to the 2017-2018 upcycle. But UBS said that kind of annual increase may still fall short of the level needed to trigger fresh investment in capacity.
Based on industry feedback cited in the report, suppliers may require price increases of 40% to 50% or more before considering expansion plans for 2028 and later. UBS described this as the central tension in the sector: customers want more supply, while producers remain reluctant after the previous downturn damaged profitability.
If no new capacity is added, UBS estimates utilization would reach 103.7% in 2029, and shortages would begin to appear that year. The report said that if wafer prices rise more than 20% in 2027 but producers still do not expand, the 2029 supply gap could become the next bottleneck for semiconductor industry growth.
Chinese competition seen as manageable
UBS said Chinese wafer makers are expanding, but their impact on global supply-demand conditions in 2027 and 2028 should be limited. The bank said the main opportunity for Chinese suppliers may be new mature-node logic fabs in China, while leading Chinese logic and memory customers still prefer overseas wafers because of yield considerations.
For non-Chinese customers, UBS said it is difficult to adopt Chinese wafers at scale in mature-node foundry production because that would require requalification. In advanced logic and memory, the report said Chinese wafers still lag on performance.
UBS identified NSIG as China’s largest wafer maker. Its average selling price for 12-inch wafers is $54, versus an industry range of $100 to $120, which UBS said indicates most of its shipments are still non-production wafers. On that basis, the bank said Chinese suppliers remain limited in high-end wafer competitiveness and are unlikely to materially reshape the global high-end supply chain in the near term.
Ratings and target price changes
UBS maintained Buy ratings on Shin-Etsu Chemical, GlobalWafers and Siltronic, while keeping SUMCO at Neutral.
For GlobalWafers, UBS cut its target price to TWD 1,750 from TWD 2,000, based on 7.5x forward price-to-book, down from 8.5x previously. The bank also lowered its earnings per share forecast for 2026 by 7%, and for 2027 and 2028 by 14%, though it said sales growth should accelerate in the fourth quarter of 2026 and in 2027.
UBS raised Siltronic’s target price to EUR 120 from EUR 105. SUMCO remained Neutral with a target price of JPY 4,000.
The bank also said the wafer sector’s price-to-book ratio has pulled back to 2.6x from 3.3x in July 2026, placing it around the midpoint of the past decade’s 1.0x to 4.0x range. UBS said that pullback offers a buying opportunity tied to a structural upcycle.
Report note
This article is based on a整理 and interpretation by Chaoxiang Research of a third-party brokerage report from UBS dated Sept. 18, 2026, combined with public market information. The ratings, target prices, earnings forecasts and related views cited in the piece are those of the brokerage analysts and represent the position of their institution, not that of Chaoxiang Research, and do not constitute investment advice.
Market risk remains. Investment decisions should be made independently. The article should not be used as a basis for buying or selling any security.