tokenized tre2026-09-11 07:45:52Token Terminal data shows USYC added $2 billion in market cap over the past yearTokenized U.S. Treasury products posted notable market cap growth over the past year, according to data cited by ChainCatcher from Token Terminal. USYC, a product under Circle, led the category with a $2 billion increase in market capitalization, ranking first among comparable assets. iBENJI and USDY followed behind, with market cap gains of $1.7 billion and $1.5 billion, respectively. BlackRock’s BUIDL recorded a $552.5 million increase during the same period, placing fifth in the rankings. The figures highlight the relative expansion of several leading tokenized Treasury products over the last 12 months, based on the dataset referenced in the report.900
yield-bearing2026-09-03 09:23:59Alea Research: Sky, BlackRock, and Circle Control Half of Yield-Bearing Stablecoin MarketAlea Research reports that Sky, BlackRock, and Circle collectively command half of the yield-bearing stablecoin market. The market comprises 26 products with a total size of $21.43 billion, with the top three — sUSDS (23.8%), BUIDL (16.7%), and USYC (12.7%) — accounting for 53.1% of the share.880
BlackRock2026-08-31 03:24:17BlackRock's BUIDL Retakes Top Spot in Tokenized Treasuries With $2.8B Market CapBlackRock's tokenized U.S. Treasury fund, BUIDL, has regained the top spot among tokenized Treasury products, with a market cap of roughly $2.8 billion. According to Token Terminal, BUIDL now accounts for about 18.5% of the $15.1 billion tokenized Treasury market, narrowly ahead of Circle's USYC. The $15.1 billion total represents the combined size of the tokenized Treasury market tracked by that data provider. USYC had briefly overtaken BUIDL in late August, reaching roughly $2.9 billion versus BUIDL's $2.7 billion, but it lost the lead again this week. The close race between the two funds has meant the top position has changed hands more than once in the past month. Both funds are among the largest in the tokenized Treasury category. Tokenized Treasury funds allow institutions to hold short-term U.S. government debt on a blockchain and offer around-the-clock settlement. That makes them a popular option for institutions seeking to park idle cash or provide yield-bearing collateral. The story was originally reported by BeInCrypto and carried via Techub News.930
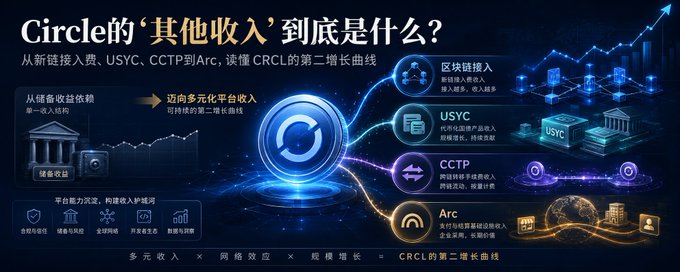
Circle2026-08-08 15:26:54Inside Circle’s “other revenue”: how chain integrations, USYC, CCTP and Arc shape CRCL’s second growth trackCircle’s core business is still easy to grasp: users hold USDC, and the company earns interest on reserves invested mainly in short-dated U.S. Treasuries, money market funds, and cash-like assets. What is harder to parse is the “other revenue” line in Circle’s filings, which management has used to support a broader pitch that the company should be valued as an internet financial platform rather than only as a stablecoin issuer tied to reserve yields. According to the company’s SEC disclosures cited in the source material, that line combines several very different kinds of revenue: one-time blockchain integration fees, recurring maintenance and subscription payments, software licensing, USYC fund management fees, redemption fees tied to Circle-issued assets, blockchain rewards, transaction revenue from infrastructure such as Cross-Chain Transfer Protocol, and Arc-related accounting revenue from token presales. That mix matters because growth in the line item does not automatically mean growth in predictable, high-quality recurring income. The article tracks Circle’s other revenue across 2025 Q4, 2026 Q1, and 2026 Q2, reviews which chains were launched in each period, and highlights why quarterly figures can be uneven. It also argues that the higher 2026 guidance appears to include about $160 million of ARC token presale revenue, a category that should not be treated the same way as recurring platform income when investors assess CRCL.1930
Circle2026-07-22 12:08:13Circle Overtakes BlackRock as Tokenized Treasury Market Tops $11 BillionCircle’s USYC has grown to about $2.2 billion, overtaking BlackRock’s BUIDL at roughly $2 billion, as the tokenized U.S. Treasury market reaches a record above $11 billion.1820
stablecoins2026-07-09 19:13:13Stablecoin Market Tops $315 Billion as Circle’s USYC Leads Weekly GainsThe stablecoin market has climbed to $315.94 billion, with the top 10 tokens controlling nearly 94% of total value. USDT remains dominant, USDC approaches $80 billion, and Circle’s USYC posted the strongest weekly gain at 13.9%.1690
yield-bearing2026-07-02 10:23:33Yield-Bearing Stablecoin Supply Slumps 15% in Q2 as Treasury-Backed Products GrowIn Q2 2026, the supply of yield-bearing stablecoins fell 15% quarter-over-quarter, driven by contractions in sUSDe and sUSDS. Meanwhile, Treasury-backed products such as BUIDL, USYC, and USDY continued to expand, signaling a shift toward lower-risk yield assets amid macroeconomic uncertainty.1360
yield-bearing2026-07-02 10:23:33Yield-Bearing Stablecoin Supply Drops 15% in Q2 as Treasuries-Backed Products GainIn Q2 2026, the total supply of yield-bearing stablecoins fell by 15%, driven by contraction in crypto-native tokens such as sUSDe and sUSDS. Meanwhile, Treasury-backed tokenized products including BUIDL, USYC, and USDY continued to expand, signaling a shift in investor preference toward asset-backed yields over purely crypto-native instruments.1320