


China’s A-share refinancing market stayed active in the first three quarters of 2026. Wind data cited in the report show 359 companies completed equity financing during the period, raising a combined 750.86 billion yuan. Of that total, IPOs accounted for 216.32 billion yuan and refinancing deals brought in 534.55 billion yuan. Private placements remained the dominant refinancing tool, with 175 completed deals raising 465.49 billion yuan, or 62% of all equity financing.
Activity was uneven across the year. January saw 19 completed placements raising 125.8 billion yuan, while June had 22 deals worth 91.1 billion yuan. August recorded 27 completed placements, but total proceeds were only 27.9 billion yuan. The report notes that a handful of large transactions were still enough to reshape monthly fundraising totals.
The structure of the market also shifted. On one side, central state-owned enterprises such as China Shenhua and SPIC Energy continued to use share issuance for asset consolidation. On the other, companies in semiconductors, hardware equipment and smart vehicles directed placement proceeds toward capacity expansion, research and industrialization projects. The report says the 2026 market looked less like a simple financing wave and more like a combination of industrial consolidation and an active refinancing function in the capital market.
Large asset injections supported fundraising
Measured by total proceeds alone, private placements were down from the same period in 2025. The report says that comparison needs to be read against an unusually high base. In 2025, four capital replenishment placements by Bank of China, Postal Savings Bank of China, Bank of Communications and China Construction Bank contributed 520 billion yuan, lifting the prior-year figure sharply.
As of Sept. 29, 2026, the number of A-share private placement deals had risen 48% year on year, while fundraising volume had fallen 39.8%. In other words, the market did not lack projects. What was missing were the ultra-large bank capital replenishment deals seen a year earlier.
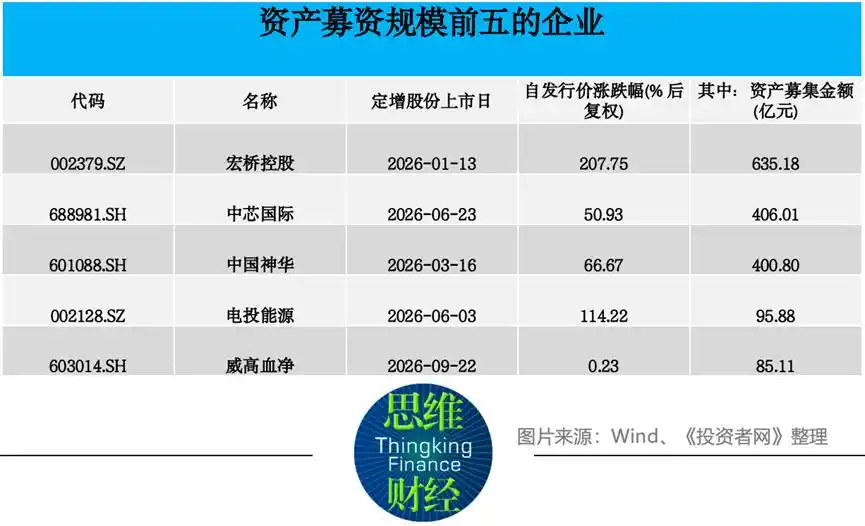
Among 170 companies that had completed share issuance under private placements, total fundraising reached 422.408 billion yuan. Cash financing accounted for 141 deals and 214.718 billion yuan. Asset financing accounted for 29 deals and 207.690 billion yuan. Asset deals represented only 17% of the cases, but nearly half of the money raised.
That concentration was driven by several large transactions. Hongqiao Holdings ranked first in asset financing with 63.52 billion yuan. Semiconductor Manufacturing International Corp. followed with 40.6 billion yuan. China Shenhua raised 40.08 billion yuan through asset financing, and SPIC Energy raised 9.59 billion yuan.
The logic behind those deals was similar. China Shenhua acquired stakes in 12 companies under China Energy Group through a share issuance, covering coal, coal-fired power, coal chemicals, ports and shipping. SMIC acquired the remaining 49% stake in SMIC North, turning it into a wholly owned subsidiary. SPIC Energy acquired Baiyinhua Coal and Power to strengthen synergies across coal, new energy, power generation and electrolytic aluminum.
Other transactions carried the same internal consolidation feature. Huahong Grace injected Huali Micro, Xiamen Port Development injected terminal assets, and Qingdao Doublestar injected tire-related assets. The report says these deals differ from traditional financing aimed at filling funding gaps. Listed companies gained internal group assets while also addressing horizontal competition and improving business structure. For central and local state-owned enterprises, the capital market is becoming an important vehicle for group-level asset consolidation.
According to the report, central and local state-owned enterprises completed 58 private placements and raised 189.9 billion yuan, equal to 45% of the total raised by companies that had completed share issuance. State-owned asset financing alone accounted for 82.06 billion yuan. The report adds that the figure would be higher if deals involving exits by state-owned shareholders and minority stake consolidation, including SMIC, were included.
Cash placements clustered in semiconductors and advanced manufacturing
Cash placements showed a clearer industrial direction than the large asset injection deals.
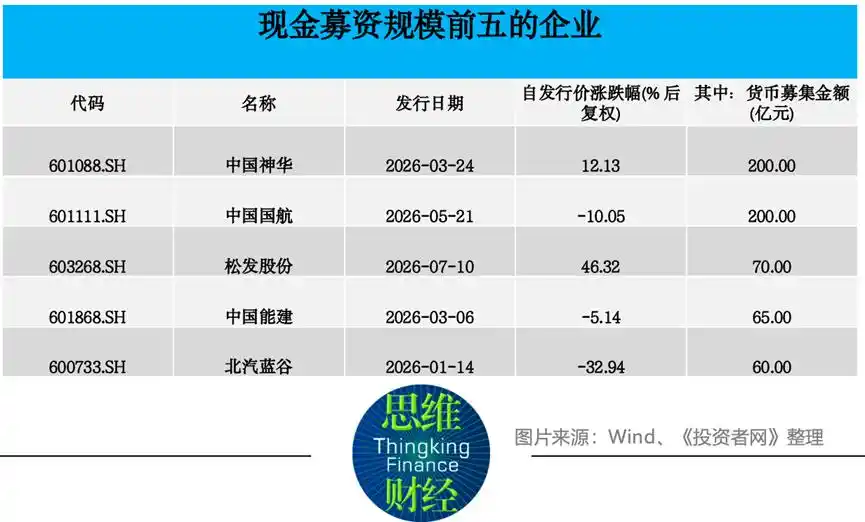
Among the 141 cash financing cases, 94 were mainly used for specific projects and raised 133.42 billion yuan. Another 21 were supporting financings tied to mergers and restructurings, raising 47.69 billion yuan. A further 26 placements included working capital replenishment, totaling 33.61 billion yuan. By that breakdown, more than 60% of cash placement funds in the first nine months ultimately went into specific projects.
Industry data pointed the same way. Based on Wind’s first-level industry classification, 19 semiconductor companies completed cash placements and raised 82.27 billion yuan in the first nine months of 2026. Hardware equipment companies completed 25 such deals and raised 34.32 billion yuan. Together, those two groups accounted for 44 companies and 116.6 billion yuan, making them the most concentrated destinations for cash placement funding.
Private companies were a major part of that trend. The report says private enterprises completed 85 cash placements and raised 82.78 billion yuan, with about 90% of the proceeds used for project financing. The money mainly flowed into hardware equipment, semiconductors, software services and machinery.
Several examples were highlighted. Piotech raised 4.6 billion yuan for a high-end semiconductor equipment industrialization base and a frontier technology R&D center. Longsys raised 3.7 billion yuan for AI high-end memory, storage controller chip research and high-end packaging and testing capacity. Changchuan Technology raised 3.127 billion yuan for semiconductor equipment-related business.
Smart vehicles and new energy were also major destinations. BAIC BluePark raised 6 billion yuan for new energy vehicle model development, an AI intelligent platform, and smart driving and electrification system development. Energy China raised 6.5 billion yuan for solar thermal, energy storage and wind power projects. Songfa raised 7 billion yuan mainly for green and intelligent high-end shipbuilding projects.
The report links that funding pattern to the structure of the A-share market this year. In the first half of 2026, the STAR 50 Index rose 64.25% and the ChiNext Index gained 35.58%, both well ahead of the CSI 300 over the same period. Trading in technology sectors such as electronics and communications was also active. For industries with high R&D spending and heavy capital expenditure, the report says a stronger market environment made it easier to secure longer-term funding through equity financing.
At the same time, merger and restructuring policy support continued to build. Since the start of 2026, the China Securities Regulatory Commission has kept optimizing its review mechanism for mergers and restructurings, while shelf issuance and other refinancing systems have also moved forward. The report says policy support for industrial consolidation, quality asset injections and higher financing efficiency provided a strong institutional base for this year’s private placement market.
Post-issuance performance split sharply
In the current A-share market, completing a private placement does not end the story. For institutions and shareholders that take part, the real test often begins after the new shares are issued.
Among the 170 companies that had completed share issuance, 107 were trading above their issuance price as of Oct. 8, while 63 were below. The average gain was 21.7% and the median gain was 10.2%. Asset-backed placements performed much better than cash deals. Of the 29 asset deals, 26 were up, with a median gain of 42.5%. Cash placements had a median gain of only 5.7%.
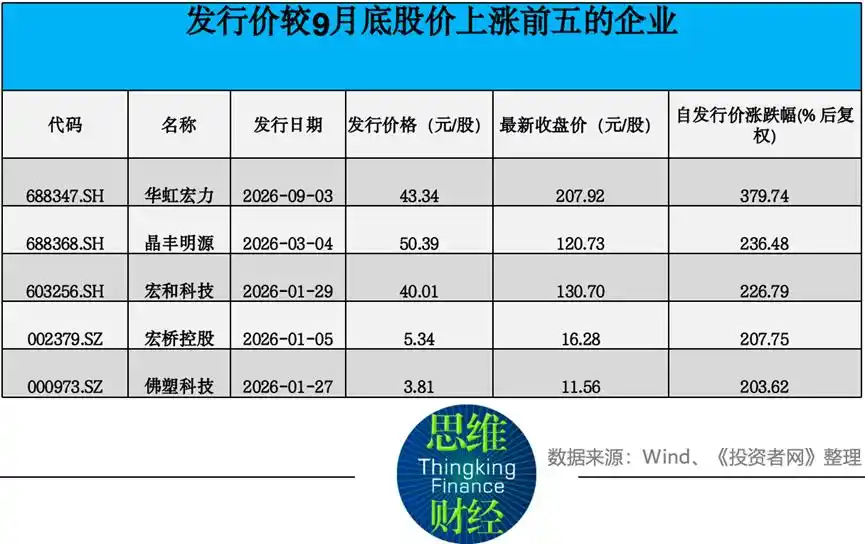
The gap at the stock level was even wider. Huahong Grace was up 379.74% from its issuance price. Jingfeng Mingyuan rose 236.48%, Hongqiao Holdings gained 207.75%, and Fosu Technology rose 203.62%.
On the losing side, Longsys fell 46.08% from its issuance price. JAC Motors dropped 44.93%, Pan Asia Microvent Tech fell 41.65%, and OFILM and BAIC BluePark were down 38.95% and 32.94%, respectively.
Issuance discounts also showed a pattern. Across 141 cash placements, the median discount on the issuance date was 13.5%. For the nine deals with discounts above 30%, the median post-issuance gain reached 54.1%, and all of them rose. By contrast, the six deals issued at a premium had a median return of -1.0%.
Pricing methods mattered as well. Among 107 book-building placements, the median post-issuance move was -2.0%, and 48% of the stocks rose. Among 34 fixed-price placements, the median gain was 24.0%, with 88% rising. In 36 deals involving controlling shareholders, the median gain was 15.1%, well above the 1.4% median for deals without major shareholder participation.
Longsys became a notable example of the downside
Longsys was one of the clearest examples in the report. Its placement price was 560 yuan per share. The stock later kept falling and was trading near 300 yuan per share, down 46% from the issuance price, making it the worst-performing cash placement among deals completed in the first nine months of 2026. The report says the time gap between the placement and subsequent capital operations also created a clear divergence between institutional subscription prices and secondary market prices.
Other cases showed a different outcome. Jingfeng Mingyuan completed an issuance in March 2026 at 50.39 yuan per share, and its stock was later trading near 105 yuan. Megmeet, Jiangfeng Electronics and Songfa also recorded sizable gains over their issuance prices.
The report concludes that market feedback on private placements is no longer driven by discount alone. Whether the injected assets are strong, whether projects can generate incremental profit, and whether the issuance price is reasonable may now matter more for post-deal stock performance.
Overall, the first three quarters of 2026 showed several clear lines in the A-share private placement market: large fundraising was concentrated in state-backed restructurings and asset injections; cash placements focused on semiconductors, advanced manufacturing, AI, smart vehicles and new energy; and the secondary market drew much sharper distinctions between projects.
The original article was published by the WeChat account Investor Network - Siwei Caijing and credited to Wu Wei. It also stated that the article was for reference only and did not constitute investment advice.