
In a preview report dated Sept. 11, 2026, Goldman Sachs said it is sticking with a Neutral rating on Micron Technology and a 12-month price target of $1,100. Against Micron’s Sept. 10 close of $977.41, that implies 12.5% upside. Goldman bases that target on 18x normalized earnings per share of $62.
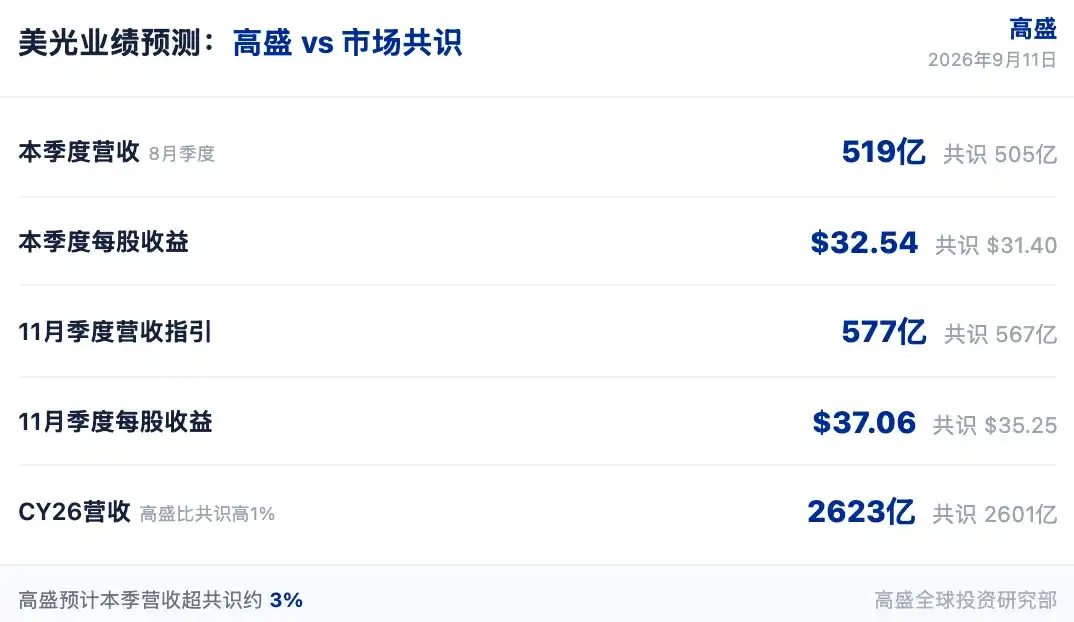
Goldman is looking for Micron to post quarterly revenue of $51.9 billion, gross margin of 87.3%, and EPS of $32.54. Each of those numbers sits above market consensus.
Quarterly estimates top consensus
Analyst James Schneider said investors are zeroed in on strategic customer agreements, or SCAs, capital return plans, and trends around HBM4 products. Goldman’s view: DRAM and NAND supply is still tight. So it expects Micron to turn in another strong quarter, with both reported results and guidance having a shot at landing above what the market expects.
For the current quarter, Goldman models revenue at $51.9 billion, versus consensus of $50.5 billion. It puts gross margin at 87.3%, against 87.0% consensus, and EPS at $32.54, compared with $31.40 consensus. On Goldman’s math, revenue is roughly 3% above consensus.
The report said investor positioning remains broadly positive because DRAM and NAND are still tight. But there is another side to it. Some investors are uneasy about longer-term supply growth from competitors, especially in China.
November-quarter guidance also seen above consensus
For the November quarter, Goldman expects Micron to guide to $57.7 billion in revenue, ahead of the $56.7 billion consensus. It sees gross margin at 88.1%, versus 87.5% consensus, and EPS at $37.06, compared with consensus of $35.25.
Goldman said Micron’s November-quarter revenue guidance should point to low-double-digit sequential growth, helped by product mix and incremental pricing.
On pricing, the bank said DRAM momentum is still holding up. Investor expectations remain high, though less stretched than they were in earlier quarters. In HBM, Goldman put Micron’s current market share at about 20%, and said investors expect the company to hold or grow that share.
CY26 to CY29 forecasts were revised higher
Goldman’s CY26 revenue and EPS estimates are 1% and 3% above consensus, respectively. It now expects CY26 revenue of $262.3 billion, versus consensus of $260.1 billion. For CY27, it forecasts revenue of $267.6 billion against consensus of $264.7 billion. For CY28, Goldman projects revenue of $280.2 billion, compared with consensus of $260.6 billion.
The bank also added a CY29 forecast: revenue of $284.5 billion and EPS of $174.22.
Goldman said the higher revenue and EPS estimates come from its latest DRAM demand view and recent pricing trends. For CY27, its revenue estimate is 4.9% above its prior forecast, while its gross margin estimate is 80 basis points above the earlier figure.
SCAs and capital return are key market focus areas
Goldman said investors expect Micron to sign more strategic customer agreements, and they are closely watching how pricing in those deals stacks up against earlier agreements.
Per the note, the pricing structure in those agreements directly affects revenue visibility and margins over the next several quarters.
As for capital return, Goldman said investors will be watching management’s comments on share repurchases very closely, especially now that restrictions tied to the CHIPS Act have been lifted. The report said Micron’s repurchase capacity had earlier been limited by the CHIPS Act. Now that the restriction is gone, investors are looking for signs of a large-scale buyback. Goldman said the size and timing of any capital return plan are major variables for the stock.
HBM4 roadmap and China supply remain central to the debate
On the HBM roadmap, Goldman expects Micron to comment on its HBM market share and give more detail on HBM4 shipments and HBM4E sampling.
The bank said investors expect Micron to maintain or expand its current HBM share of about 20%. The speed of HBM4 shipments and the progress of HBM4E samples will be the main markers for judging Micron’s standing in next-generation high-bandwidth memory competition.
Goldman listed upside risks including continued execution on the HBM roadmap, market share gains, and a sharp rise in HBM content within AI accelerators. Downside risks include continued DRAM share gains by CXMT, which Goldman identified as a Chinese DRAM maker, and negative pressure on pricing dynamics. Put simply, the report said CXMT’s expansion could weigh on DRAM prices.
Goldman added that after Micron reports earnings, the stock discussion is likely to remain centered on long-term customer agreements, excess capital return, and long-term supply increases, especially from China. In Goldman’s view, the bigger long-run argument is about how long the current pricing advantage from tight supply can hold and whether capacity expansion by Chinese rivals will alter the supply-demand balance.
Disclosure in the source material
The source article said it was a compilation and interpretation by Chaoxiang Research of a third-party broker report from Goldman Sachs dated Sept. 11, 2026, together with public market information. It also said the rating, price target, earnings forecasts, and related judgments cited in the article were the views of Goldman’s analyst and reflected only that institution’s position, not the view of Chaoxiang Research, and did not constitute investment advice.
The source also said that markets involve risk, decisions should be made independently, and the article should not be used as a basis for buying or selling any security.