
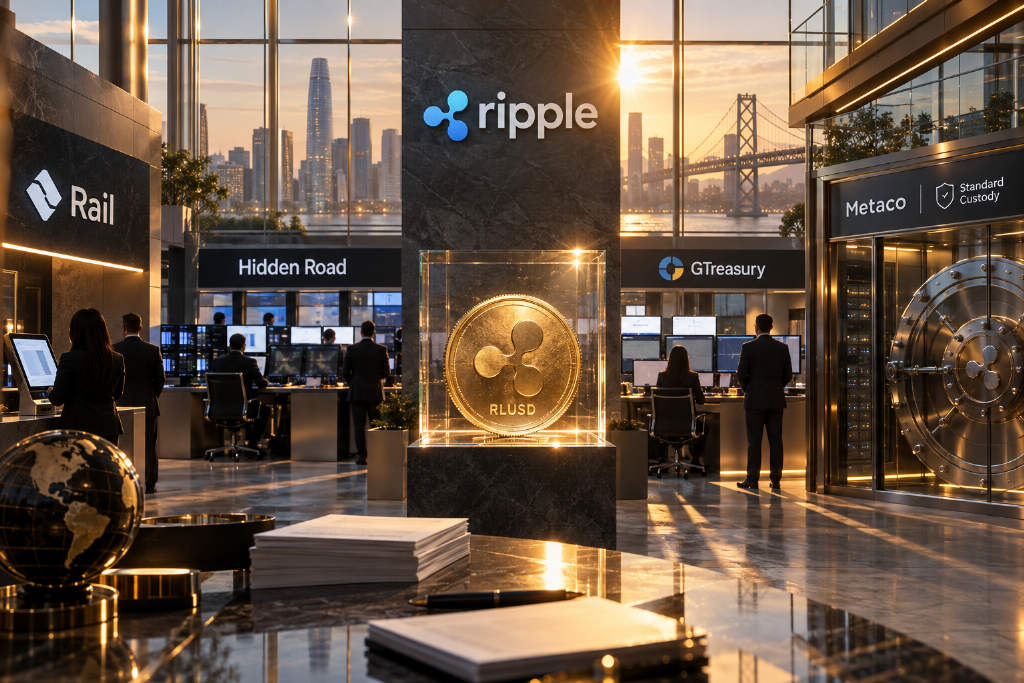
Ripple announced three major acquisitions in 2025: Hidden Road for $1.25 billion, Rail for $200 million, and GTreasury for $1 billion. The disclosed consideration across the three deals totals $2.45 billion.
For a company best known for cross-border payments, buying a prime broker, a stablecoin payments platform, and a treasury management system can look like a scattered strategy. Put those deals back into the lifecycle of money, and the structure is easier to read. Rail connects the entry and exit points for funds. Hidden Road brings the credit, financing, and clearing functions that sit behind institutional trading. GTreasury places Ripple inside the systems where enterprises decide how cash is managed and deployed. Add the custody capabilities Ripple had already built and its dollar stablecoin RLUSD, and a broader institutional financial stack starts to come into view.
Seen that way, Ripple is turning the account arrangements, asset protection, liquidity, credit support, and corporate workflows that stablecoins rely on into services it can offer itself. The company has not just bought products. It has acquired operating businesses, customer relationships, and institutional service capacity, giving it a stronger position in how stablecoins are used and who earns revenue around that usage.
To understand Ripple today, the timeline has to extend well beyond 2025. The burst of acquisitions that year looks more like a concentrated release of groundwork laid over more than a decade.
From XRP to banks: the problem Ripple originally set out to solve
Ripple’s history starts with the relationship between the company and the network.
XRPL went live in June 2012. In September of the same year, a team that included Chris Larsen and Jed McCaleb formed a company initially called NewCoin. It was soon renamed OpenCoin, later became Ripple Labs, and gradually came to be known simply as Ripple. The XRPL founding team also gifted a large amount of XRP to the company, tying Ripple closely to XRP’s development and holdings from an early stage.
Any serious discussion of Ripple needs to separate at least four things:
- Ripple: the company providing enterprise financial services and technology, best analyzed through customers, products, revenue, profit, and capital allocation.
- XRP: the native digital asset of XRPL, best analyzed through utility, liquidity, supply and demand, and value capture.
- XRPL: the public blockchain network, best analyzed through transactions, asset issuance, settlement, and developer activity.
- RLUSD: the dollar stablecoin issued by a Ripple-affiliated entity, best analyzed through reserves, redemption, distribution, and real-world usage.
Owning XRP does not mean owning equity in Ripple. Growth in Ripple’s business, growth in XRPL usage, and market demand for XRP are separate questions.
In its early years, Ripple focused on capital efficiency in cross-border payments. A payment company that needs to pay out in multiple markets often has to pre-fund accounts through banks and local partners. Cash ends up scattered across jurisdictions, constrained by time zones, business hours, settlement cycles, and local rules. Liquidity can be tied up before the actual transaction happens.
By 2017, Ripple’s product lineup had broken different payment problems into separate tools. xCurrent handled payment messaging and institutional coordination. xRapid used XRP to source cross-border liquidity. xVia offered standardized connectivity. xRapid later evolved into On-Demand Liquidity, or ODL.
The bridge-asset path for XRP was straightforward: convert the sending currency into XRP, move it across borders, then convert into the receiving currency, reducing the need for long-term pre-funding in the destination market.
That addressed a real pain point. But moving value on-chain is only one segment of the payment chain. Delivering usable funds to an end customer still requires deep enough markets on both sides, consistent quotes from liquidity providers, reliable bank accounts, compliant counterparties, and clear accountability when trades or payments break. What customers ultimately care about is whether the money is usable on arrival, what the all-in cost is, and who is responsible if something goes wrong.
Faster asset transfer can change the way liquidity is arranged. Funding cost, risk bearing, and last-mile delivery still need to be solved elsewhere.
Ripple spent years building around those constraints. Its $55 million Series B in 2016 brought in investors including Standard Chartered, SBI, Accenture Ventures, and SCB Digital Ventures, the venture arm of Siam Commercial Bank. In 2018 it launched Xpring to support XRP- and XRPL-related projects through investments, incubation, acquisitions, and grants. In 2019 it invested in Bitso to support a Latin American liquidity network. In 2021 it announced the acquisition of a 40% stake in Tranglo to expand cross-border payment links in Asia.
Using capital to build out an ecosystem has long been part of Ripple’s playbook. The shift is that the company initially invested around payment corridors and XRP utility, then moved into a broader set of institutional financial services.
Expansion under regulatory pressure
The U.S. Securities and Exchange Commission sued Ripple in 2020. By August 2025, the parties had withdrawn their appeals, bringing the case to a close. A civil penalty of about $125 million and an injunction against violations of securities registration rules remained in effect.
That history changed Ripple’s operating environment and left behind useful case studies from its earlier business model. MoneyGram had taken an investment from Ripple and used related technology before the two companies ended their partnership in 2021. MoneyGram’s SEC filings disclosed that 2020 included $50.2 million in related-party market development fees from Ripple.
The point is not that one kind of demand excluded another. It is that demand driven by customers paying for a product, demand supported by commercial incentives, and volume reinforced by capital relationships are different things, even if they coexist. They can have very different durability.
Still, Ripple’s later moves should not be reduced to a simple story of “the case ended and then the company started buying aggressively.” In May 2023, well before the final end of the litigation, Ripple acquired Metaco for $250 million. In June 2024 it completed the acquisition of Standard Custody & Trust Company. Both deals happened before the legal process fully wound down.
Metaco added institutional custody technology and customer relationships. Standard Custody added a regulated trust entity and an important organizational foundation for stablecoin operations.
Banks and asset managers entering digital assets first need an operational control framework: who holds the keys, who can initiate transfers, who reviews them, how permissions and limits are set, how assets are segregated, how records are reconciled, and how exceptions are handled. Metaco put Ripple inside those institutional workflows. Once custody technology is embedded in bank systems, the relationship can become sticky. A bank using a custody platform does not mean the client assets become Ripple’s own balance-sheet assets.
Standard Custody gave Ripple a way to move new business forward on top of a New York-regulated limited-purpose trust company. When that acquisition closed, Jack McDonald also became head of Ripple’s stablecoin business.
RLUSD officially launched on Dec. 17, 2024, with issuance initially on XRPL and Ethereum.
By then Ripple’s menu had clearly widened. It could offer an XRP-related liquidity route, a dollar stablecoin, and custody for the assets moving through those channels. Clients could choose based on currency, corridor, and internal policy.
That was a strategic change. The range of financial business Ripple could participate in was no longer confined to a single bridge-asset pathway.
The 2025 acquisition wave: connecting funds, credit, and enterprise workflows
In 2025, Ripple began paying larger prices for critical business capabilities. Hidden Road, Rail, and GTreasury each placed the company in a different fee position: institutional financing and clearing, money movement and conversion, and enterprise treasury software and workflows.
Hidden Road: entering the credit and collateral network
When the acquisition was announced, Hidden Road said it cleared about $3 trillion annually and served more than 300 institutional customers. Ripple had already participated in Hidden Road’s Series B and was also a client of the platform. The progression is visible: invest first, use the service, then expand the capital commitment.
After closing in October 2025, Hidden Road was renamed Ripple Prime. By that point, Ripple had disclosed that RLUSD was being used as collateral in some prime brokerage products, and that certain derivatives clients were choosing to hold balances in RLUSD.
That extended stablecoin usage into margin, collateral, and financing arrangements.
In a payment context, a stablecoin may come in and go out quickly. In a collateral context, institutions may hold balances for longer to maintain positions and access services. Those are different reasons for holding an asset, and they can lead to different balance behavior.
If a stablecoin is accepted across trading and financing networks, clients have another reason to own it: the asset supports their broader financial activity. Hidden Road gives Ripple credit, clearing, and financing capabilities around capital flows, and gives RLUSD deeper institutional utility.
The $3 trillion figure, however, was a disclosed multi-asset clearing volume at the time. It should not be read as RLUSD payment volume, nor as evidence that the entire business has moved to XRPL.
Rail: linking on-chain rails to fiat money flows
Rail brought virtual accounts, collections, fiat-to-stablecoin conversion, third-party payments, and enterprise treasury flows.
For payment service providers, those capabilities map to day-to-day operating questions: how incoming client money is identified, under whose name it is recognized, how funds are pooled, when conversion happens, who can be paid out, and how the supporting transaction data is passed through the chain.
That means enterprises can continue to send and receive fiat while a service provider uses stablecoins in the middle of the process. What the customer buys is a money movement service, not necessarily wallet management, exchange accounts, or direct on-chain operations.
The November 2025 acquisition of Palisade added wallet-as-a-service, wallet configuration, and transaction-signing capabilities. By March 2026, Ripple described how Rail and Palisade were being integrated: named virtual accounts and wallets for collections, and a single platform for holding, converting, and paying out in fiat or stablecoins.
That made Ripple’s payments offering look more like a deliverable treasury and funds-operations service. The exact account structures, treatment of third-party funds, and customer scope still depend on the contracting entity, local rules, and approvals from partner banks.
Rail’s strategic value lies in connecting stablecoins to the account setups, collections, and payout processes customers actually use.
GTreasury: entering the place where companies decide how to use money
GTreasury may carry the longest strategic tail of the three deals. Ripple said the platform served more than 1,000 customers across 160 countries, and confirmed the acquisition had closed in December 2025.
Treasury systems sit inside the daily work of cash visibility, cash forecasting, payment approvals, FX exposure management, financing, and investment. They connect to banks, ERP systems, approval permissions, and audit records. They also sit on top of budgets that already exist.
When a company decides whether to use stablecoins, the question extends far beyond initiating an on-chain transfer. Accounting treatment, operator permissions, transaction limits, consolidation of bank cash with on-chain balances, and updates to cash forecasts all need to fit within existing controls.
GTreasury gives Ripple a way into clients at the point where those questions are actually handled.
In April 2026, Ripple Treasury launched Digital Account Management and Unified Treasury, bringing digital-asset balances, valuations, transaction records, and fiat position views into one system. Ripple disclosed that the treasury platform helped clients process $13 trillion in payments in 2025.
That figure reflects the scale of existing workflows, including traditional money movement. It is not stablecoin payment volume, and it should not be added directly to Ripple Payments volume.
The more valuable strategic question is how much of that existing workflow could become a path for new services when enterprises are allocating cash, handling cross-border payments, or moving funds across internal entities.
Ripple Treasury added Solvexia in January 2026, bringing in financial automation, reconciliation, and regulatory reporting. The direction remained consistent: move digital assets into the financial operations enterprises already run instead of leaving them in isolated pilots.
2026: from acquisition list to institutional adoption
By 2026, product launches and client developments began to provide clearer tests of the strategy.
In March, Ripple said its Payments business had processed more than $100 billion cumulatively and was active in more than 60 major markets. In July, it launched Ripple Mint, offering institutions a portal for RLUSD minting, redemption, and operations, while linking fiat and on-chain transaction status through APIs, webhooks, and consistent reference IDs.
Those capabilities make it easier for stablecoins to be integrated into payment companies, trading venues, and internal enterprise systems. For institutions, traceability, reconciliation, and automation are not side features. They shape the scale at which a product can be used.
As of Oct. 8, 2026, Ripple’s website showed RLUSD circulation at about $2.46 billion and reserves at about $2.60 billion. That is meaningful scale, but still materially below the outstanding supply of USDT and USDC. Ripple’s importance in the stablecoin sector therefore has to be judged in the context of the wider service set built around funds, not from RLUSD balances alone.
Another development with stronger financial-infrastructure characteristics emerged in collateral networks. In January 2026, Ripple and LMAX announced a multi-year partnership under which Ripple would provide $150 million in financing to support RLUSD usage in LMAX’s institutional trading infrastructure. The announcement described the arrangement as financing, which should not be characterized as an equity acquisition.
On Oct. 12, Standard Chartered said its DFSA-regulated DIFC branch had launched institutional custody for RLUSD on XRPL. It also said it was working with Ripple and LMAX on collateral mirroring. The idea is to map the value of eligible collateral into trading venues so institutions can keep assets in bank custody while still using them, reducing the need to move them directly onto trading platforms. The custody service is live, while the collateral linkage still requires documentation, testing, and approvals.
The logic is straightforward. Institutions need a way to solve custody, market access, credit support, and counterparty exposure together. Stablecoins are starting to appear inside that combined solution.
There is also an important distinction in who is holding what. BNY said in 2025 that it would act as the primary reserve custodian for RLUSD, meaning the reserve assets that support issuance. Standard Chartered’s service, by contrast, covers RLUSD tokens held by institutional clients. Reserve safety, client-asset custody, and collateral use at trading venues are linked functions, but they sit behind different responsibility lines.
Ripple Prime kept expanding. In August 2026, it launched a Delta One business supporting total return swaps tied to U.S.-listed equities, indices, and digital assets. The company also disclosed regulatory net capital of more than $1 billion and the completion of a $275 million private placement of senior unsecured notes.
In October, Brevan Howard expanded its relationship with Ripple Prime to use multi-asset prime brokerage, clearing, and financing services. DriveWealth said it would integrate around stablecoin settlement, cross-border funding, and custody while exploring stock-financing cooperation.
Some of those lines are already in service, some are being integrated, and some remain exploratory. The common direction is clear: one institution can build multiple service relationships with Ripple around money, assets, and credit.
That is where Ripple’s product set begins to show observable common-customer use cases.
Capital relationships are expanding too, but they are not all the same thing
Ripple’s investment and acquisition strategy needs to be viewed alongside its shareholders, portfolio companies, and partners, but those relationships should not be collapsed into one category.
In November 2025, Ripple announced a $500 million strategic equity investment at a $40 billion valuation. Participants included funds managed by Fortress-affiliated entities, entities affiliated with Citadel Securities, and firms including Pantera, Galaxy, Brevan Howard, and Marshall Wace.
In March 2026, CoinDesk, citing people familiar with the matter, reported that Ripple had launched a share buyback of up to $750 million at pricing implying a roughly $50 billion valuation. A buyback provides liquidity to existing shareholders and employees; it is different from fresh financing.
Outside those capital relationships, Ripple continued to invest in business nodes tied to use cases.
- Regional payments and acceptance: Bitso and Tranglo, linked to local money networks and liquidity.
- Market liquidity: Keyrock, linked to market making, OTC, and trading services.
- Trading-infrastructure financing: LMAX, linked to stablecoin collateral and settlement.
- Fund and tokenization technology: ZILO and Licuido, linked to registration, issuance, and collateral usage.
In March 2026, Keyrock announced a Series C led by SC Ventures with continued support from Ripple at a $1.1 billion valuation. In August, Ripple invested in ZILO and Licuido, extending its reach into fund-share registration, issuance, and collateral mobility, while saying RLUSD could serve as the dollar cash leg in delivery-versus-payment flows.
Equity investments, financing arrangements, technology partnerships, and customer contracts each carry different rights and responsibilities. They may create business synergies, but the commercial result still has to be tested case by case.
Across Ripple’s broader development arc, though, the direction is becoming more concentrated: enable institutions to hold assets, access liquidity, use credit, and settle related activity in digital dollars.
Standard Chartered illustrates the long arc of that relationship building. It participated in Ripple financing in 2016, then in 2026 offered RLUSD custody. Product adoption cannot be explained by shareholding links alone, but the ten-year span does show how institutional relationships and service capability can accumulate across multiple market cycles.
Where the business value may sit
Ripple’s significance starts with the fact that it can participate in more lines of business where customers exist, budgets exist, and there are clear reasons to pay.
Payments can charge around collections, payouts, and conversions. Custody can charge for technology, operations, and asset servicing. Treasury software ties into recurring subscriptions and enterprise workflows. Prime brokerage brings clearing and financing fees. RLUSD adds reserve-related income. The actual allocation and scale of those revenue streams depend on contracts and legal entities.
They are different economic models. Together, they create multiple growth paths.
The original analysis offers a simple order-of-magnitude illustration rather than a forecast: if a stablecoin averages $2.5 billion in circulation and reserve gross yield is 4% annualized, that points to roughly $100 million in gross interest a year before distribution, custody, operations, and compliance costs. That is not Ripple’s actual revenue and it is not an interest-rate prediction.
The point is that judging a company valued in the tens of billions requires looking beyond circulating stablecoin balances and including its service mix, customer footprint, and capital resources.
Another advantage for Ripple is the depth of the client relationships these products can reach. A payment rail connects to a transaction. A treasury management system participates in daily funding decisions. Custody and prime relationships touch asset safety, credit terms, and risk management. The deeper the service goes, the more systems, processes, and responsibilities a client has to revisit if it wants to switch providers.
If product integration works, existing clients may become a channel into additional services. Clients also have a reason to reduce duplicate integrations, duplicate reconciliation, and coordination across multiple vendors.
That is where the longer-term value of the acquisition set may lie: placing multiple financial services inside business processes that run continuously and can produce repeatable paid relationships.
Integration, however, has a cost. Institutions often want to preserve optionality across banks, issuers, and liquidity sources to manage concentration risk. Ripple is both promoting its own asset and providing infrastructure around it, which means customers will want clarity on routing choices, related-party issues, pricing, and exit arrangements.
How open Ripple remains while expanding its own business may shape how wide a client base the platform can ultimately serve.
Capital resources also need separate analysis. Ripple has previously disclosed sizeable XRP holdings and escrow arrangements, which matter for understanding its financial resources. But token market value, deployable cash, operating profit, and private-market equity pricing each mean different things. Public information is not sufficient to split Ripple’s valuation cleanly into how much comes from XRP-related assets and how much comes from operating businesses.
The longer-term test is whether those resources can be converted into durable customer revenue and risk-adjusted returns.
How to test the strategy from here
Ripple has already completed a visible business expansion and has started to show institutional partnerships that span more than one product. Those are concrete developments.
Its licensing network has expanded as well. In January 2026, Ripple obtained an EMI license and Cryptoasset Registration from the U.K. Financial Conduct Authority. In July, it received full MiCA CASP authorization from Luxembourg’s CSSF. The U.S. Office of the Comptroller of the Currency gave a proposed national trust bank a preliminary conditional approval in December 2025, but opening still requires the conditions to be met and final approval to be granted. Different entities, products, and money activities remain bounded by separate licensing and banking approvals.
From that base, the original analysis proposes three ways to judge Ripple’s next phase.
First is demand quality. How much sustained RLUSD balance and actual usage comes from institutions with no investment tie to Ripple? How much incentive spend is needed to drive volume growth? Do customers stay after promotions end? The history with MoneyGram remains a useful lens for measuring demand quality today.
Second is integration quality. After acquisitions close, how many customers actually adopt a second or third product? Do treasury clients add payments? Do prime clients use custody? How do retention and unit operating costs change as the product set broadens? Those questions say more about synergy than placing every logo on one architecture slide.
Third is capital quality. As financing and derivatives activity expands, credit risk, funding cost, and liquidity demands rise with it. Haircuts, concentration, and stress scenarios will directly shape returns. The capital backing stablecoin reserves also needs to remain clearly separated from the group’s other capital and operating funds.
Those questions also reinforce a separate point: Ripple’s business development should not be conflated with XRP value capture. RLUSD issuance, software subscriptions, and financing income do not automatically convert into proportional XRP demand. Even when business uses XRPL, the way fees and reserve requirements interact with supply and holding demand still needs its own analysis.
Look back across the timeline and the progression is layered rather than random. Ripple first tried to improve cross-border fund transfers. It then moved into safekeeping of assets, followed with a regulated digital dollar, and then expanded into the systems that decide how money is allocated, pledged, and financed.
On that basis, Ripple now has a credible claim to being an important participant in the institutional stablecoin market, with enough reach to influence business models and operating standards. How much value the combination ultimately creates will depend on execution and operating results.
The source article said the analysis was compiled from public materials available through Oct. 15, 2026, with all amounts in U.S. dollars. It cited Ripple announcements, XRPL materials on network history and its relationship with Ripple, SEC case documents, MoneyGram’s 2022 Form 10-K, BNY’s reserve-custody announcement, Standard Chartered and Ripple materials on RLUSD institutional custody and collateral mirroring, the LMAX partnership announcement, FCA registration records, the OCC’s preliminary conditional approval notice, Keyrock’s Series C financing, Ripple’s RLUSD transparency page, CoinGecko market data, and reporting from Reuters, The Wall Street Journal, and CoinDesk. The source also noted that RLUSD transparency data is dynamic, business volumes should retain their original dates and definitions, and that buybacks, financing arrangements, and equity investments carry different meanings. It also stated that the commentary was based on public information and did not constitute investment advice.