
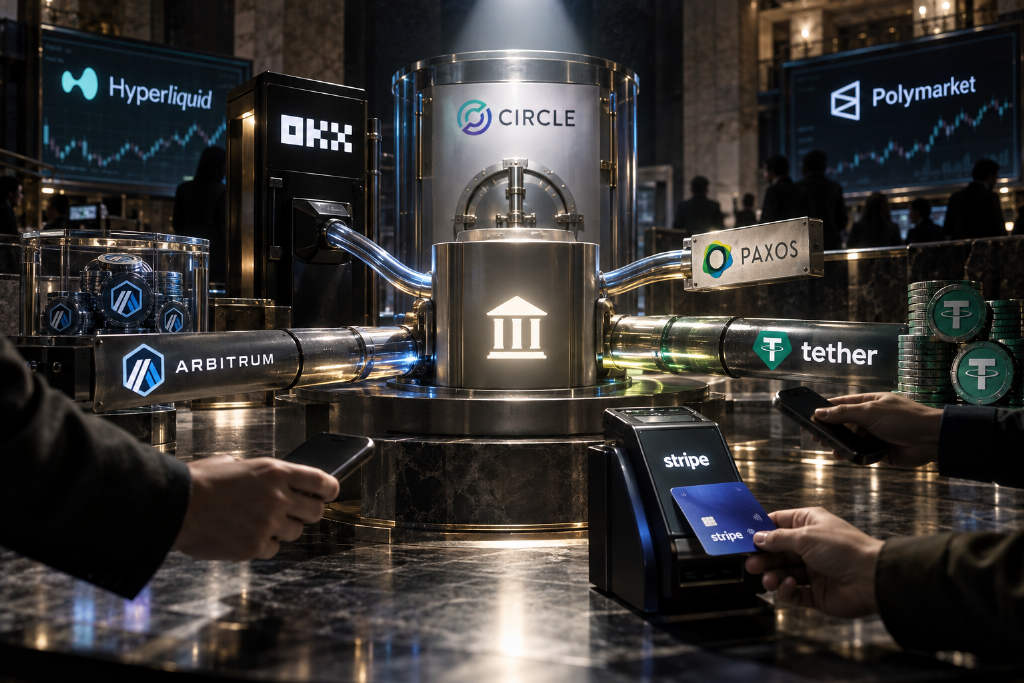
Three developments on Oct. 6, 2026 pointed in the same direction for stablecoins.
Arbitrum One launched USDG natively and joined the Paxos-led Global Dollar Network. At the same time, ArbitrumDAO put forward a governance proposal to add another 100 million ARB to the USDG incentive program, with voting still underway. The article says Arbitrum holds about $3.78 billion in stablecoins on-chain. Global Dollar Network’s pitch is blunt: 「Stop funding their profits」.
On the same day, OKX said it had completed a new strategic financing round at a $25 billion pre-money valuation. The investor list included Circle, QRT, Ripple and SC Ventures, the venture arm of Standard Chartered. OKX said it was not raising money out of necessity and wanted long-term partners instead.
In the same window, Stripe stablecoin lead Henri Stern said the company plans to roll out stablecoin cards to more than 100 countries by year-end, letting users spend stablecoins from their wallets across Visa’s 175 million merchants. The card processed $1.2 billion last month, up threefold from a year earlier, according to the article.
For the author, the common thread is clear: the stablecoin business is no longer centered only on who issues the token. It is shifting toward who controls distribution, settlement and the interface into real-world payments.
Tether’s profits still set the pace
The article describes Tether as the most profitable stablecoin issuer in crypto. In 2025, Tether posted more than $10 billion in net profit with roughly 300 employees, or about $33 million in profit per employee. The model is straightforward. A user deposits $1 to mint 1 USDT, Tether invests that dollar into U.S. Treasuries and other reserve assets, and keeps the spread. Token holders do not receive the interest.
By the end of 2025, Tether directly held more than $122 billion in U.S. Treasuries. Including indirect exposure through repos and money market funds, its total Treasury position stood at about $141.6 billion. The article says that if Tether were treated as a country, it would rank close to the world’s 18th-largest holder of U.S. debt. It also held 127.5 tons of gold and 96,185 BTC. At year-end market prices, those positions were worth about $17 billion and $8.4 billion, with unrealized Bitcoin gains of roughly $3.5 billion.
Using DeFiLlama protocol revenue data, the article says Tether generated about $510 million in 30-day revenue, ranking first. Circle was second at about $210 million, less than half of Tether’s figure. Hyperliquid and Pump.fun were each below one-eighth of Tether’s level.
The author argues that Tether’s edge is not just issuance. It is reach. In convenience stores across Central America, rural markets in Africa and phone top-up shops in Southeast Asia, users may not have access to Coinbase or Circle’s regulated channels, but they can find USDT. Research cited in the piece says about 93% of USDT on Tron sits in ordinary wallets rather than exchanges, while Andersen Institute estimates roughly 95% is held outside centralized exchanges. That distribution is fragmented and hard to choke off through any single gatekeeper.
Circle is growing, but paying more for access
Circle is profitable too, the article says, but under more pressure. In fiscal 2025, Circle generated $2.747 billion in total revenue, up 64% year over year. The problem is not top-line growth. It is how much of that revenue must be shared with distribution partners.
One of Circle’s key metrics is RLDC Margin, the share of revenue left after distribution costs. For 2025, that figure was about 39%. In other words, more than 60% of revenue went to the channels that helped place USDC. Circle’s distribution, transaction and other costs reached $1.664 billion in 2025, up about 64% from a year earlier. Of that, roughly $1.4 billion went to Coinbase alone, up about 51%.
Rates are another pressure point. More than 90% of Circle’s revenue comes from reserve interest, so Fed cuts hit the business directly. In the second quarter of 2026, USDC on-chain transaction volume jumped 151% year over year, but reserve income rose only 5%. Average circulation increased 25%, while reserve yield fell by 66 basis points. The article’s point is that transaction activity and reserve income are no longer moving together. Circle earns on dollars that stay parked in the system, not on how many times those dollars change hands.
After the Fed entered a rate-cutting cycle in 2025, Circle reported adjusted EBITDA of $582 million for the year, but still posted a net loss of $70.1 million because of $424 million in IPO-related stock compensation. Markets were also watching competition. On Sept. 1, shares fell 6% after Goldman Sachs, Citigroup, Bank of America and 21 major global financial institutions said they would form a joint venture to issue a stablecoin. On June 30, Circle stock dropped about 17% in a single day after Stripe, Visa, Mastercard, BlackRock and Google joined OpenUSD. On Aug. 3, Morgan Stanley cut its price target to $38 from $106, citing slower USDC growth, pressure from OpenUSD and the fragility of the reserve-income model.
The article’s conclusion is that Circle’s weakness is not poor compliance or opaque reserves. It is dependence on outside channels to get USDC into users’ hands.
The “last mile” is where stablecoin payments still break down
The analysis frames the commercial challenge as the “last mile.” On-chain settlement can be instant, but that does not mean a payment is complete in the real economy. A token can move from Venezuela to Vietnam in seconds. Converting that token into local currency under local rules, sending it to the right bank account and reconciling the transaction is much harder.
The article breaks the process into four steps. Cross-border transfer is largely solved. FX conversion is manageable. The real bottlenecks are local payment channel integration and compliance reconciliation. A provider serving 10 markets may need to maintain dozens of separate bank and mobile payment integrations. Each one can fail on its own. Each country also has different KYC fields and reporting requirements.
Inbound flows are messy too. A user may send the right dollar amount on the wrong chain, transfer USDT when the merchant accepts USDC, or forget to include a memo. Binance disclosed in 2023 that it handled about 4,000 deposit recovery requests per month and had recovered 7 million USDT in total. Kraken charged as much as $200 per mistaken token recovery.
BCG and Allium cleaned up $62 trillion in public-chain stablecoin transfers and, after removing bot activity, internal transfers and speculative trading, estimated that real economic activity amounted to about $4.2 trillion. Of that, only $350 billion to $550 billion could be identified as payments for goods and services, less than 2% of the total. A European Central Bank survey found that only 0.2% of online merchants in the euro area accept crypto assets, while in-store acceptance has stayed below 1% for two years. Mastercard’s chief product officer said about 90% of stablecoin transaction volume is still tied to crypto trading and that stablecoins lack a clear value proposition in ordinary consumer-to-merchant payments.
The article also cites field research in Yiwu. Most merchants had barely heard of stablecoins. Among those who had used them, some found that traditional settlement qualified for export tax rebates of 6% to 13%, while using USDT meant losing that benefit. In the author’s framing, blockchains solve how money moves, not how goods are delivered and settled in the real world.
Crypto card failures exposed dependence on back-end providers
Several companies trying to solve that last mile have already run into trouble. BitPay’s card stopped accepting new users in June 2023 and had not resumed after three years. Its Trustpilot score stood at 1.2 out of 5, with support limited to email tickets and weekend service cut to four hours. From 2025 to 2026, Dupay shut down because “compliance issues and obstacles in fund circulation could not be fundamentally resolved,” OneKey U Card was suspended, Binance ended card services in Europe and Latin America, and Paris-based Kulipa collapsed into insolvency, affecting more than 20 wallet clients including Solflare and Ready.
Kulipa’s issuer, Monavate, was fined 270,000 euros by Lithuania’s central bank. Once its license was suspended, the product died immediately. Cambodia-based Huione Pay saw its on-chain balance drained to just 990,000 USDT, while its license had already been revoked a year earlier. In January 2026, Polish regulators revoked Quicko’s license. On Feb. 3, cards from CEX.IO, Trustee Plus and IN1 all stopped working on the same day.
The article says these cases had different direct causes but shared one structural weakness: the front-end brand owns the user relationship, while the back-end issuer, license, settlement and compliance nodes decide whether the product survives. Most crypto card projects are not Visa Principal Members. They rely on BIN sponsorship, effectively renting a bank membership. The sponsor handles compliance and settlement, the project handles branding and customers, and the sponsor’s name may barely appear in the cardholder agreement. If the sponsor fails, the card fails. The piece points to Wirecard’s 2020 collapse, which hit early Visa cards from Crypto.com and Binance, and Metropolitan Bank’s 2023 exit from crypto, which hurt BitPay.
It also argues that Visa is often misunderstood. Visa is not simply a toll collector. What it sells is the road system itself: authorization, routing, rules, fraud controls, inter-institution clearing, chargeback handling and a global acceptance network. In a $100 purchase, most of the merchant discount goes elsewhere, and issuers take the larger share through interchange. Visa’s own network fee is only a small slice, but that slice rests on a trust and settlement system built over decades.
By September 2026, Visa’s network was running more than 160 stablecoin-linked card programs, with annualized stablecoin settlement above $20 billion, up more than 15-fold year over year. The article notes that Visa’s CFO did not break the figure out separately on the earnings call because it still represented only 0.12% of Visa’s annual volume, which runs into the tens of trillions of dollars. Even so, the direction is hard to miss: crypto has not displaced Visa. It is paying to use a new stablecoin lane that Visa is building.
Platforms are now charging issuers for access
The article says Hyperliquid made that power shift explicit. In September 2025, Hyperliquid did something unusual: it put the issuance rights for its ecosystem stablecoin USDH out to public tender. Paxos, Frax, Ethena, Sky and Agora were among the bidders, and Native Markets won. At the time, Hyperliquid’s monthly trading volume was close to $400 billion and its chain held $5.7 billion in stablecoins. Dragonfly partner Haseeb Qureshi publicly questioned the process and suggested Native Markets may have been preselected. The article’s point is different. Hyperliquid showed that the platform, not the issuer, could decide who gets to issue on top of its traffic.
USDH ran for eight months and peaked at only $100 million in circulation, versus more than $5 billion in USDC on Hyperliquid. Users did not adopt it at scale. On May 14, 2026, Hyperliquid, Circle, Coinbase and Native Markets announced at the same time that USDH would be discontinued and USDC would return as the platform’s sole settlement asset. Native Markets handed the purchase rights to the USDH brand assets to Coinbase and exited.
On the surface, that looked like a win for Circle. The terms of the new AQAv2 agreement tell a different story, according to the article. First, about 90% of cost-adjusted USDC reserve income flows to the Hyperliquid ecosystem, above the 50% Native Markets had promised during the USDH phase. Second, Circle and Coinbase each staked 500,000 HYPE, with the stake subject to slashing if revenue fails to cover costs. Third, Coinbase handles treasury deployment while Circle handles technical deployment and cross-chain work. They do the work, while the platform keeps most of the economics. Revenue started accruing on Aug. 26, and the first payment arrived on Oct. 3 for $14.58 million.
The article’s reading is that Hyperliquid did not win the war to issue its own stablecoin. It won the war over who gets paid rent to stay on the platform.
Polymarket, Pump.fun and meme platforms are doing the same
Polymarket took a different route. In April 2026, it upgraded its collateral system and replaced USDC.e with its own pUSD. The token is backed 1:1 by USDC and enforced by smart contracts. Users can deposit more than 20 assets, including ETH, DAI and WBTC on Ethereum, USDT and WETH on Polygon, SOL and USDe on Solana, and even USDT on Bitcoin and Tron. The system automatically bridges and converts them into pUSD for settlement inside the platform. Users still see dollars. Polymarket, however, controls the settlement layer while the underlying reserves remain anchored to USDC. The article estimates that reserve income from those assets could bring in at least $50 million a year.
The same logic is spreading to meme platforms. Pump.fun’s treasury has accumulated nearly $2 billion. Co-founder Noah Tweedale said publicly in September 2026 that the team was discussing a native stablecoin and said plainly that decentralization was not the key issue. Control of end users was. The article says Pump.fun first switched trading pairs from SOL to USDC to solve revenue settlement, and the next step would be to keep reserve income inside the platform.
On BNB Chain, Four.Meme did not issue its own token but designated UXUY’s UUSD as the official launch asset and made it the default quote asset in the launch flow. On Solana, LetsBonk partnered with Trump family-linked World Liberty Financial. WLFI offered incentives to developers who launched tokens paired with USD1. On Jan. 3, 2026, LetsBonk recorded 8,800 token creations in a single day, and its market share rose from 3% to 30%.
From issuer-owned to platform-owned settlement
The article divides stablecoin development into three generations.
The first is issuer-owned. Tether and Circle are the clearest examples. The issuer controls the brand, minting rights, reserve income and channel relationships, while distribution partners are paid service providers. Tether used first-mover advantage and low-cost transfers on Tron to spread across emerging markets. Circle used Coinbase and regulatory positioning to win U.S. institutional business.
The second is issuer-as-infrastructure. The article presents Paxos as the clearest example. It issued BUSD for Binance, PYUSD for PayPal and now supports USDG for Global Dollar Network. Paxos has effectively split its business into white-label stablecoins for brands and GDN plus USDG, where reserve income is shared with network participants. In that model, the issuer keeps the license, custody, minting technology, compliance capability and APIs, while the brand, users and increasingly the economics belong to someone else.
The third is platform-owned settlement, which the article says is unfolding now. OpenUSD has brought in more than 140 institutions. The underlying ledger and reserves are shared, while Visa, Stripe and Shopify each control their own use cases and split economics based on traffic contribution. Equity can also be allocated to partners that help grow the network. PayPal has gone further with PYUSDx, a platform that lets companies issue branded stablecoins without directly handling reserves or compliance. PayPal and MoonPay turn issuance into a configurable service exposed through APIs.
The article does not frame this as a simple story of issuers losing and platforms winning. Issuers are also moving up and down the stack. Circle is pushing Arc chain in an effort to build more of the road itself. Stripe is expanding on both sides, with Bridge for stablecoin conversion, the Privy wallet acquisition and a broader stablecoin card push. Visa has launched its Stablecoin Platform to bring stablecoin settlement into its global network. Tether is expanding into payments, its own public chain, wallets and physical infrastructure. Everyone is trying to avoid being pushed back into the role of a low-level supplier.
Market share matters less than control of the interface
The article ends by arguing that USDT and USDC market share no longer tells the whole story, even if the two still account for more than 80% of the market combined.
Issuance rights are becoming less valuable. Distribution rights are becoming more valuable. As bridges and smart routing make it cheaper to switch between stablecoins, it matters less whether a user holds USDT, USDC or pUSD. What matters more is who gets their settlement layer embedded into trading, payments, cross-border transfers and bank clearing. Tether’s moat, in this telling, is not just the size of its Treasury book. It is the millions of wallets and offline touchpoints it has across emerging markets. Circle’s investments in OKX, its willingness to give up about 90% of reserve income in the Hyperliquid arrangement and its effort to build Arc all reflect the same reality: compliance and reserves alone do not guarantee distribution.
The author argues that there will not be one universal stablecoin. There will be many settlement coins tied to specific use cases: exchanges, prediction markets, meme platforms, banks and card networks. They may share the same reserve and compliance base underneath, but they will move through different channels and split economics according to traffic.
The piece also cites a16z’s view that the real opportunity for stablecoins is not to displace Visa at its 150 million merchants, but to serve merchants that Visa never covered in the first place, including individual developers and small software sellers with no website, no legal entity and no credit history. They may not qualify for card acceptance, but they can receive USDT at a wallet address. For machine-to-machine payments between AI agents, the x402 protocol embeds stablecoin payments directly into HTTP requests, making card fees look more like a tax that can be optimized away.
The article’s final point is simple. The battle is moving from who owns the dollars to who controls the interface through which dollars enter the real economy. In that setup, issuers look more like suppliers of raw monetary material, while the platforms that control access, distribution and the last mile are gaining the stronger hand.
