Bernstein
Oct 28, 2026

Bernstein cuts COIN 2026 revenue forecast by 32% and keeps outperform ratings on four platforms

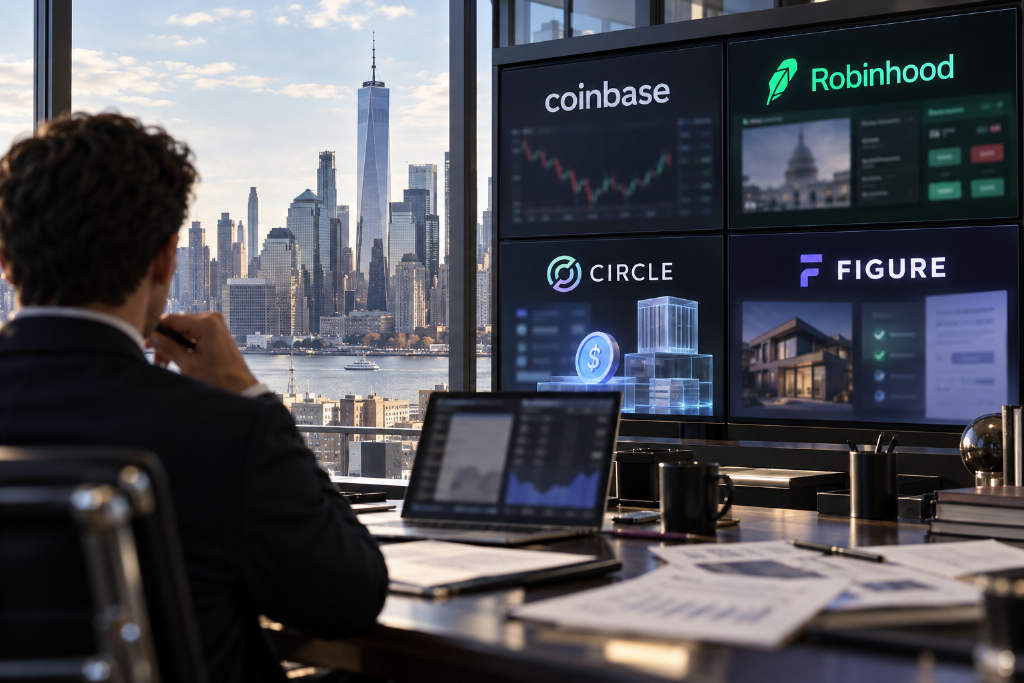
Bernstein cut its 2026 revenue forecast for COIN by 32% in a report dated Oct. 26, 2026, according to a ChainCatcher brief citing Chaoxiang Research. The note also laid out third-quarter expectations for several digital asset platforms: HOOD is projected to post $1.5 billion in revenue, up 13% quarter over quarter; CRCL is expected to report $770 million in revenue, up 10% from the prior quarter; and FIGR is forecast to reach $5.1 billion in loan volume, a 20% sequential increase. Bernstein said spot trading volumes in native crypto remain weak, pushing valuation anchors for the four companies toward newer product lines including prediction markets, perpetual futures, tokenization and lending platforms. Despite the reset in assumptions, the firm maintained outperform ratings on all four names. Its price targets stand at $160 for HOOD, $250 for COIN, $145 for CRCL and $70 for FIGR. The report also said new-product revenue could rise sharply over the next few years, with HOOD’s share climbing from 3% in 2025 to 25% in 2028, while COIN’s could increase from 2% to 19%. Bernstein said the pace of monetization in these newer businesses will drive valuation divergence.
790
Bernstein cuts COIN 2026 revenue forecast by 32% and keeps outperform ratings on four platforms
Figure
Aug 12, 2026

Figure’s valuation gap centers on a business Wall Street still treats like a lender

A joint memo from Artemis Analytics and North Island Ventures argues that Figure is being valued as a conventional balance-sheet lender even as its business shifts toward a lighter marketplace model. The report points to a sharp rise in partner-originated flow, rapid expansion at Figure Connect, and a larger share of revenue coming from platform-style fees rather than capital-intensive lending activity. In the first quarter of 2026, partners accounted for 78% of platform flow, Connect volume climbed to $1.6 billion from $8 million in the fourth quarter of 2024, and ecosystem and technology fees reached 28% of revenue, up from 5%. The authors say that shift matters because Connect lets Figure collect underwriting and distribution fees without taking on the same customer acquisition burden, warehouse funding needs, or credit exposure tied to its legacy model. They also point to two possible supply drivers: a recovery in second-lien home equity lending and Figure’s pending acquisition of Kiavi, which they say could double the company’s first-lien business. The memo argues that current consensus expectations and valuation multiples still do not fully capture that transition, while also laying out risks including weaker housing activity, underwriting becoming more commoditized through AI, pricing deterioration, and governance concerns tied to the company’s dual-class structure.

2350
Figure’s valuation gap centers on a business Wall Street still treats like a lender